Portable Mortgages Sound Great. The Math Is Messier – Shared article

Thank you for tuning in – I am sharing this article featured on my friends blog – lender Christian Carr – visit his lending blog here.

The MOVE Act, introduced by Representative Tom Kean Jr., aims to address homeowners’ frustrations about being locked into low-rate mortgages. However, it only proposes future portable mortgages that won’t retroactively help current borrowers. While this could assist mobility, it doesn’t eliminate financing gaps or selling costs for new homes.

Infographic showing a homeowner selling a $1.2 million home with a $500,000 mortgage at 3%, using roughly $630,000 to $640,000 in net equity toward a $1.6 million replacement home, and still needing about $460,000 to $470,000 in new financing.
A portable mortgage may preserve a low existing rate, but it does not eliminate the financing gap on a more expensive replacement home. Selling costs reduce usable equity, and the remaining balance may need to be financed at a higher rate.
There is a reason H.R. 10028 is getting attention.
It speaks directly to one of the biggest frustrations in housing today: homeowners who are effectively locked into their current homes because the mortgage they already have is far more attractive than the mortgage they would have to take on if they moved.
It’s a real problem affecting household mobility, inventory turnover, and the willingness of would-be move-up buyers to make a change even when life is pushing them in that direction.
So when Representative Tom Kean Jr. introduced H.R. 10028, the MOVE Act, the headline was naturally compelling. The pitch is simple enough for a cocktail conversation: what if a homeowner could take their mortgage with them when they move?
At first glance, that sounds like a breakthrough. If someone has a $500,000 mortgage at 3.00%, why should they be forced to give that up just because they want to buy a different house? Why not let them transfer that loan balance, rate, and remaining term to the next property?
It is a smart political message because it sounds like common sense. It also happens to leave out some very important details.
The first and most important issue is that the bill does not appear to do what many casual listeners will assume it does. H.R. 10028 does not say that every existing low-rate mortgage suddenly becomes portable. It directs Fannie Mae and Freddie Mac to begin purchasing and securitizing conventional mortgages that are designed to allow portability. That is a very different idea.
In plain English, this looks much more like a proposal for a future mortgage product than a retroactive rescue plan for today’s 3% borrowers.
That distinction matters.
A homeowner hearing the phrase “transfer your existing mortgage rate, term, and balance to a new property” could easily assume Congress is trying to let them keep the mortgage they already have. But the economics of the mortgage market make that far more complicated. Existing low-rate mortgages are not simply sitting on a bank’s balance sheet waiting to be modified out of generosity. In most cases, those loans have already been sold into the secondary market and are owned, directly or indirectly, by investors who purchased cash flows based on a certain set of assumptions. One of those assumptions is that when the borrower sells the home, the loan generally gets paid off.
Portable mortgages change that.
That is the overlooked angle here. Portability is not just a consumer perk. It is a borrower option, and options have value. If a borrower can keep a below-market mortgage even after selling the home, the investor loses one of the most common paths to getting principal returned and redeployed at current yields. If market rates are 6.75% or 7.00% and the investor is stuck collecting 3.00% for years longer than expected, that is not a small issue. It is the entire pricing issue.
Which is why portability is not free.
Analysts looking at portable mortgages have already suggested that borrowers would likely pay for that flexibility upfront, probably in the form of a somewhat higher interest rate at origination. In other words, if portable mortgages become a standard future product, the borrower may be buying the right to preserve that mortgage later. Useful, yes. Free, no.
Even that, however, is only the first layer of the story.
The second layer is the one I think gets missed almost entirely in the public conversation: portability helps only on the portion of the new purchase that can be covered by the old mortgage balance. It does not solve the rest of the transaction.
Let’s walk through a realistic example.
Suppose a homeowner sells a current home for $1.2 million. They have an existing first mortgage of $500,000 at 3.00%. On paper, that leaves about $700,000 of gross equity. But nobody gets to move “gross equity” into the next house. Selling costs come first. Between commissions, escrow, title, transfer charges, and other transaction costs, it would not be hard to see $60,000 to $70,000 disappear before the homeowner ever touches the proceeds.
So now the net equity available is closer to $630,000 to $640,000.
Assume that homeowner then buys a new home for $1.6 million. If the $500,000 mortgage is portable, great. That old loan balance moves over. The homeowner also applies roughly $630,000 to $640,000 in net proceeds from the sale. But the new purchase price is still $1.6 million.
The gap does not vanish.
At that point, the borrower still needs roughly $460,000 to $470,000 in additional financing.
That is where the clean political story starts to get messy.
The homeowner is no longer financing the new purchase at 3.00%. They are financing part of it at 3.00% and part of it at whatever the market demands for the new money. And because that new money may need to come in as a second lien or other subordinate structure, the rate on that gap financing may be meaningfully higher than the rate on a standard first mortgage.
Now we are talking about the actual capital stack, not the campaign version.
Let’s use $465,000 as the new financing amount. If that money potentially carries an 8.10% rate (or higher), which is not unreasonable for higher-risk secondary financing, the borrower’s balance-weighted blended rate would look attractive on paper. You would have $500,000 at 3.00% and $465,000 at 8.10%, producing a rough blended rate of about 5.46%.
That sounds pretty good relative to financing the full amount at today’s first-mortgage rates.
But rate is only part of the story. Payment matters more.
The old portable mortgage would not magically become a fresh 30-year loan. If that mortgage has 24 years remaining, then that is likely the remaining term coming into the new property. If the additional $465,000 is financed separately at 8.10%, the amortization period on that second piece becomes crucial.
If the $500,000 portable first has 24 years remaining at 3.00%, the principal and interest payment is about $2,438 per month. If the $465,000 gap financing is set up at 8.10% over 20 years, the principal and interest payment is about $3,918 per month. Combined, the borrower is at roughly $6,356 per month in principal and interest.
Now compare that with a single new $965,000 mortgage at 6.75% over 30 years. That payment would be roughly $6,259 per month.
Read that again. The borrower “kept the 3% mortgage,” and the monthly payment still comes out slightly higher in this structure than simply taking one new 30-year first mortgage at current rates.
That is not because portability has no value. It absolutely can. It is because the value of the portable piece can be weakened or even overwhelmed by the structure, pricing, and amortization of the gap financing.
And if the second piece is amortized more gently over 30 years instead of 20, the payment improves. In that case, the $465,000 loan at 8.10% would be about $3,444 per month, bringing the combined payment to around $5,882. Now portability is helping more clearly. But even then, the borrower still has to manage a more complex financing structure, potentially with two liens, two different terms, and the complications that come with that.
This is the part of the conversation that deserves more attention.
Portable mortgages are easy to understand at the slogan level. They are much harder to evaluate in an actual transaction.
Who underwrites the gap financing? Does it come in behind the portable first as a true second lien? What does that do to combined loan-to-value limits? How is the borrower requalified? What happens if the new property is a condo with its own approval issues? What happens if values soften and the subordinate lender becomes more conservative? What if the second lien is adjustable, or requires a shorter payoff horizon? What if the borrower later wants to refinance one piece but not the other?
Those are not side questions. Those are the deal.
That is why I think the real story around H.R. 10028 is not that portable mortgages are a bad idea. In concept, they are actually a very interesting idea. They recognize that a mortgage is not just debt; under the right circumstances, it can also be a valuable financial asset. A homeowner sitting on a 3.00% loan in a 7.00% world clearly owns something economically valuable.
The problem is that Washington has a habit of selling the headline benefit of a financing innovation while understating the cost, complexity, and tradeoffs underneath it.
We have seen versions of this before. A 40-year mortgage can be pitched as a lower-payment solution, but extending duration changes the economics of the loan and the way investors price the risk. The payment may go down relative to a shorter term, but the borrower pays for longer, builds equity more slowly, and can end up carrying more interest over time. The wrapper changes. The economic realities do not disappear.
Portable mortgages raise a similar issue. If you give borrowers a valuable option, someone has to absorb that cost. If you preserve only part of a low-rate financing structure, someone still has to fund the rest. And when that additional capital sits in a riskier position, it usually commands a higher rate.
That is the story.
The MOVE Act, authored by Representative Tom Kean Jr., is politically sharp because it taps into a genuine frustration in the housing market. Homeowners feel trapped by the success of their old financing. They know their current mortgage is too good to casually surrender. Any policy proposal that seems to honor that reality is going to attract attention.
But attention and execution are two different things.
If portable mortgages eventually become a viable conventional product, they may help mobility for some borrowers. They may improve transaction flow. They may allow some homeowners to preserve a meaningful portion of their financing advantage when they move. That would be a real benefit.
What they will not do is magically turn a move-up purchase into a 3.00% financing event. They will not erase selling costs. They will not eliminate the need for new capital. And they will not prevent the market from pricing the risk associated with that structure.
The cleanest way to say it is this: portability may preserve the cheap money you already have, but it does not make the next house cheap.
For borrowers, advisors, and anyone trying to think clearly about housing policy, that is the conversation worth having. Not whether portable mortgages sound good. They do. The better question is whether the full financing stack still makes sense once the math, structure, and incentives are laid out honestly.
That is where the real answer lives.

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 45 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

Why Big Banks Are Pouring Billions Into Reviving the Housing Market – Shared Article By Tristan Navera

Thank you for tuning in – sharing this article – I read here.

JPMorgan Chase, the nation’s largest bank, is a name typically attached to big numbers. But a new plan to invest $750 billion into housing market initiatives in the next decade stands out.

The bank announced this summer it would deploy $750 billion into the housing market through 2035. Its “American Dream Initiative” aims to build or preserve 1 million affordable housing units and help 500,000 customers purchase homes, 200,000 of them for the first time.

It’s not alone. Wells Fargo, Citibank, and Bank of America—which, with JPMorgan, comprise the “big four” of American finance—have each announced major housing initiatives. And, like the $5 trillion JPMorgan Chase, they’re directing tens of billions toward the problem.

The nationwide housing supply shortage, as well as rampant pessimism among young people, make the issue too big to ignore, says Sam Sheets, a strategy executive for Community & Affordable Lending at JPMorgan Chase.

“At the end of the day, it’s a function of supply and demand,” Sheets says. “Supply is the big issue—and supply of homes at the right price point.”

Housing has long been a major focus for banks. Bank of America, for instance, has provided $15 billion in loans and grants since 2019 to support down payments, closing costs, and affordable mortgage options for homebuyers. It partners with 300 housing counseling groups in the process.

But banks are now also expanding their support for efforts like zoning reform, building code changes, and new homebuilding in an effort to restore affordability to the housing market—and potentially expand the pool of mortgage borrowers, which has been shrinking lately.

“It’s driven by slower new construction but also just a lock-in effect, which has forced families to stay put when they would have moved and upsized,” Sheets says.

The business case for bank intervention

Reading between the lines, banks may be concerned about the decline in mortgage business in recent years.

The number of annual new mortgage accounts at large banks has hovered below 500,000 for the past three years, well below the million-plus levels typically seen in a single year before the pandemic, according to tracking from the Philadelphia Fed.

The sharp drop-off in big bank mortgages is due in part to increased competition from specialty lenders, but the main culprit may be the overall decline in homebuying activity since 2022.

Bernard Nossuli, COO at lending data company iEmergent, notes the mortgage business has been racked by the uncertain market, including high interest rates and limited signals from the Federal Reserve about when that might change.

Roughly 581,000 home purchase loans were originated from January through March 2026, down 19% from the previous quarter and a 12-year low. With many younger buyers priced out, and older buyers “locked in” to homes with low rates, supply-side solutions seem to be the easiest lever to pull right now.

But while those policies might seem straightforward, “the reality is a lot more complicated than that,” Nossuli says.

Large Bank Mortgage Originations Chart

Beyond mortgages

Obviously, banks have always played a major role in the housing market via the mortgages they provide. But as the nation confronts a major affordability crisis with complex causes and difficult solutions, banking leaders have sought a more proactive role.

The $49 trillion housing market has been the bedrock of Americans’ financial prosperity for generations. But the shortage of millions of homes, as well as millions of affordable rentals, has meant more Americans’ financial lives are being stifled because housing eats into their ability to save and invest.

At a Washington, DC, conference hosted by the Bipartisan Policy Center in June, Edward Skyler, head of Enterprise Services for Citi, said the private sector has roles to play around the edges.

“We need American ingenuity and entrepreneurship to help us build cheaper,” Skyler said. “We need to apply some of this great intellectual capacity and allocate some of that brain power to housing, because it is ripe for innovation.”

This year, Citi launched its “Blueprint for Housing Opportunity Initiative,” a $60 billion plan to support the preservation and construction of 250,000 homes. Last year, it financed $7 billion to support 30,000 units, and the new initiatives would double the pace, Skyler said.

Citi also committed $50 million to support housing nonprofits, including “seed funding” to support pre-development work like architecture and zoning studies on new housing projects. That support helps those companies prepare developments to turn dirt. Their role in their cities makes their housing pitches more likely to be successful, Skyler said.

“This is an issue that is really harming Americans across the country, and not just in the big cities,” he noted.

Banks push for policy change

In the case of JPMorgan, the bank has leaned into thought leadership. It has backed housing market analysis through a policy center that advocated for reducing regulatory barriers and encouraging manufactured housing innovation.

“We’re really trying to look at what levers, and particularly state and local levers, that can reduce the cost drivers of what it takes to build housing,” Olivia Barrow Strauss, vice president of Housing Policy at JPMorgan, recently told Realtor.com®.

And for Citi, policy advocacy is part of its plan, too. Its blueprint encourages lawmakers to consider changes to the Low Income Housing Tax Credit, a tool that helps finance affordable housing development. Allowing it to be transferrable would encourage more banks and other investors to put money behind the credit that developers can use, Skyler said.

“We’re seeing a lot of money left on the table,” he noted. “Our idea is simply to … try and create a market for them.”

The banks are also backing the private sector. Wells Fargo has awarded $53 million to back innovations in home construction and financing through its “Housing Affordability Breakthrough Challenge.” Its foundation has contributed $830 million toward housing efforts since 2019.

The initiatives aren’t just a philanthropic effort, either. Dennis Shea, co-leader of BPC’s Terwilliger Center for Housing Policy, says the housing shortage has major macroeconomic effects that limit labor mobility, productivity, and economics. That in turn limits bank customers and stifles growth of the broader private sector.

At Chase, Sheets says the bank is aggressively trying to grow its mortgage business. It originated $52.8 billion in mortgage volume in 2025, up from $40.8 billion in 2024, according to its most recent financial reporting.

The bank’s housing initiatives offer it “a more comprehensive view” for how it can positively influence housing supply, he says.

I read this here.

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 45 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

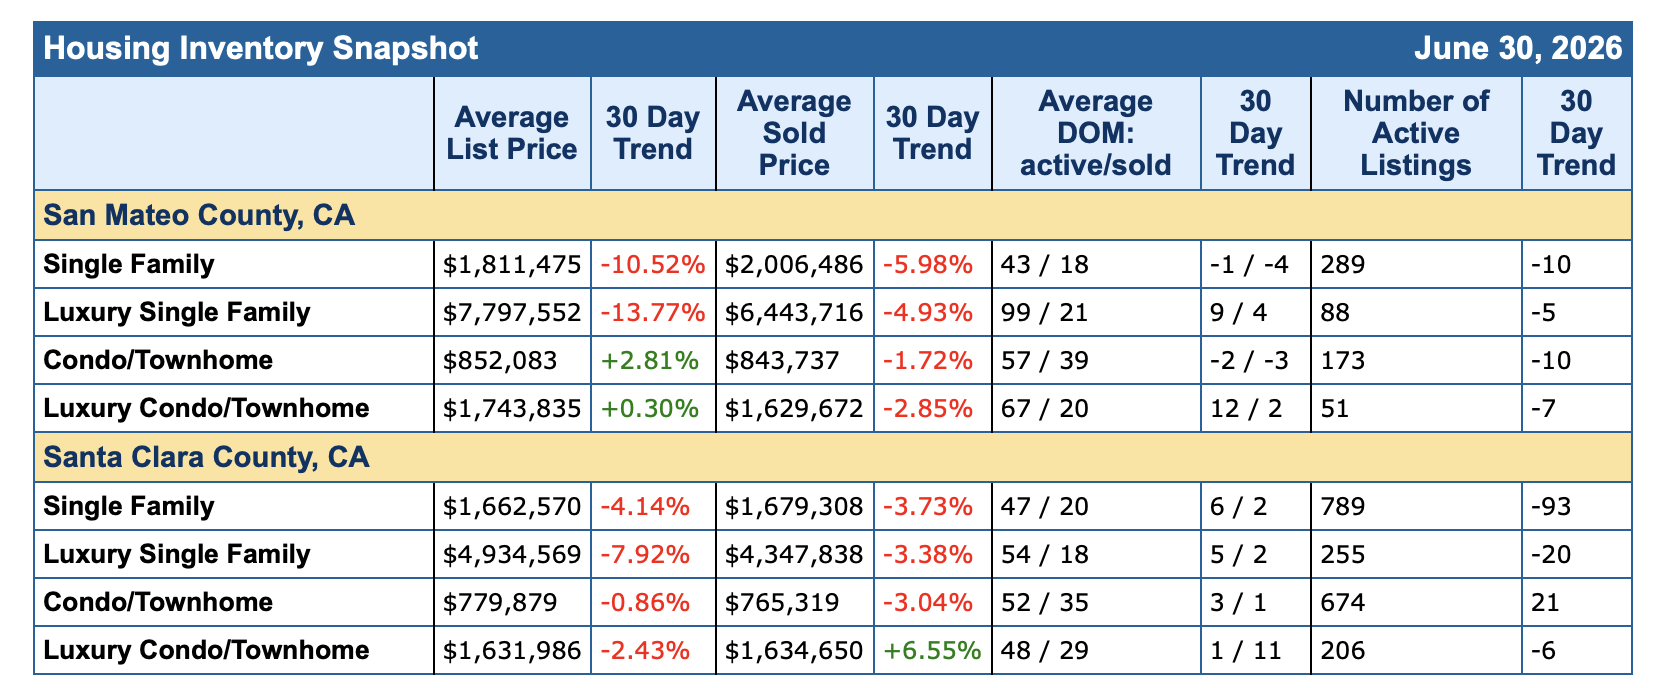
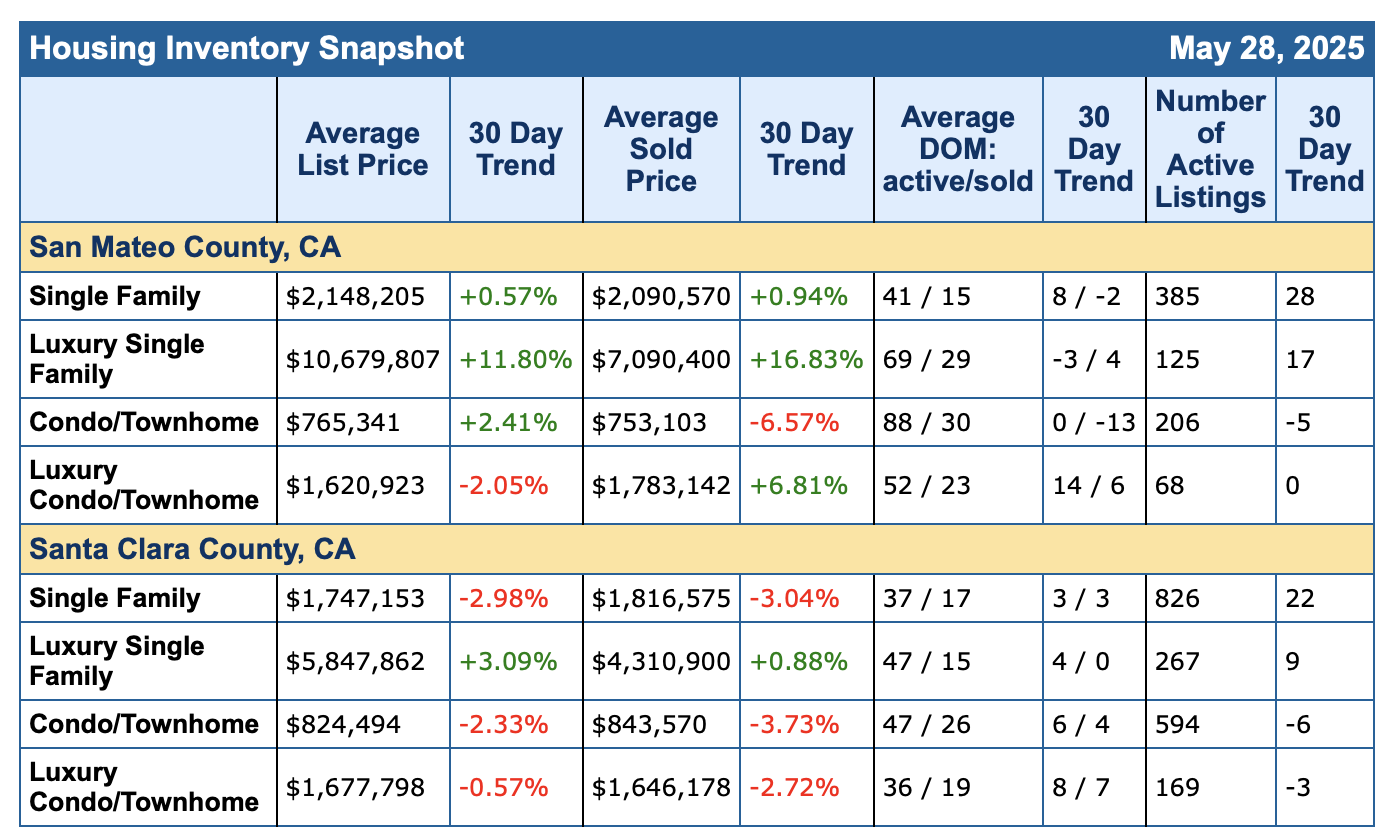
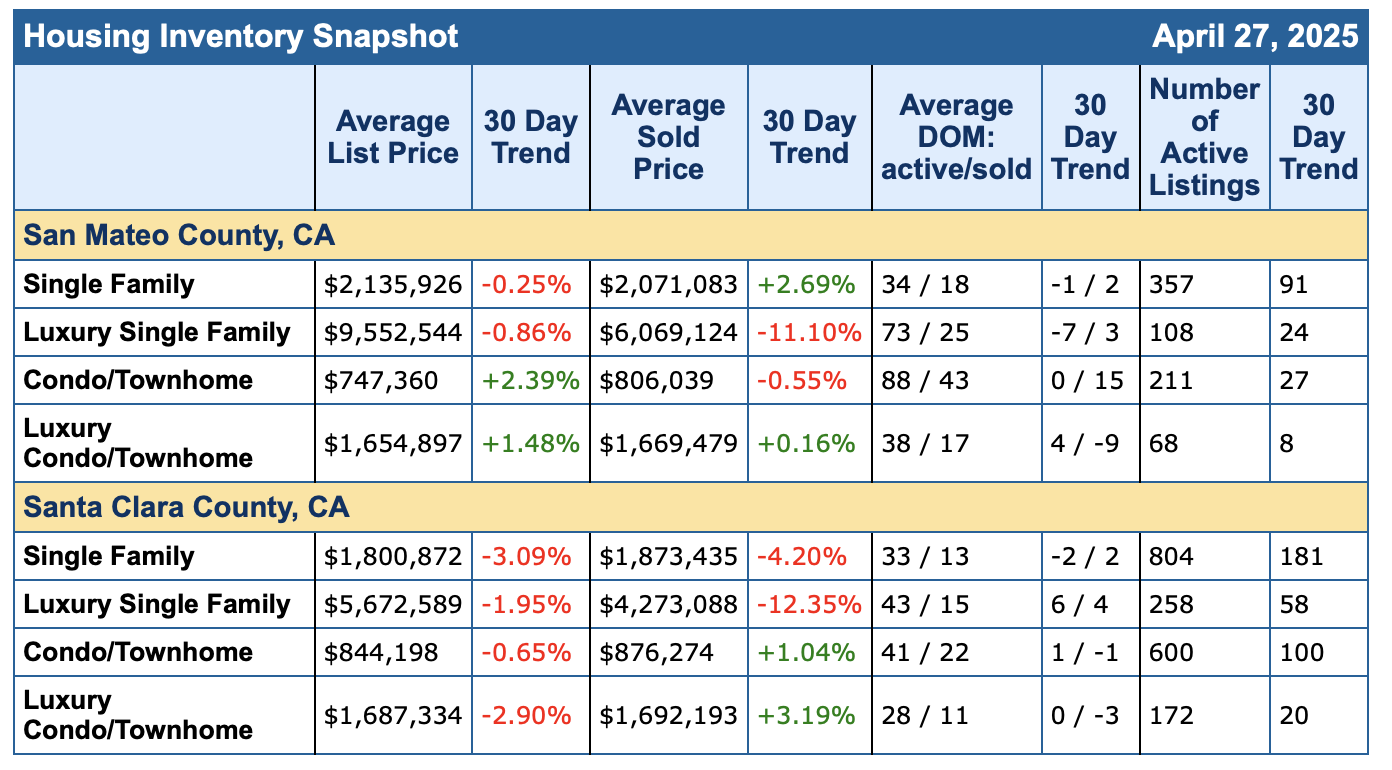
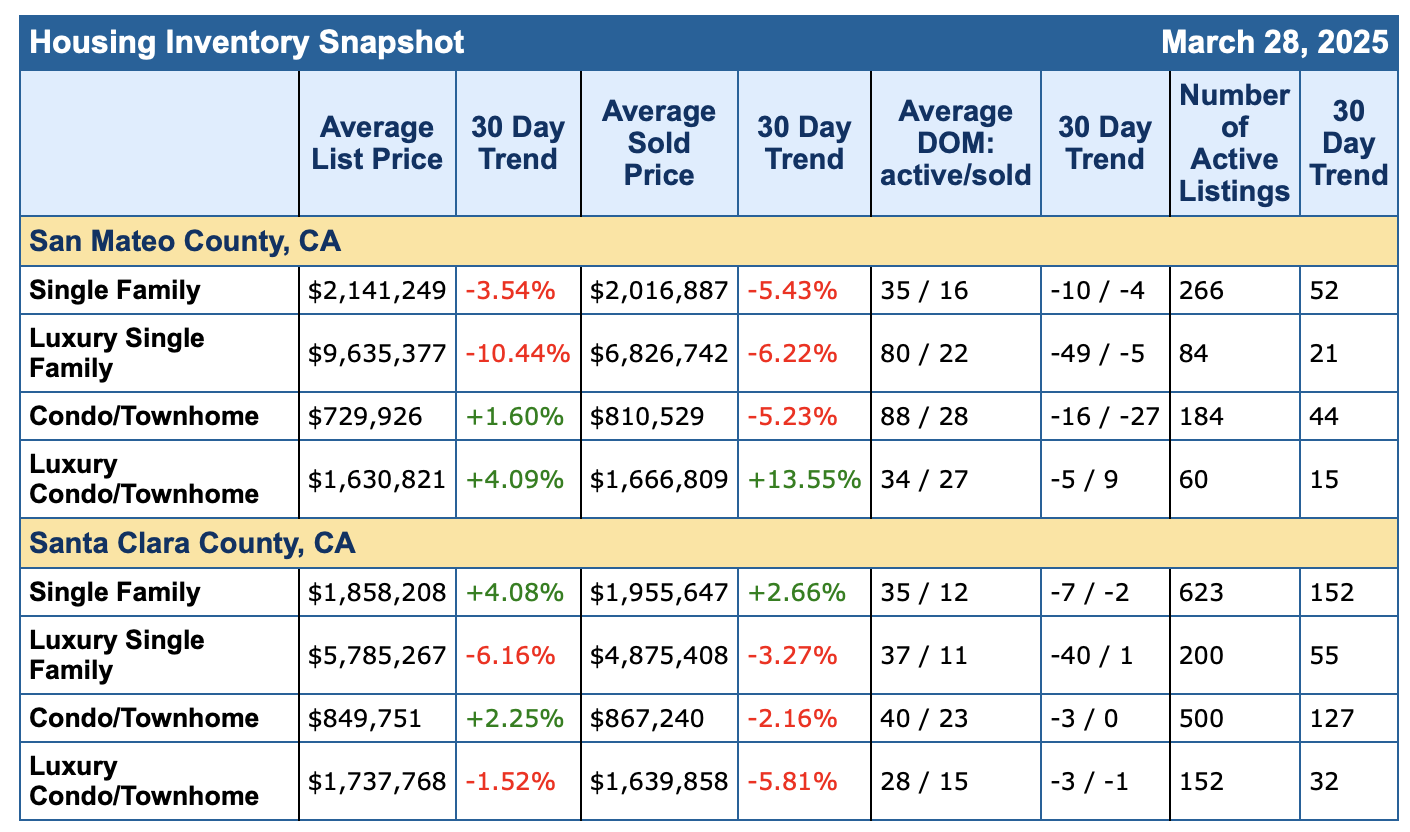
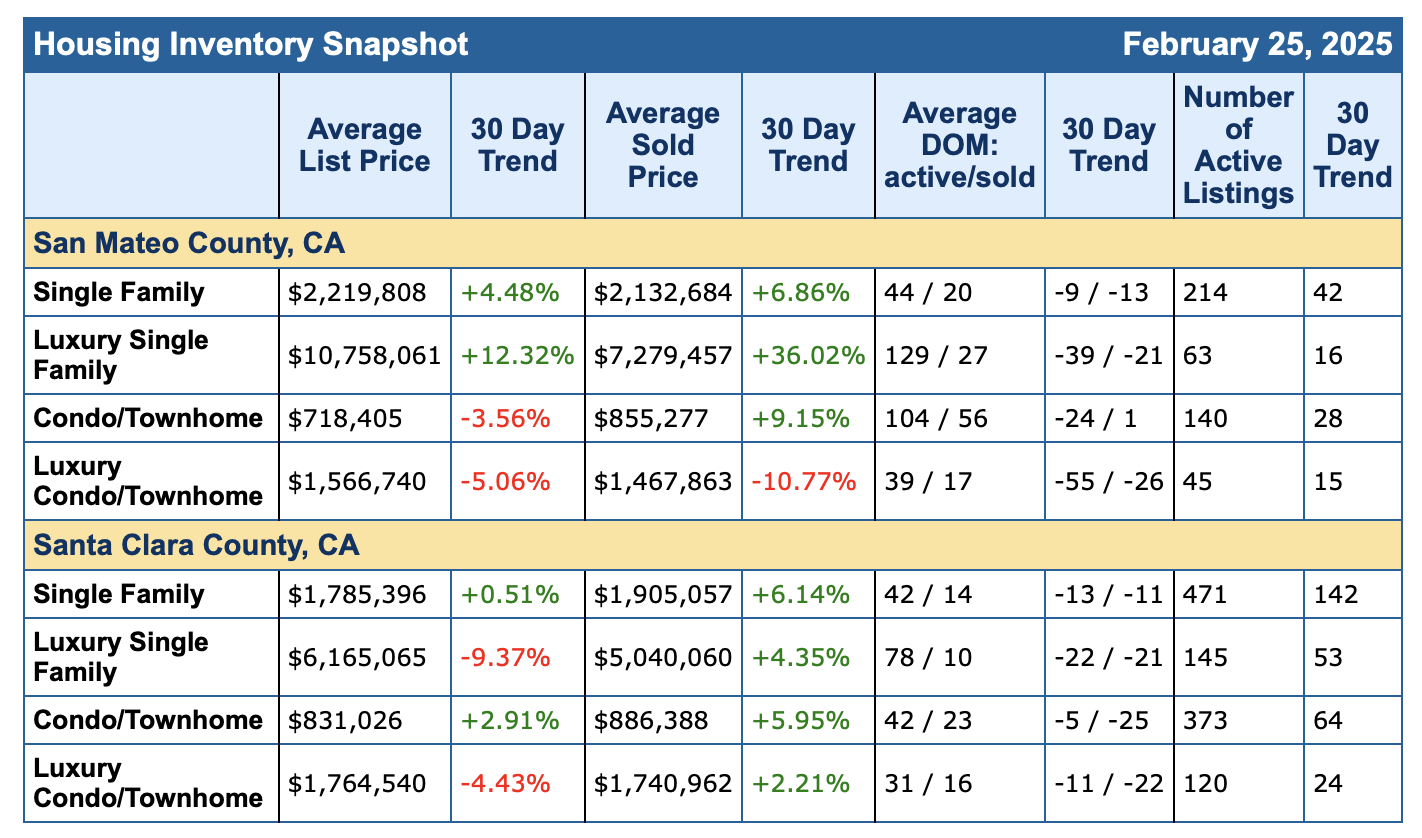
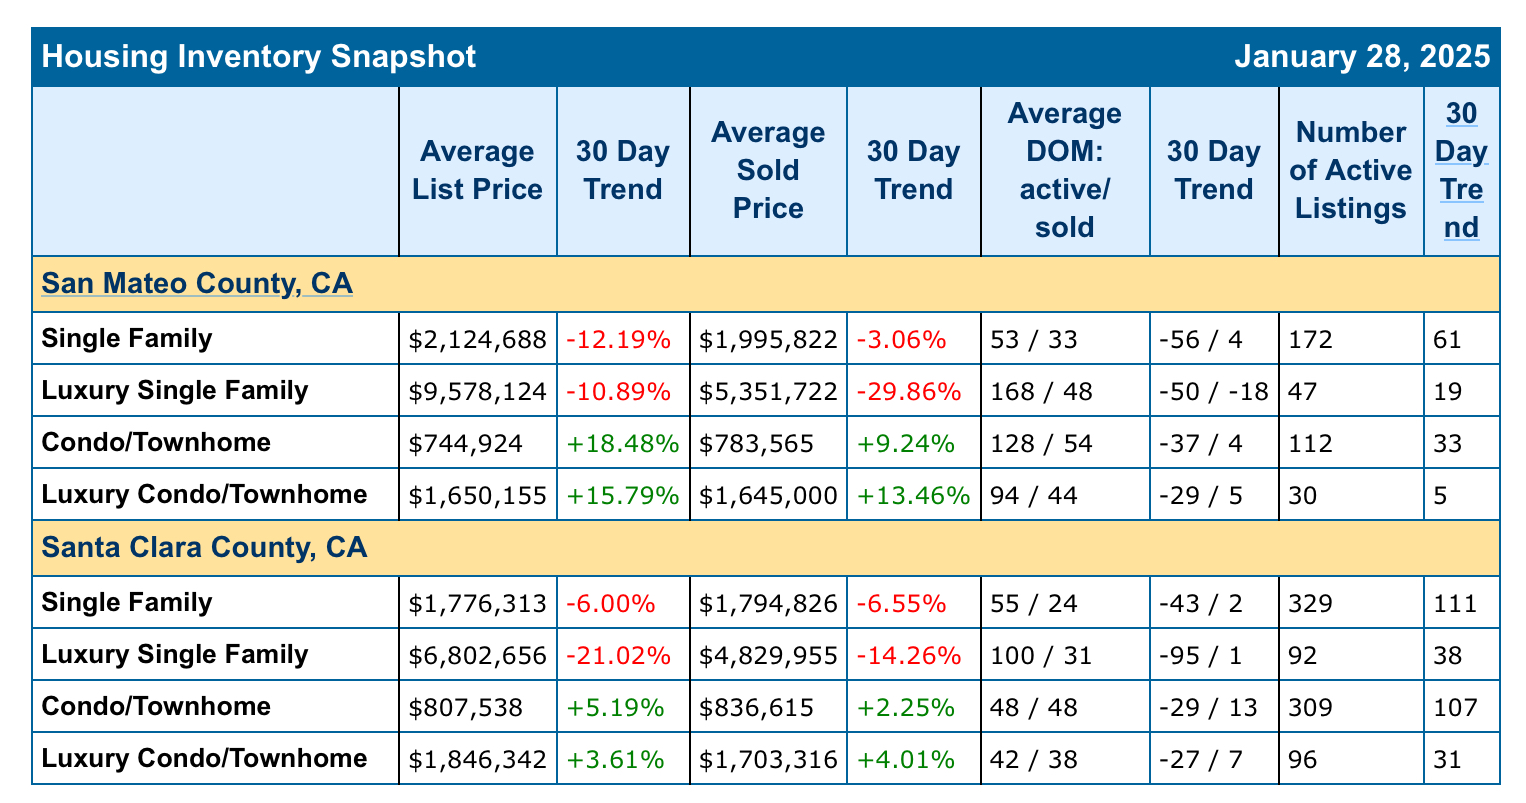
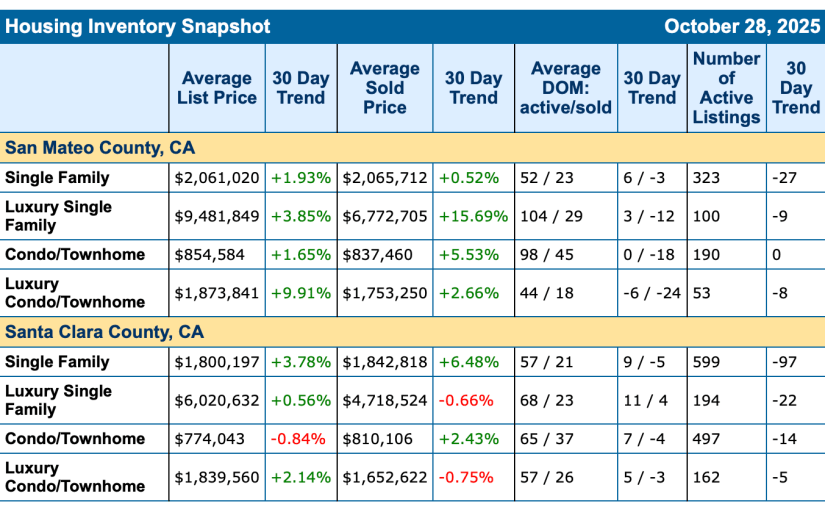
The Stats are In… Market Snapshot for July 2026

Hello Caton Team Readers,

Thank you for tuning in. The stats are in for July 2026.

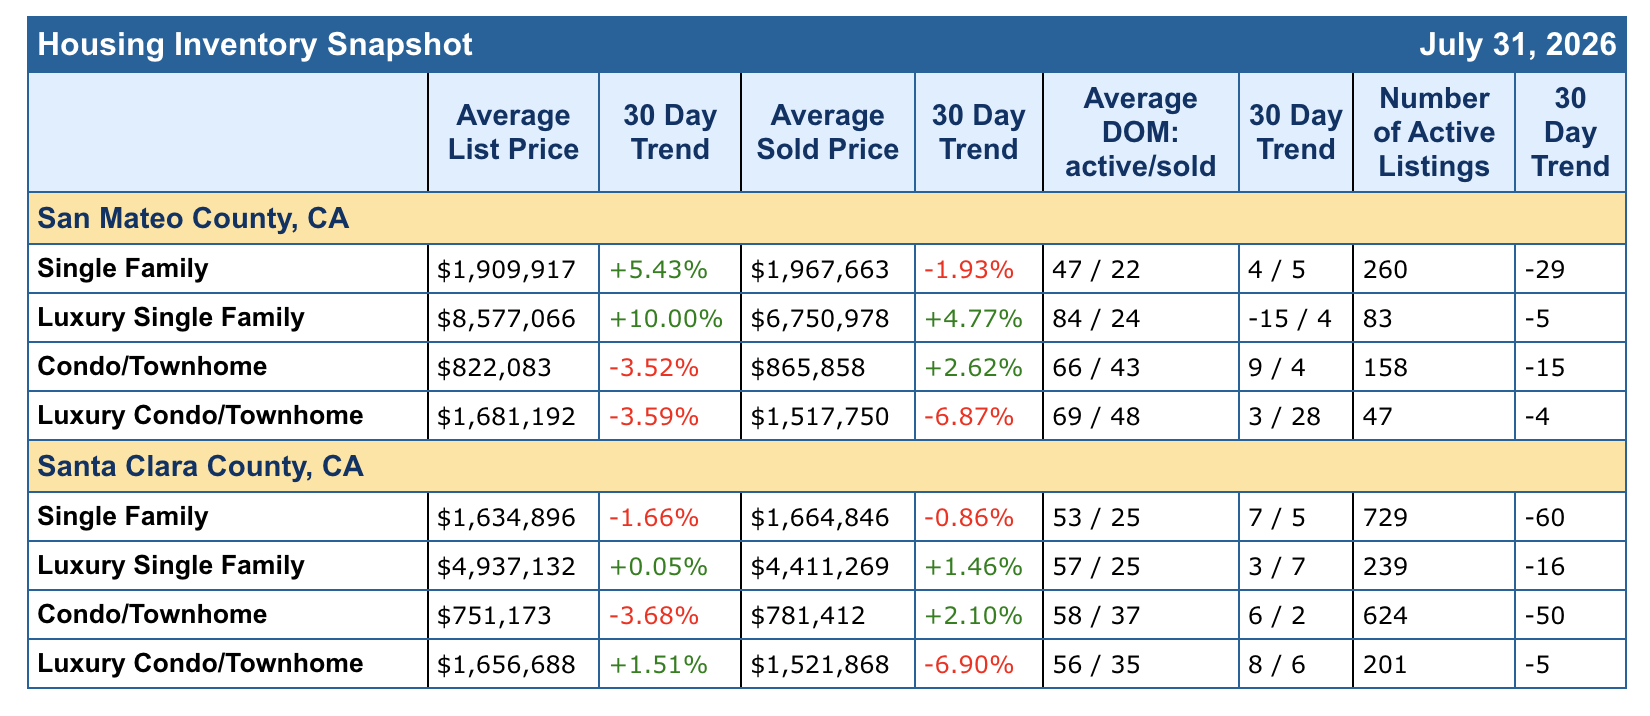
I am happy to see some growth in home sales for San Mateo County. I am not surprised about the dip in the townhome / condo market as they are faced repairs due CA legislation SB 326 (read more here). Small dip in Santa Clara County home sales. The luxury condo market in the South Bay are often newer developments so that may account for the growth there – they may not be faced with repairs due to older buildings.

As Summer comes to and end and Fall begins. I am curious where are market will go. I’ve seen an increase in buyers getting approved for loans, but also many opting to rent and save in order to buy something more to their liking. That can be a tricky move as waiting one year will impact purchase power if homes continue to appreciate and I think they will – it is the pace that I see slowing down. Homes in California have been appreciating since 1849 (I kid but you get it) – it just may not be as steep. Add some tech lay offs and we stand by to see the impact. However…

If you want to live in the Bay Area, if you have a steady job here and want to grow roots here – NOW – is a great time to buy. There are properties sitting, there are price reductions – this is an opportunity for a buyer to get a house, even under list with contingencies! As long as you see yourself here for about 7-10 years – that is a realistic time it takes to see appreciation. The longer you hold onto a home, the better. So when the market is soft and you have long terms goals here – let’s jump in.

The Caton Team provides free buying and selling consultations – to determine the current value of your home if you are selling or if you’re in the market to buy – where you get the most bang for your buck.

Remember, each neighborhood is different, if you are considering a purchase – let us guide you through this and help you find your way home.

If you’re in the market to sell – each area and price point has it’s own pros and cons – let us help you figure out your next steps.

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home. We have before and we will again. We move with the market.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined, local Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at sabrina_caton@yahoo.com.

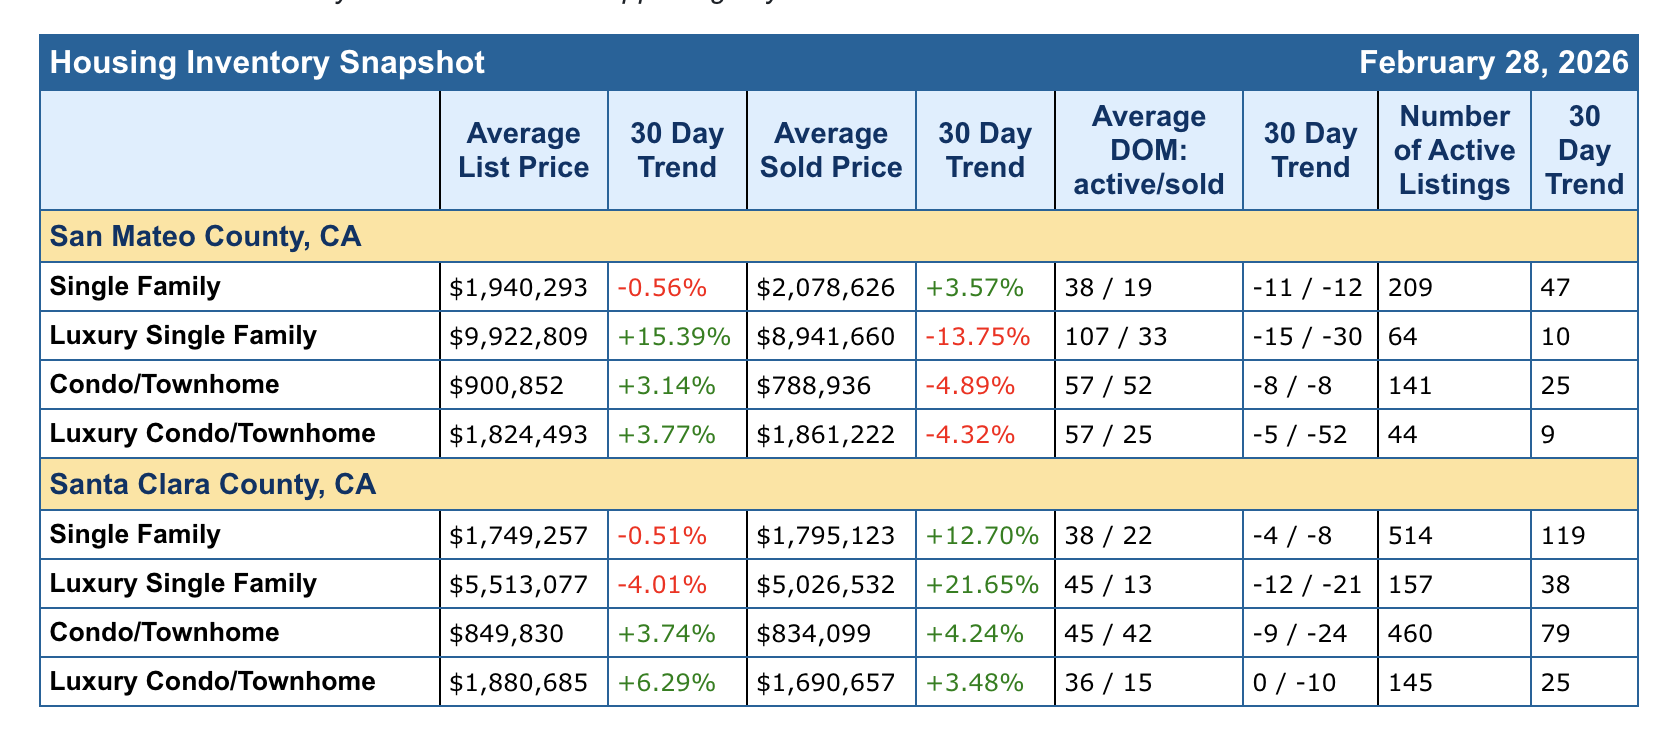
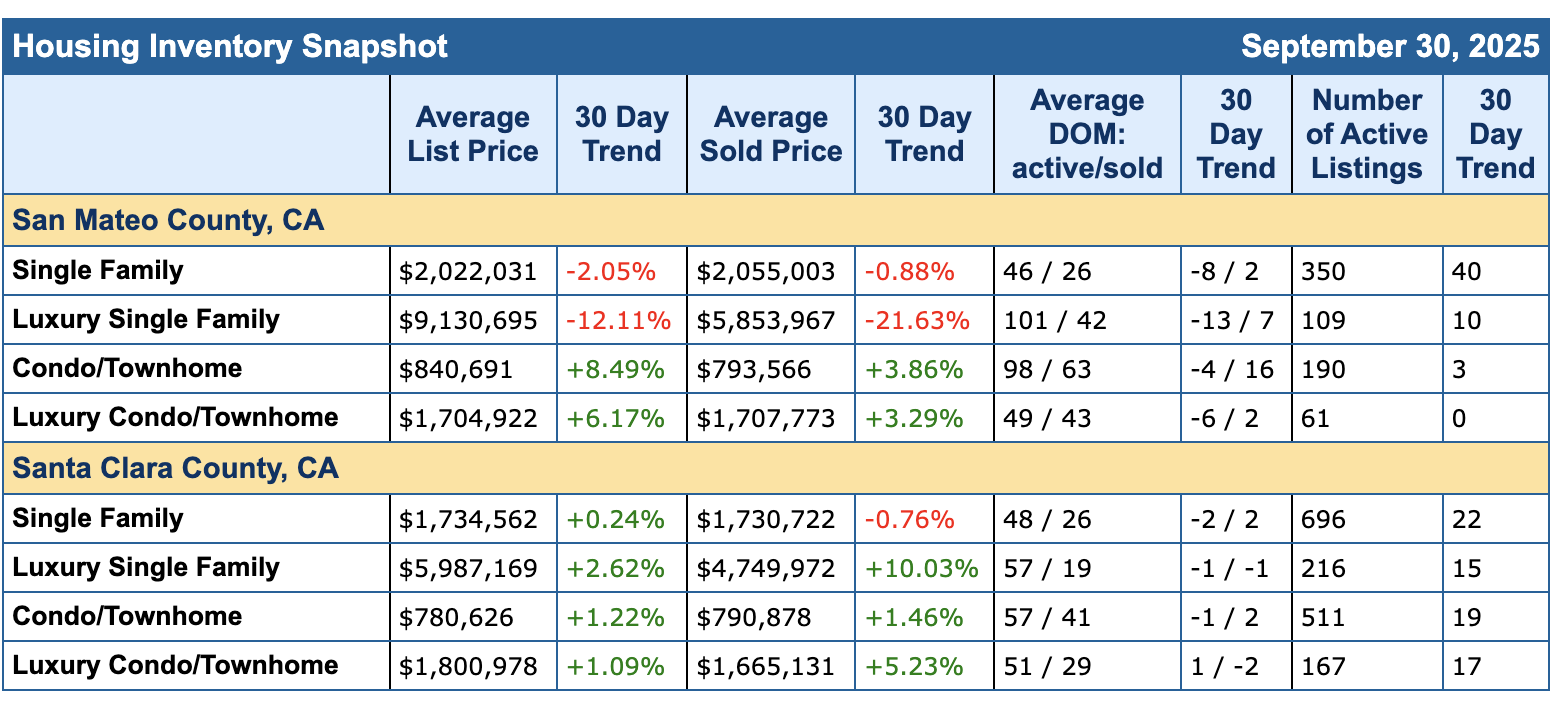
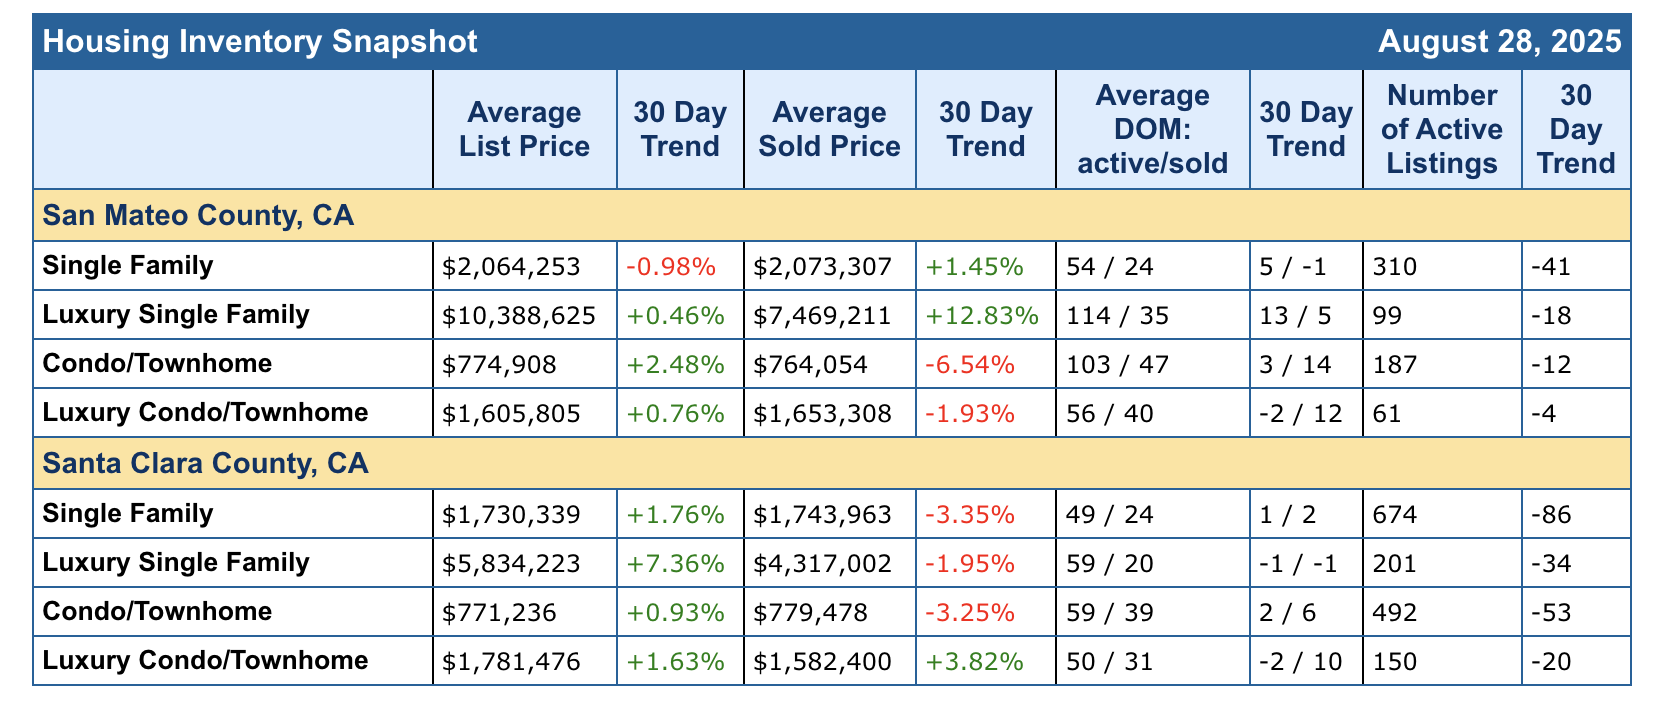
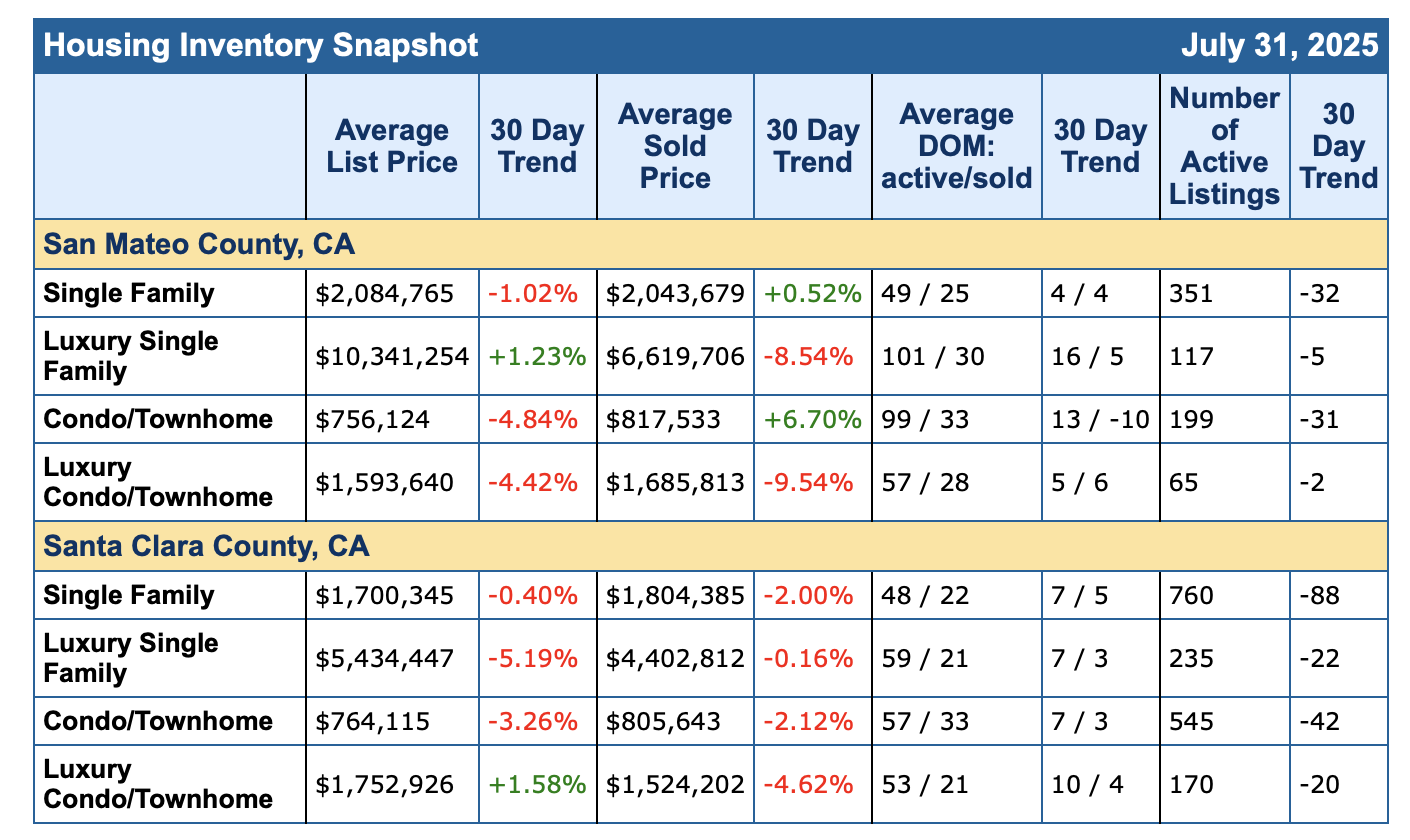
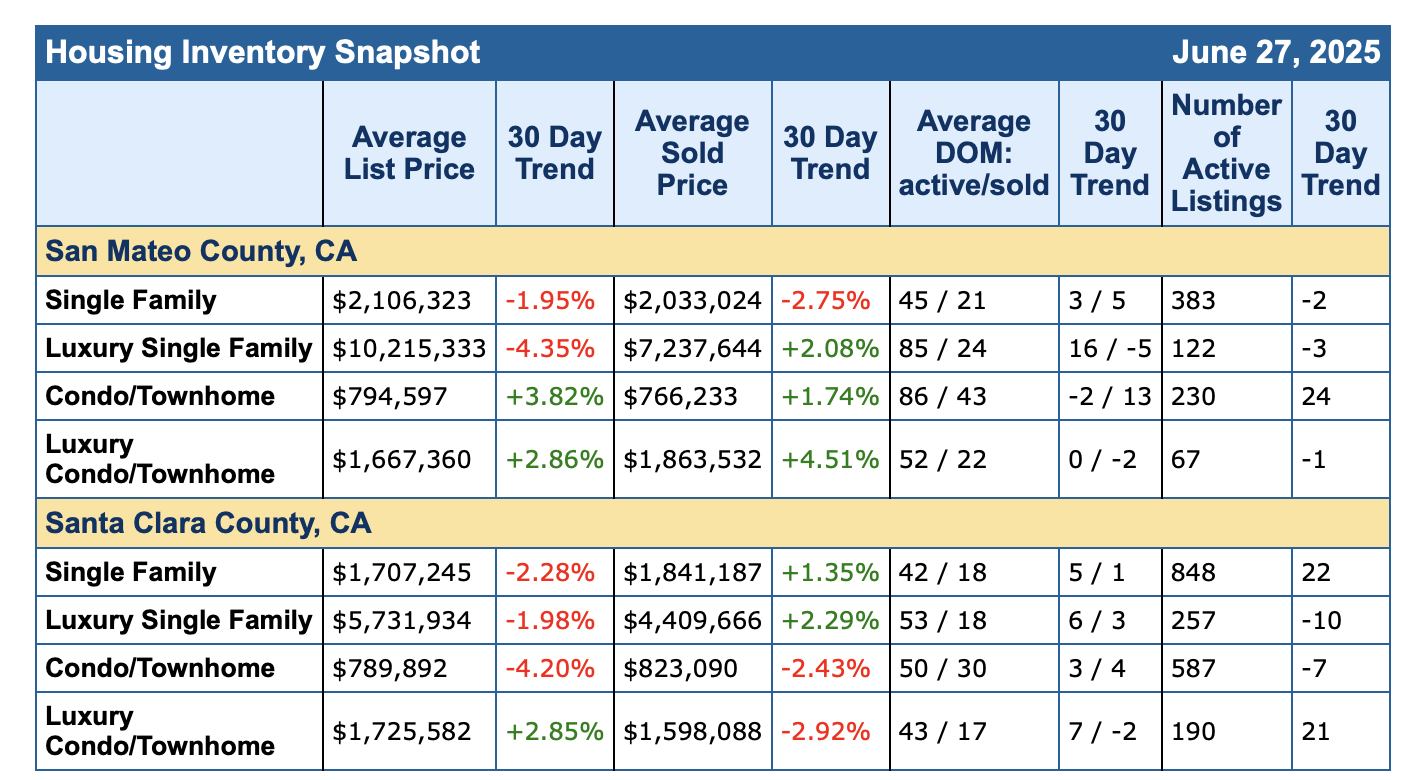
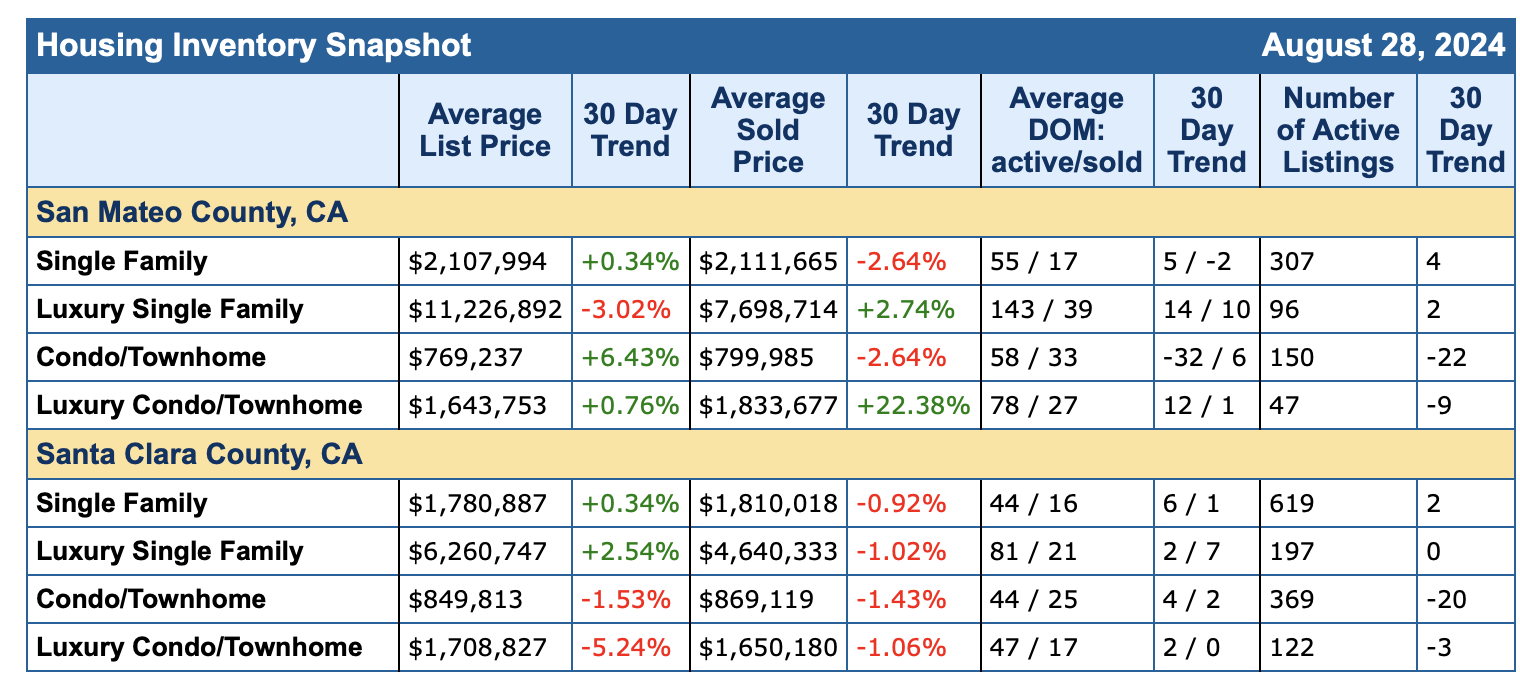
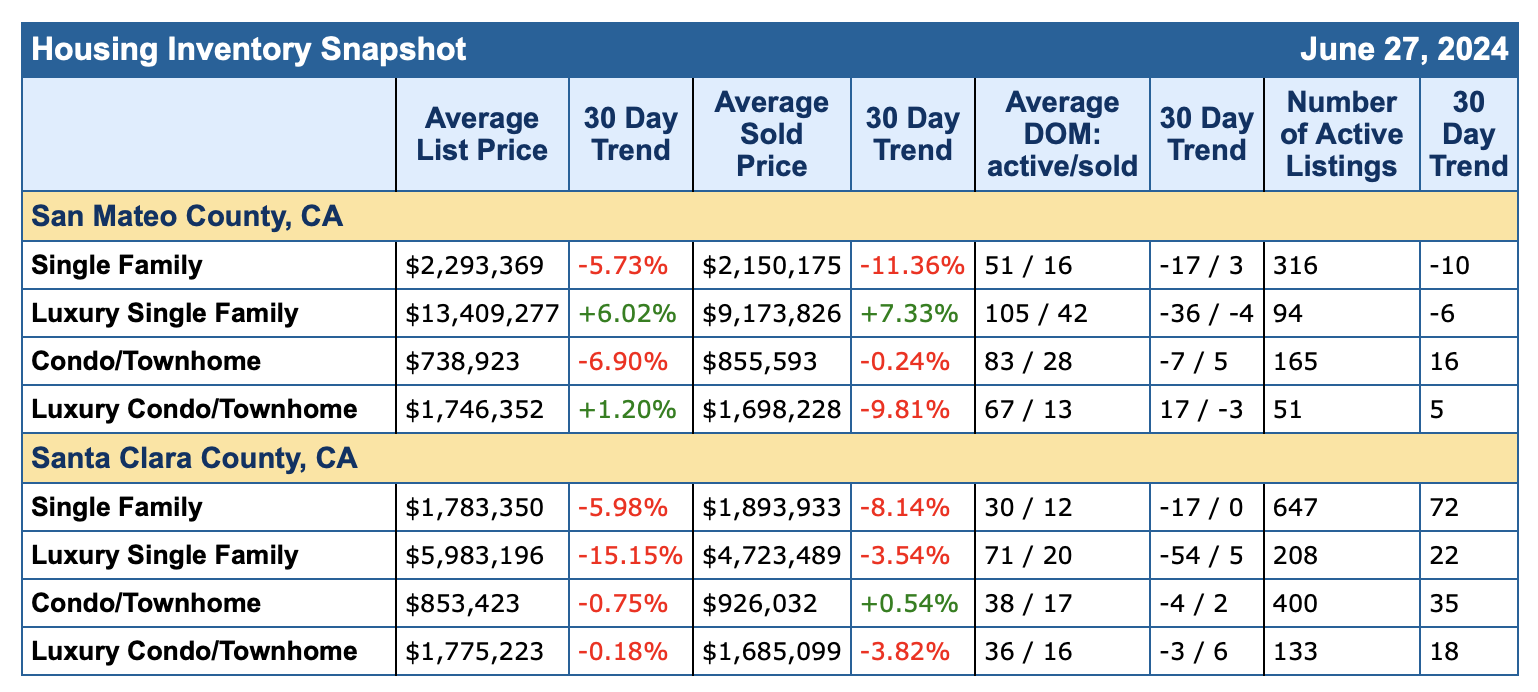
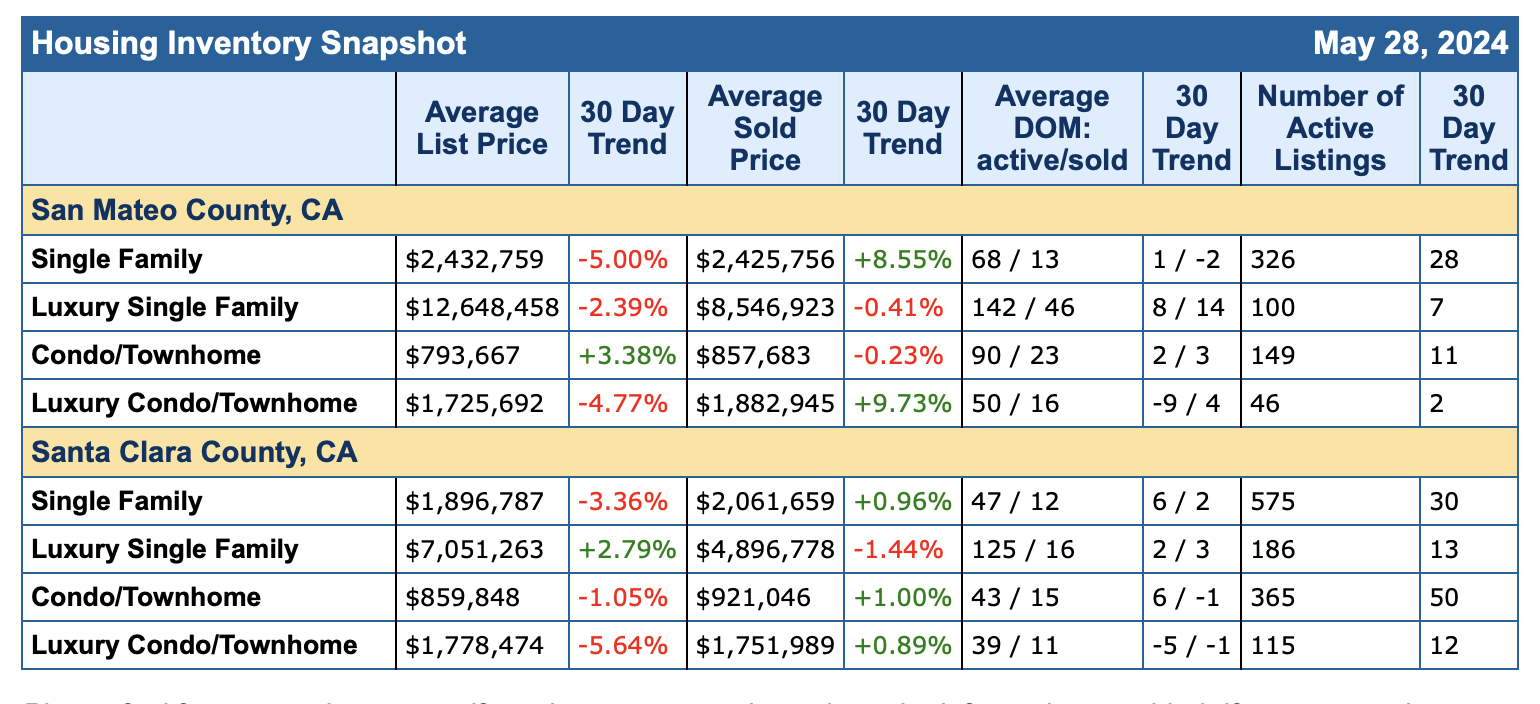
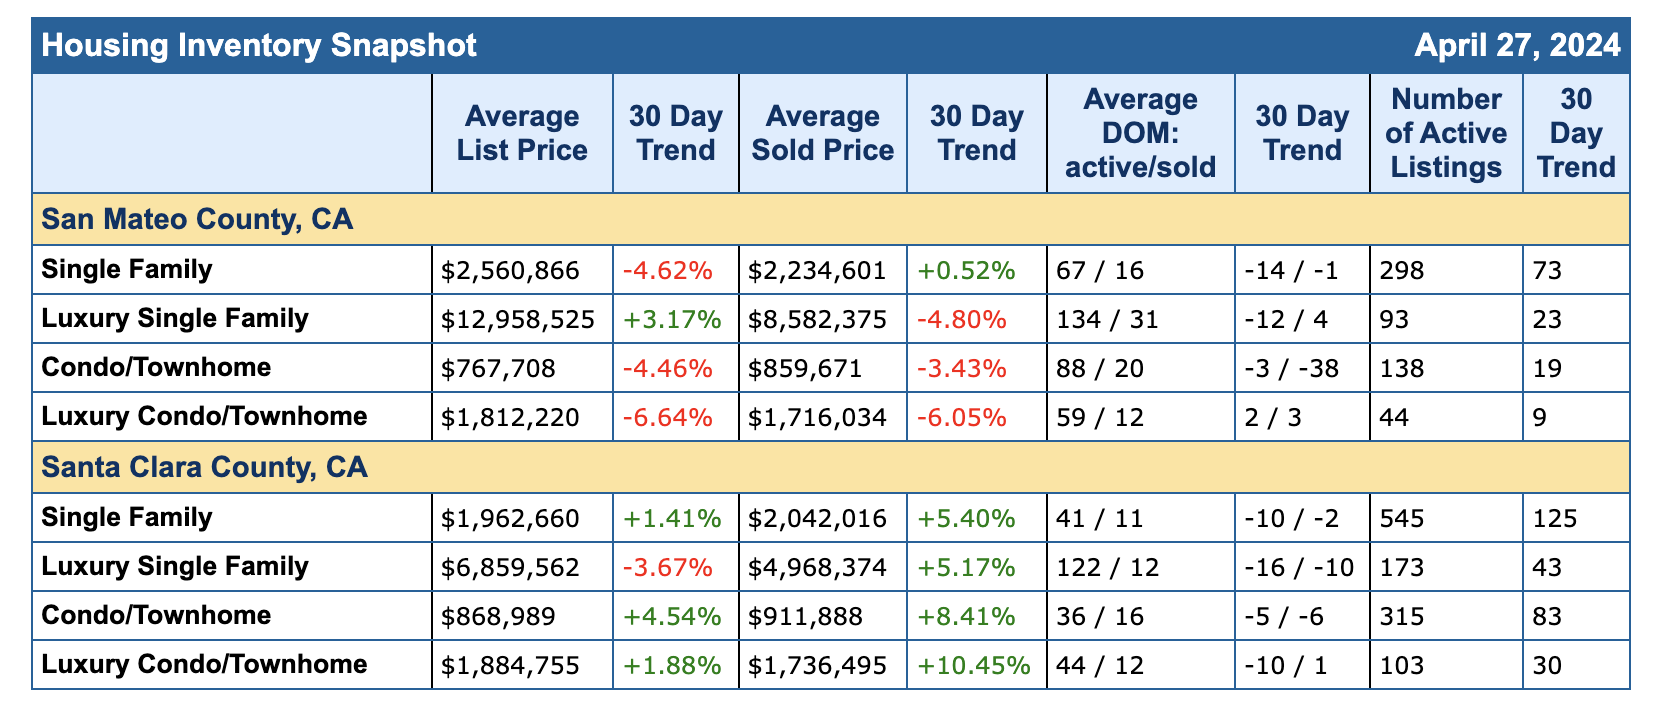
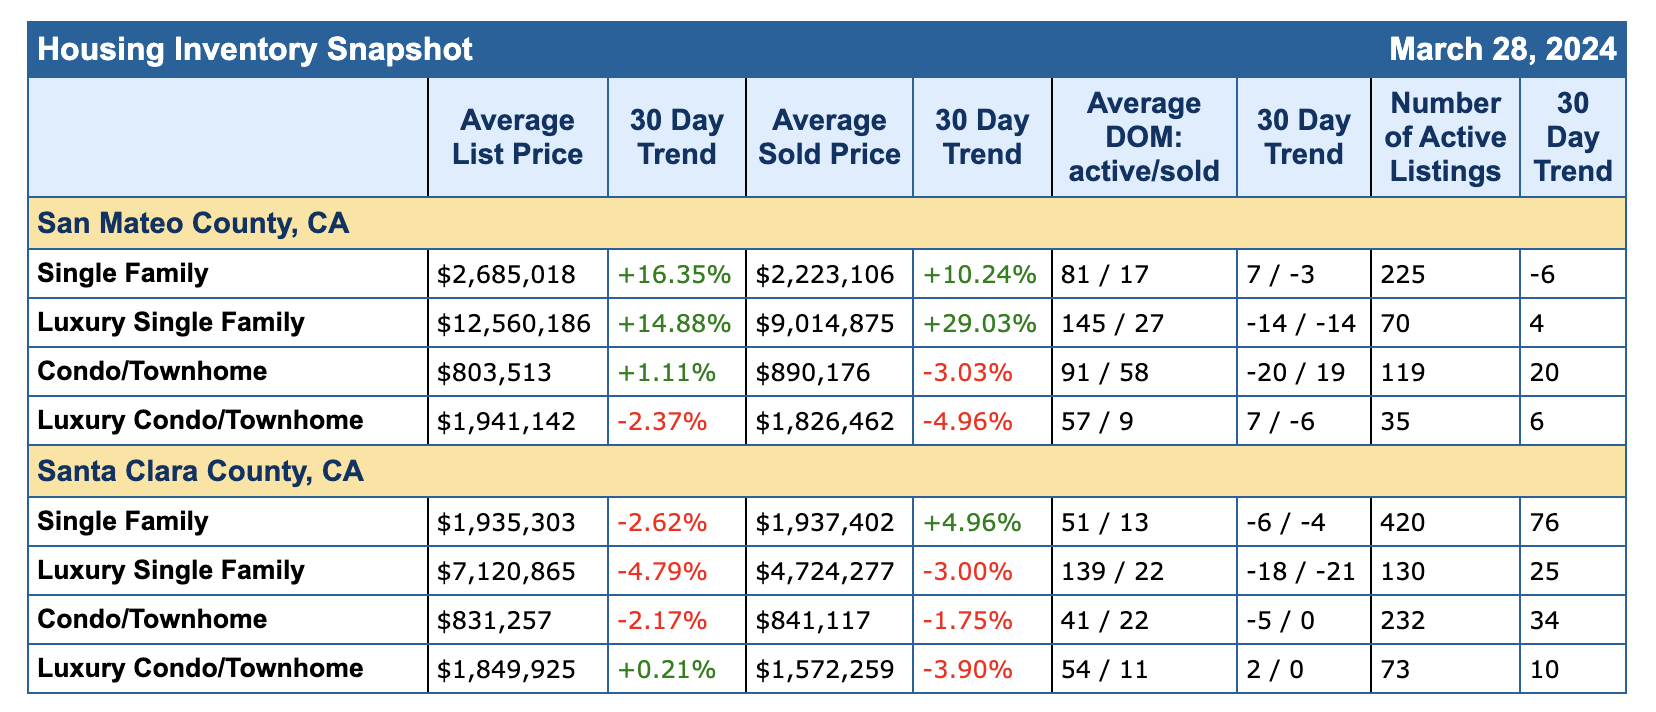
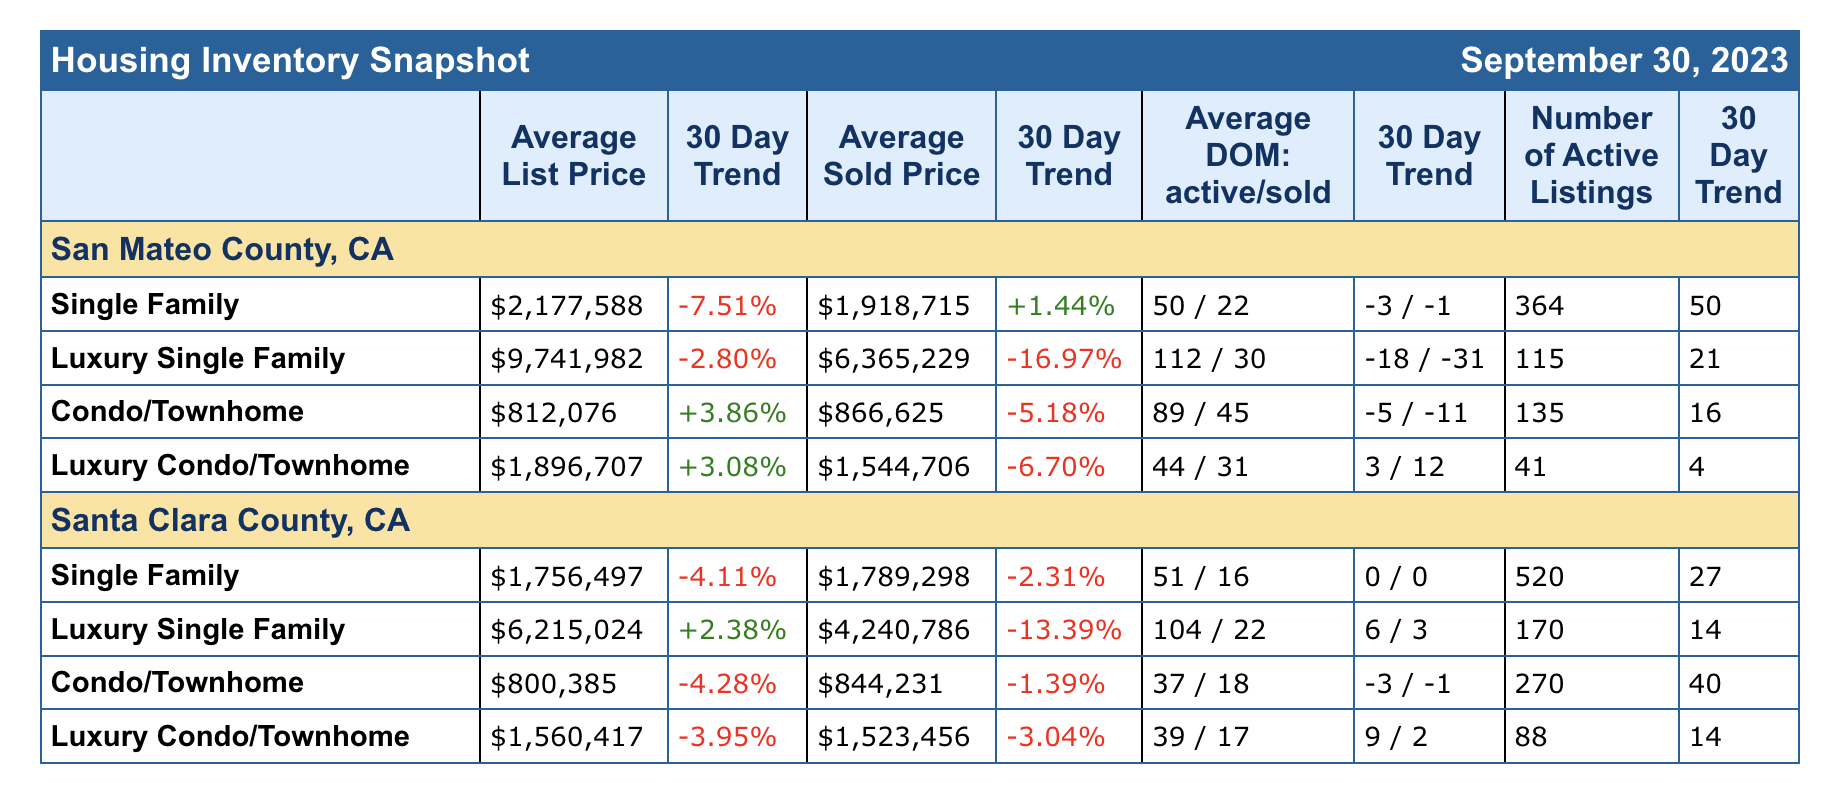
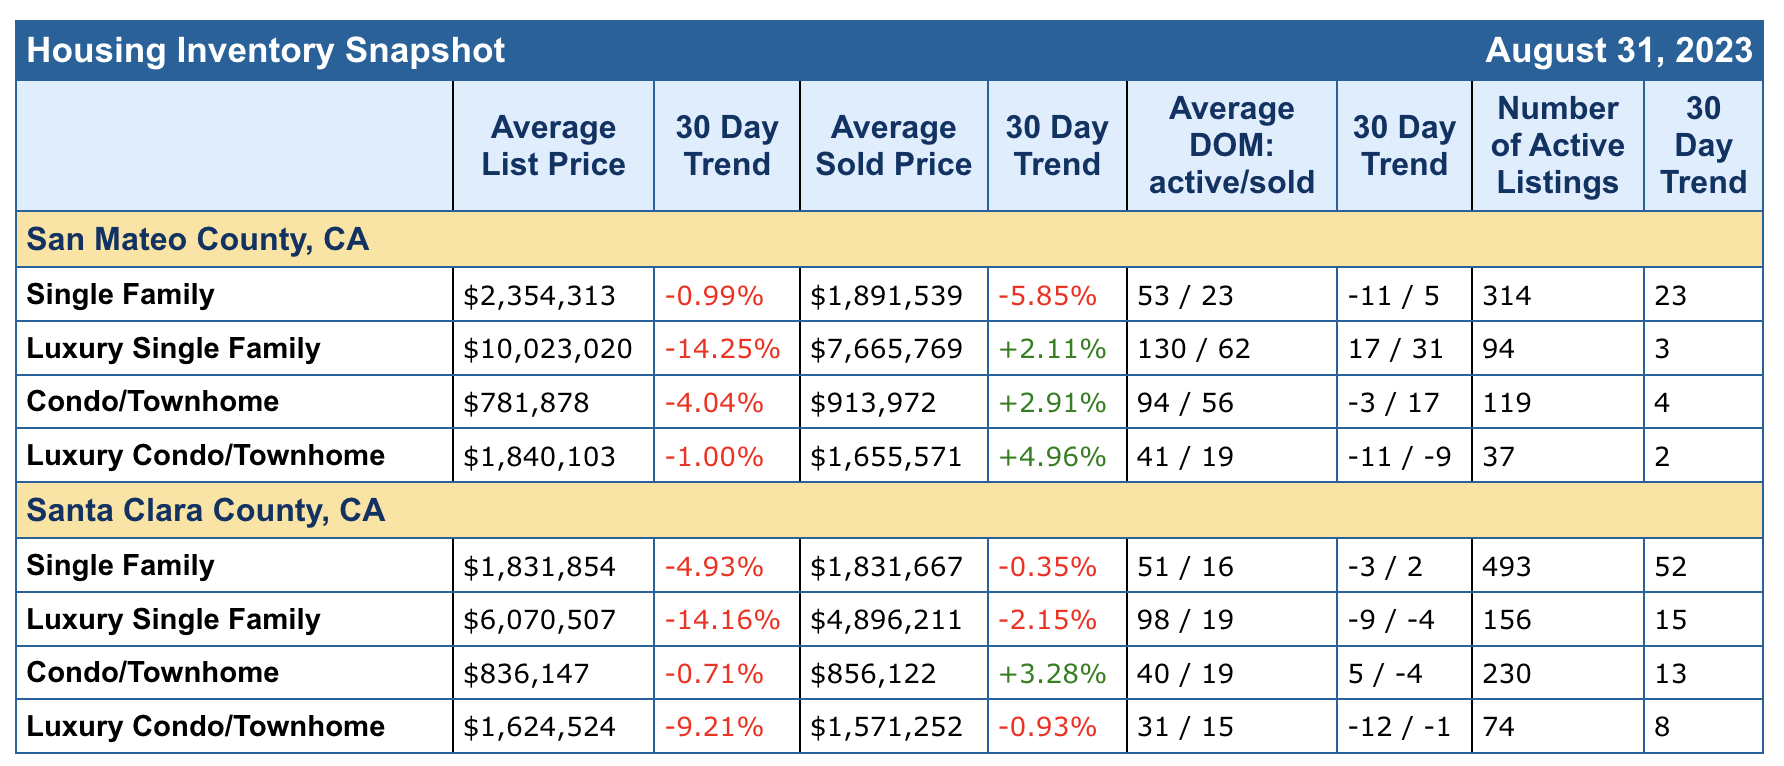
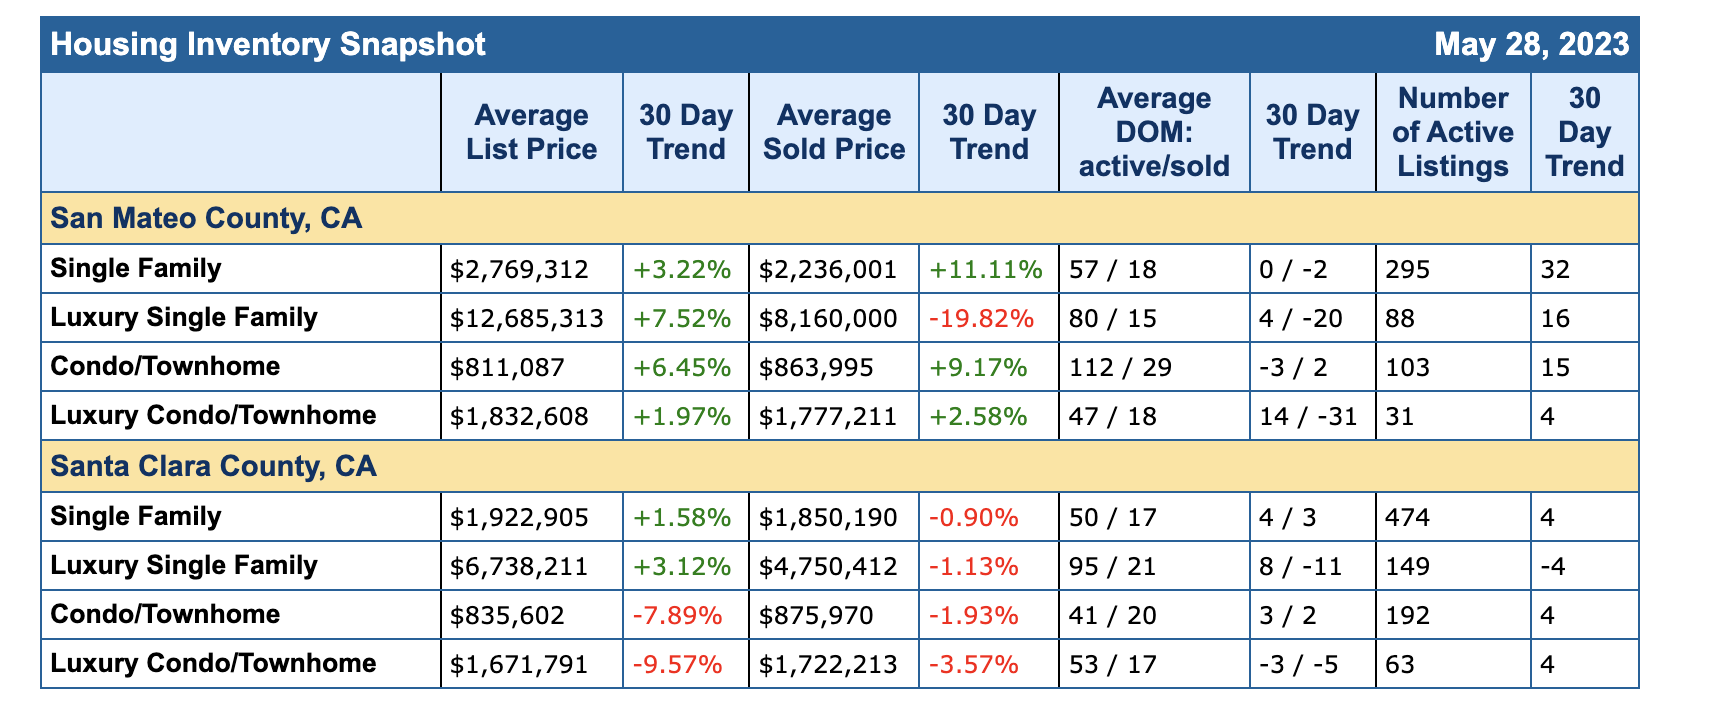
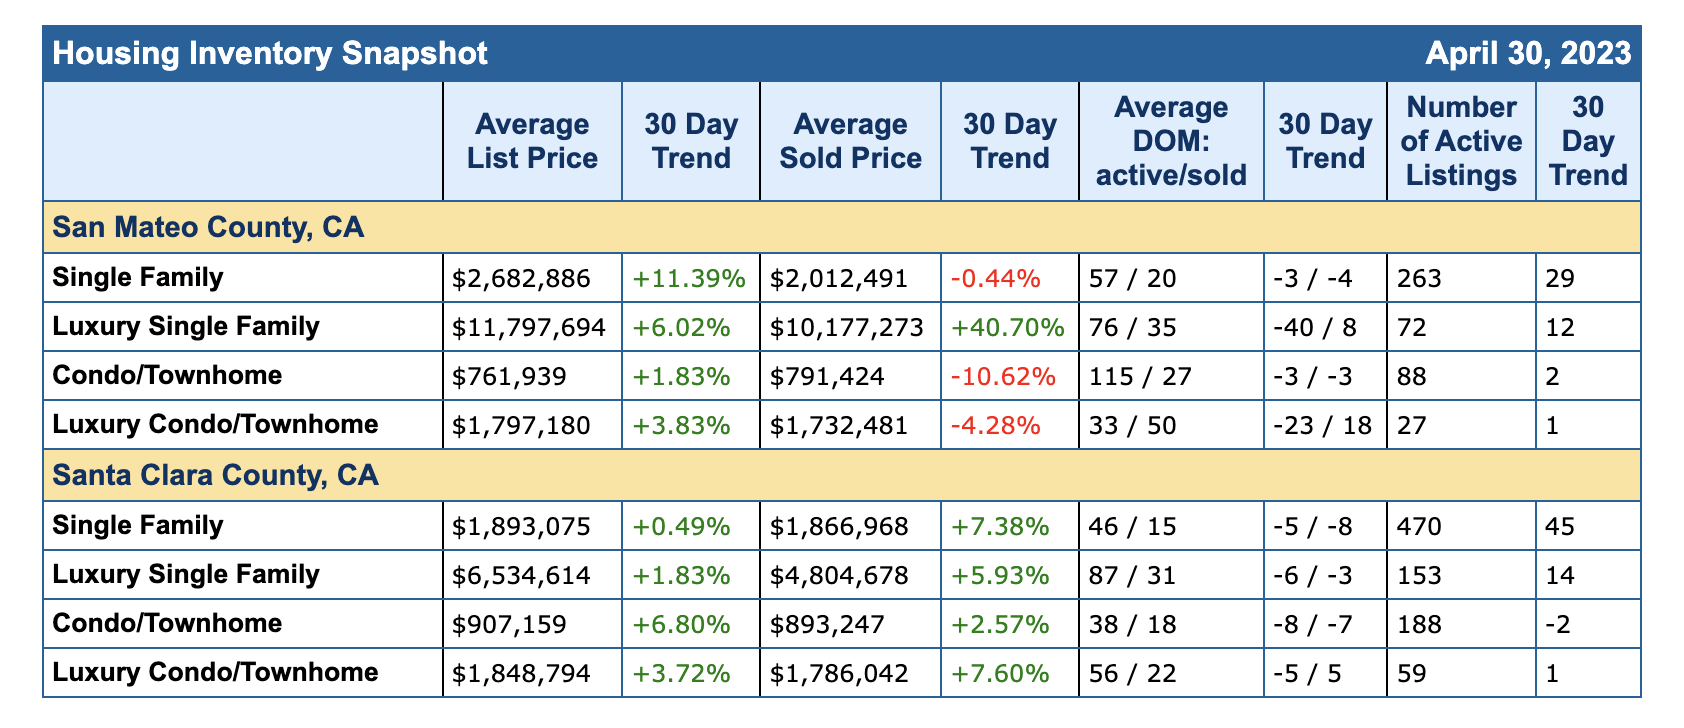
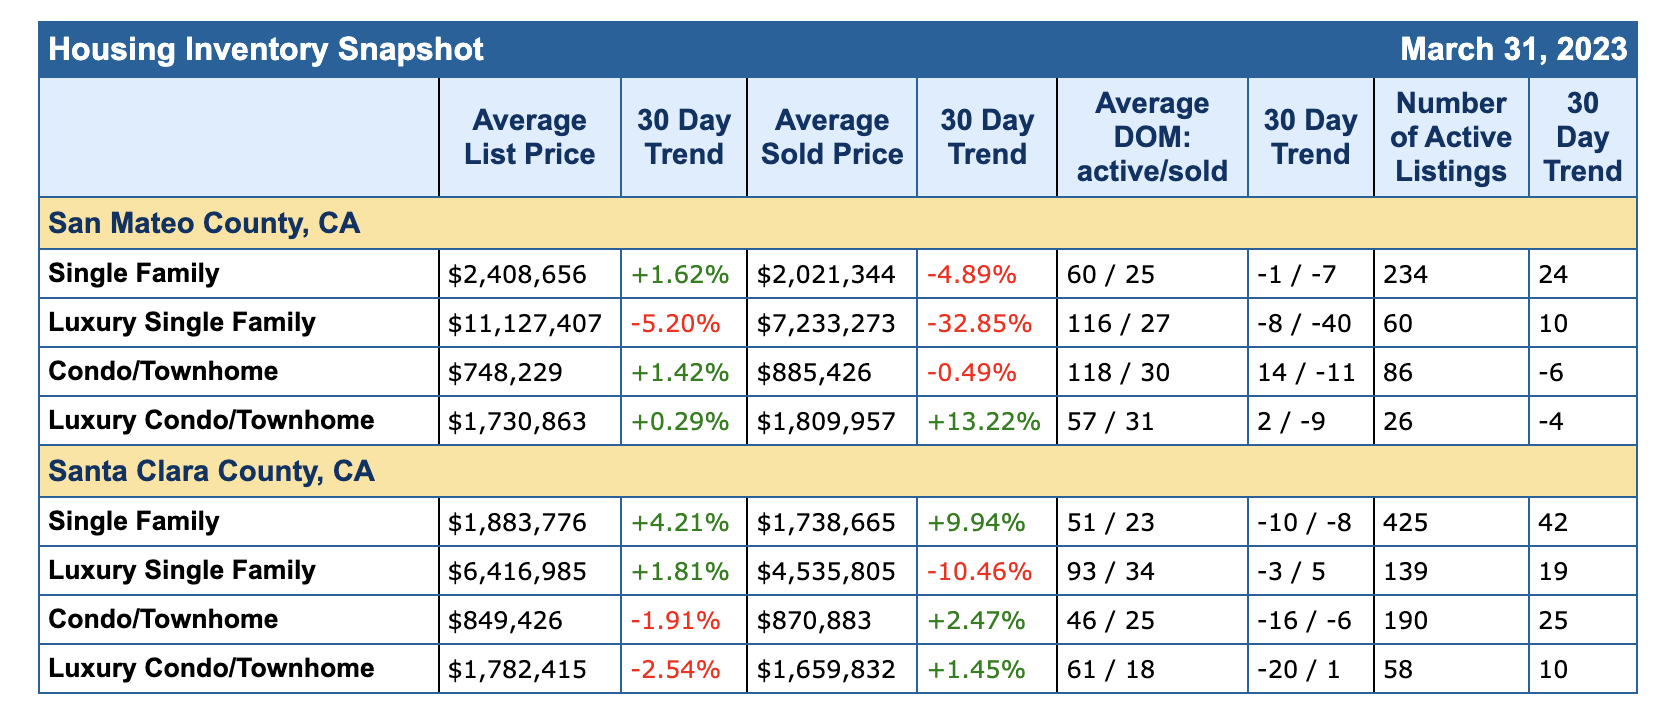
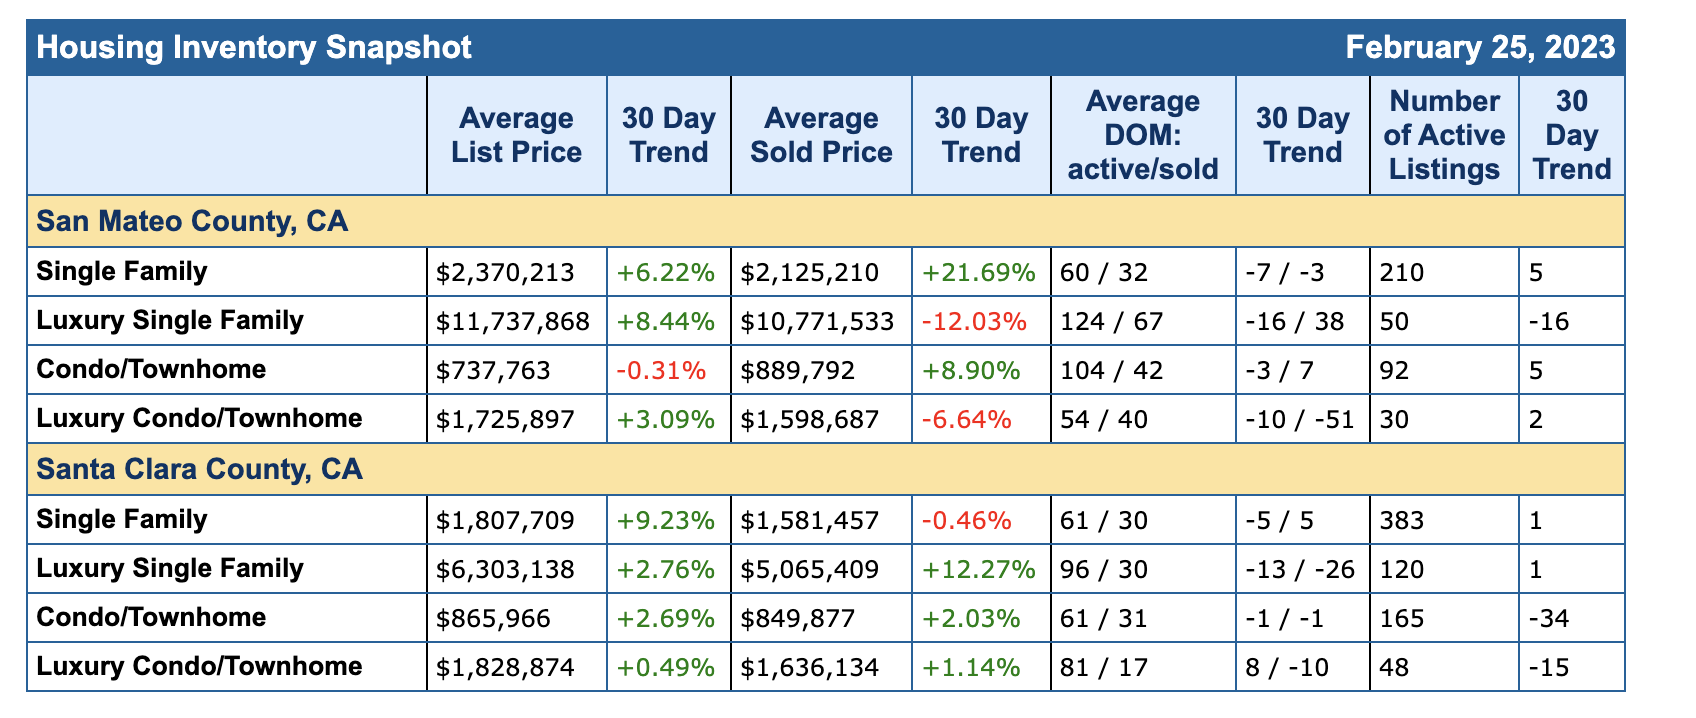
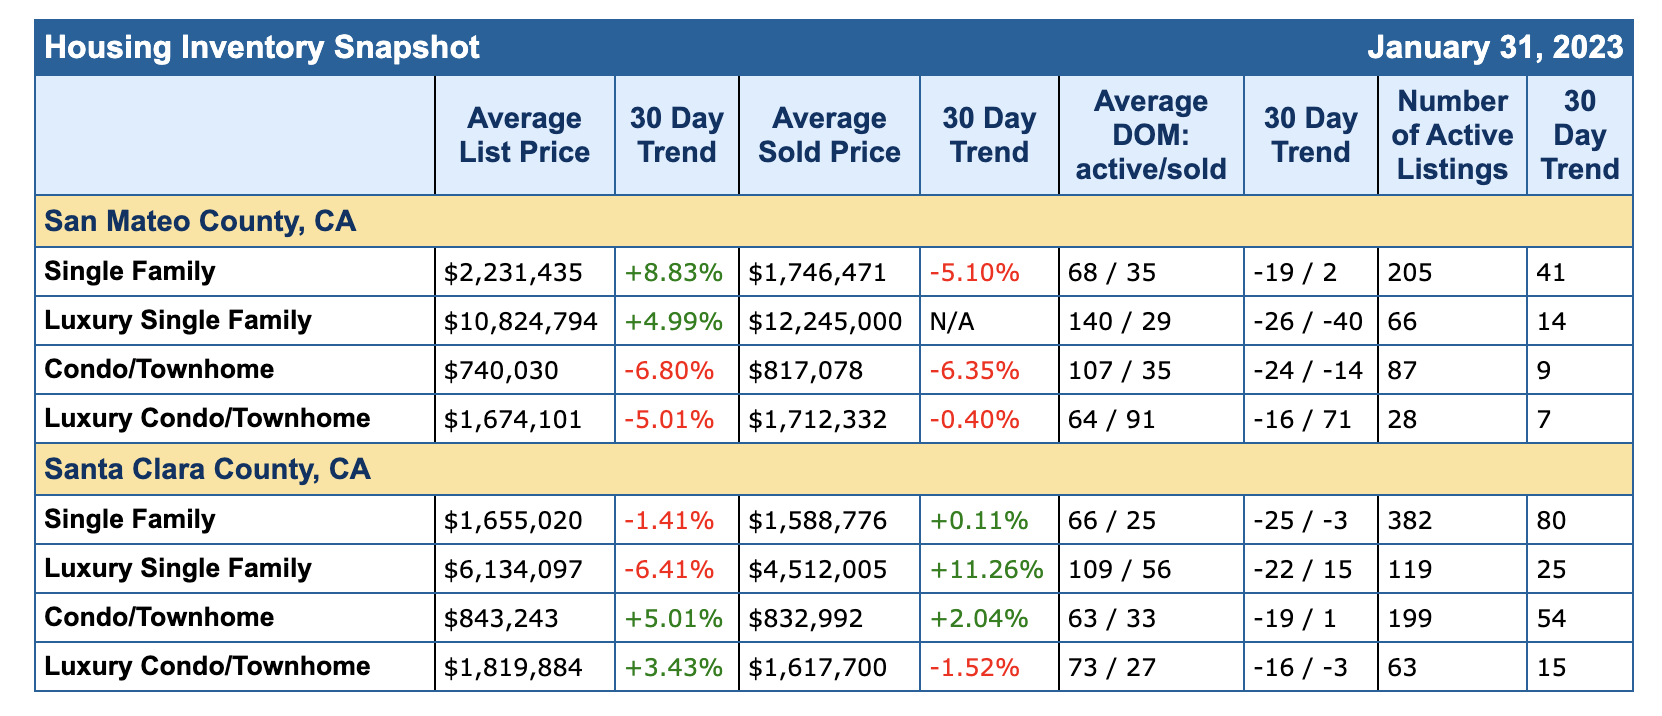
Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 45 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home

Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

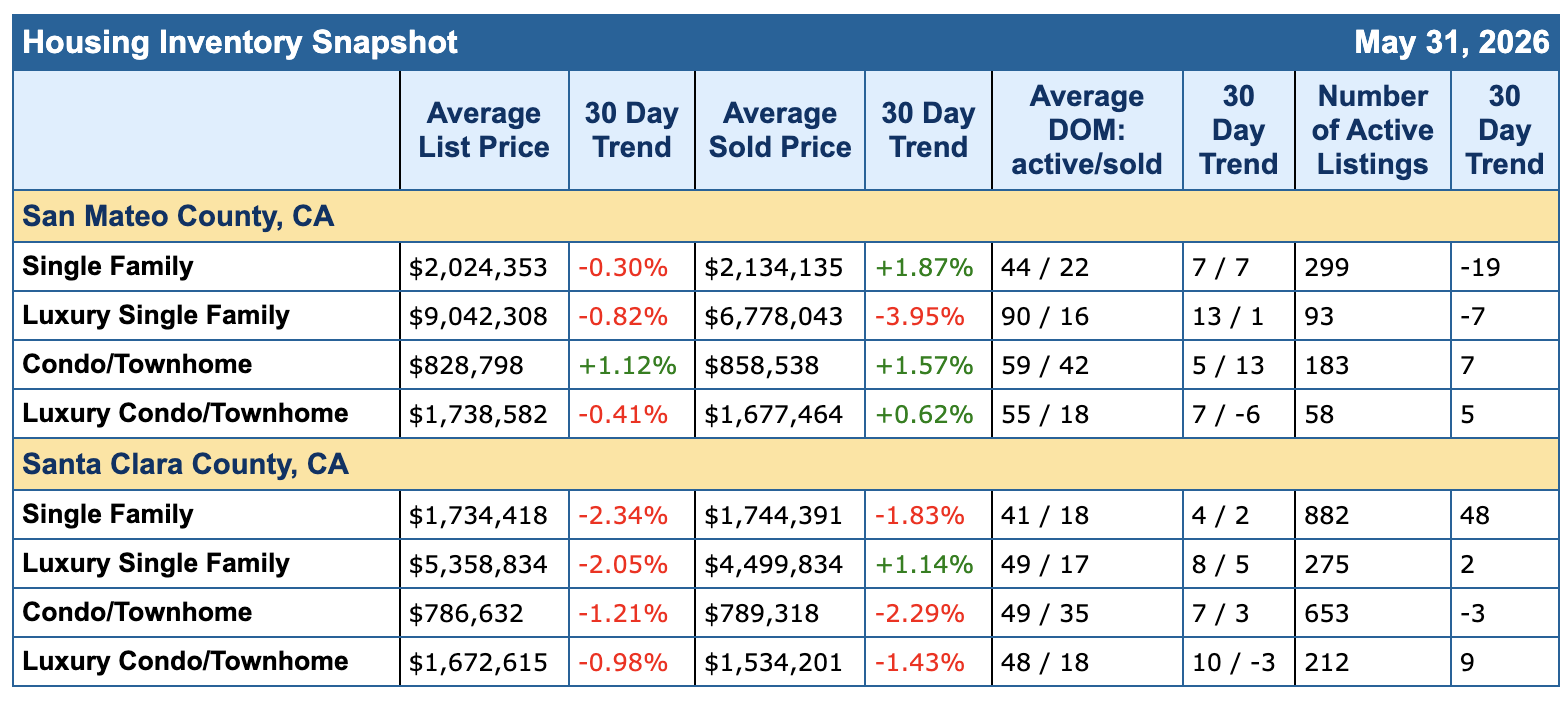
The Stats are In… Market Snapshot for May & June 2026

Hello Caton Team Blog Readers,

Thank you for tuning in. The stats are in for May and June 2026.

Welp – in May we saw all market points take a dip. With a slight rise in May and June for Condos / Townhomes. Across the board we are seeing a dip in sales. Is it seasonal? Doesn’t feel that way – we often see a good boost in sales each May – as that is the start of selling season and June often holds steady but this year is a bit different. There is so much going on in the world, economically and socially.

With no expected drop in interest rates and the cost of gas and groceries at an all time high. Folks are feeling it. When fear prevails, or concern, we see a dip in sales, and a dip in active buyers. Oddly enough – this sort of data makes the market ripe for buyers but not everyone feels they can take the plunge.

When the market is weird, it is actually a great time to buy in the Bay Area. Some homes still get multiple offers but some do not – and instead of waiting for a price drop – when you work with professional Realtors like The Caton Team – we search those over looked properties – and show them. Don’t wait for a price drop – if you’ve watched a home and it has not sold in 2 -3 weeks – have your agent contact their agent and get the whole picture. We do not wait for price reductions – we are proactive and will see if there is middle ground a buyer and seller can stand on.

With values dipping .8% – 13% – that is a market for buyers! Sellers are not seeing the demand we once had when rates were lower and if a seller has to sell, they are taking a moment to grieve their lost value and hopefully moving forward. The market is the people and what the people are feeling.

If you want to live in the Bay Area, if you have a steady job here and want to grow roots here – NOW – is a great time to buy. There are properties sitting, there are price reductions – this is an opportunity for a buyer to get a house, even under list with contingencies! As long as you see yourself here for about 7-10 years – that is the normal time it takes to see appriciation. The longer you hold onto a home, the better. So when the market is soft and you have long terms goals here – let’s jump in.

The Caton Team provides free buying and selling consultations – to determine the current value of your home if you are selling or if you’re in the market to buy – where you get the most bang for your buck.

Remember, each neighborhood is different, if you are considering a purchase – let us guide you through this and help you find your way home.

If you’re in the market to sell – each area and price point has it’s own pros and cons – let us help you figure out your next steps.

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home. We have before and we will again. We move with the market.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at sabrina_caton@yahoo.com.

Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 45 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

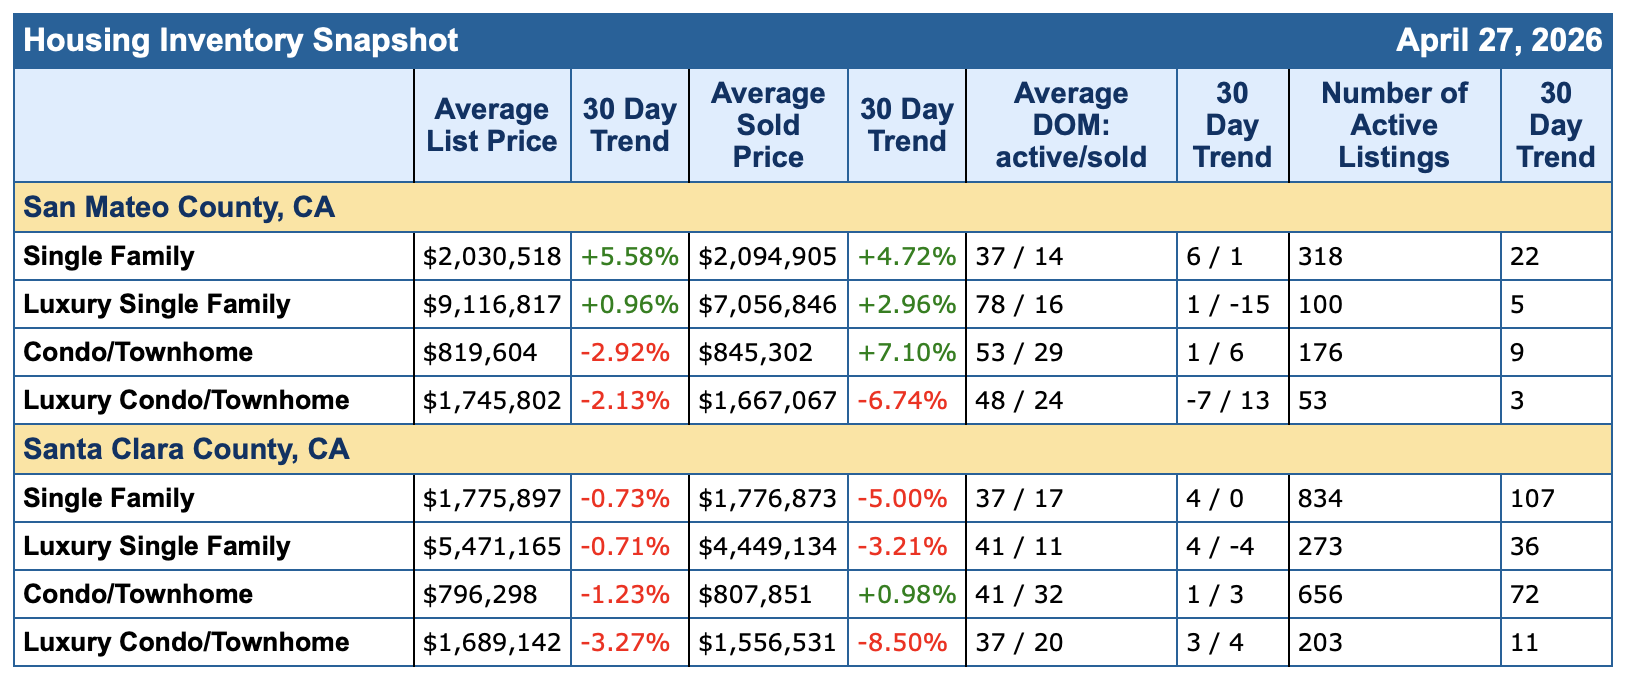
The Stats are In… Market Snapshot for April 2026

Hello Caton Team Blog Readers,

The stats are in for April 2026.

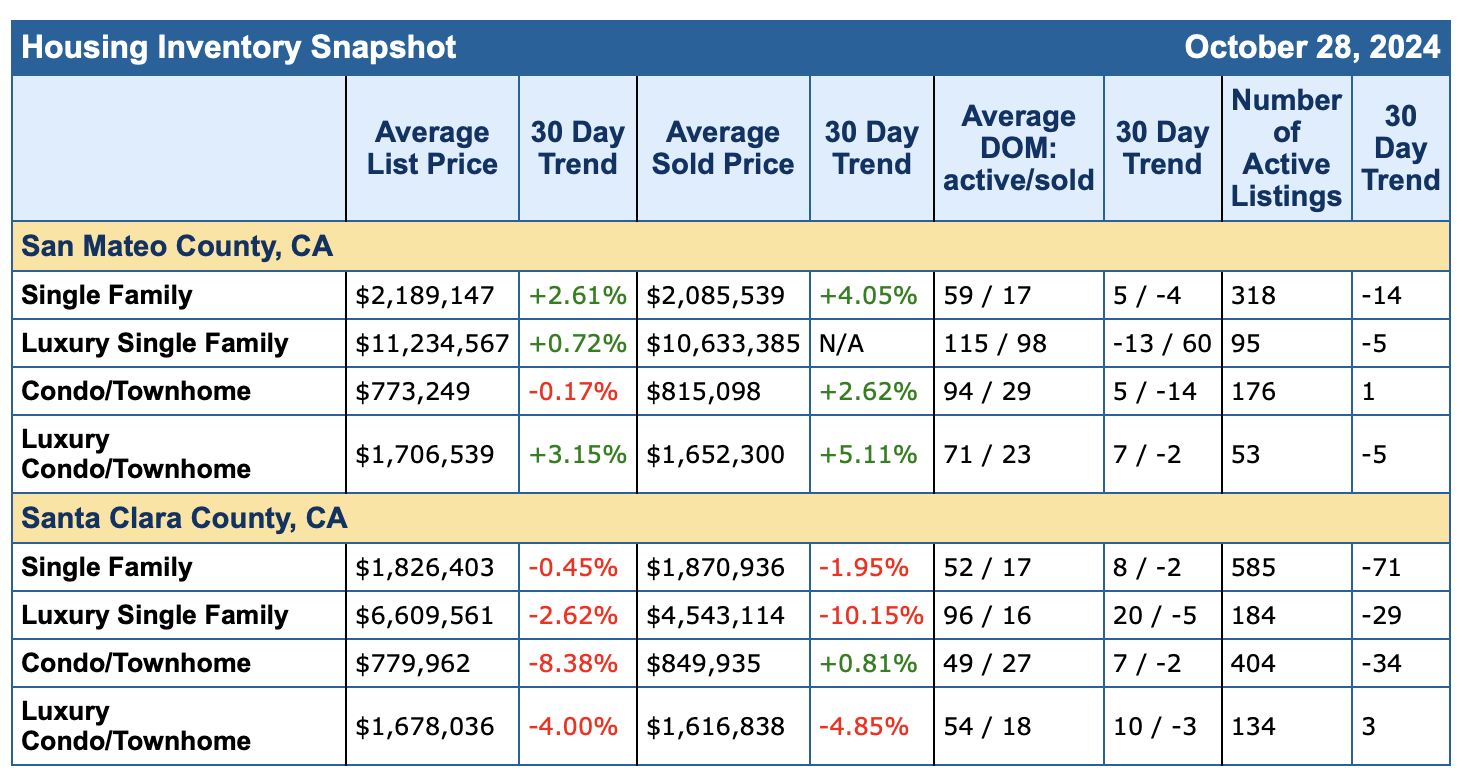
Oddly enough – the high-end sector is doing great! Homes above 2 million are selling and with multiple offers.

However – with the cost of gas and groceries – we’re seeing some adjustment in the market. Interest rates are holding where they are – so no relief in sight for the buyers on that front. Which oddly enough makes it a bit of a buyers market. So keep saving, keep looking and if you are in the market to buy – each neighborhood is different, so let us guide you through this and help you find your way home.

If you’re in the market to sell – each area and price point has it’s own pros and cons – let us help you figure out your next steps.

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at info@TheCatonTeam.com.

Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 40 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

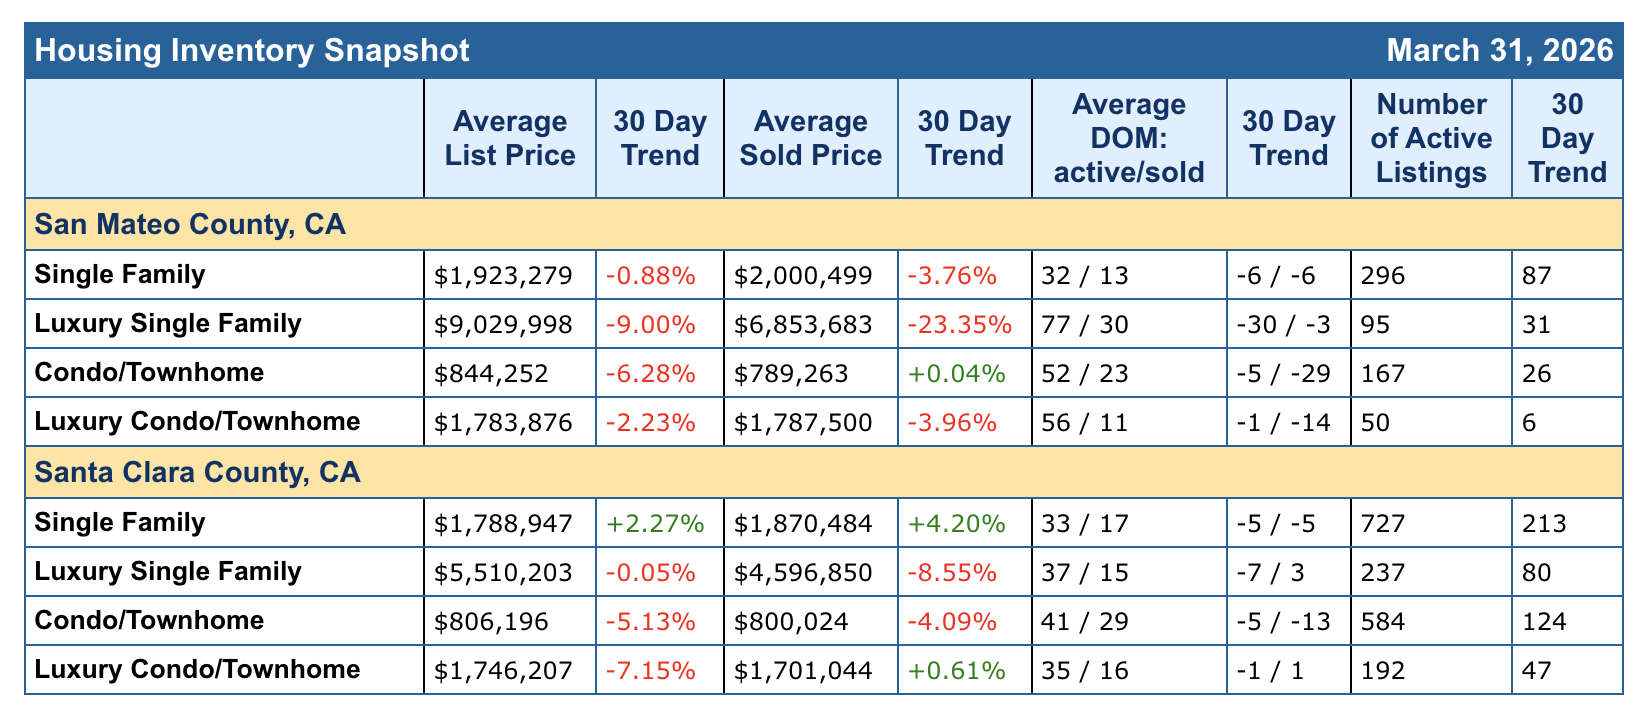
The Stats are In… Market Snapshot for Feb 2026 & March 2026

Hello Caton Team Friends,

The stats are in for Feb & Mar 2026.

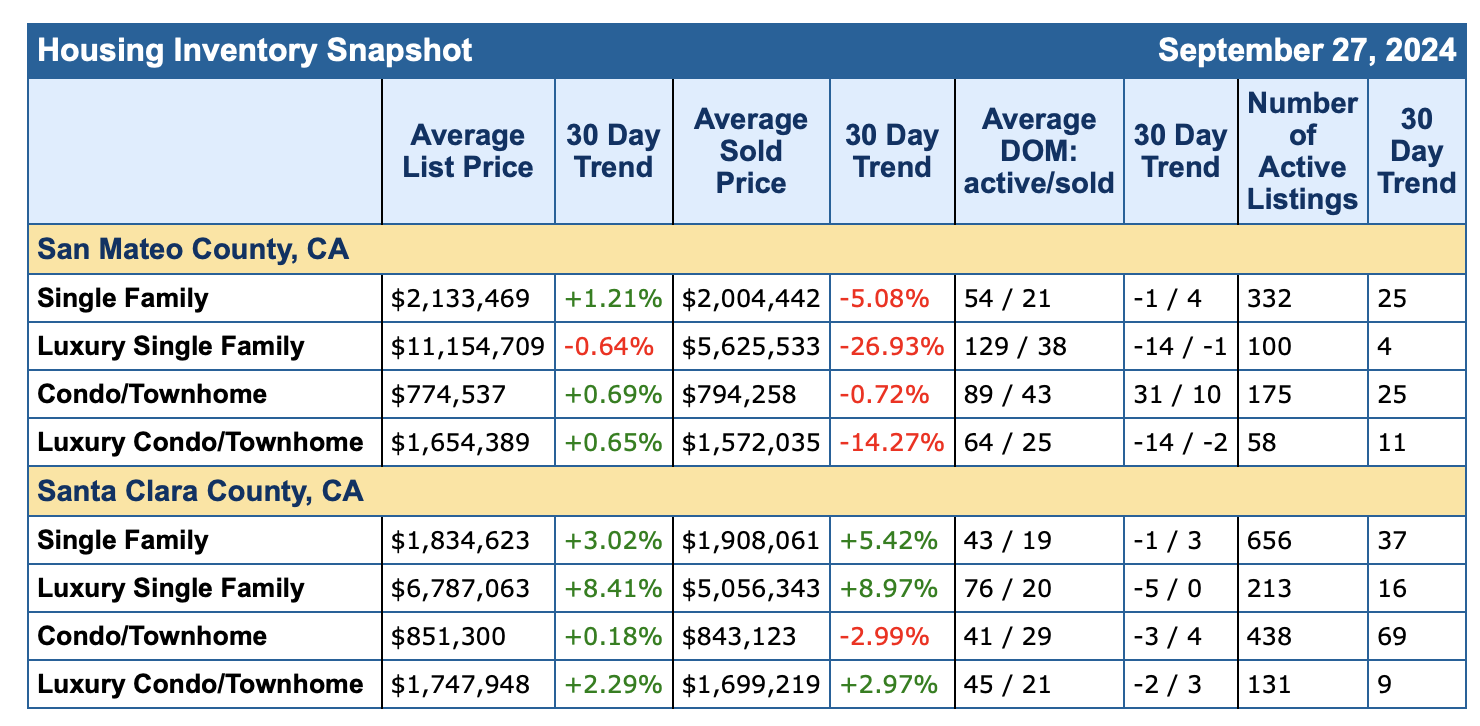
What gain we saw in Feb has tempered in March. We are midway through April and I can feel the cold thawing. Buyers are doing their homework, loan shopping and budget making. While sellers are getting their homes ready for the Spring Market that officially starts on May 1. Are you ready?

There was slight price adjustments in March, which still feels seasonal. Buyer right now are weighing so much, the interest rates haven’t fallen much, hovering around 6%+, the state of the economy and the world has folks on edge. But not off the table. With caution and a solid plan, I am seeing my clients make their Real Estate goals work! How can The Caton Team help you?

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at info@TheCatonTeam.com.

Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 40 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

How to Sell and Buy Real Estate in Today’s Market

Are you a Move Up Buyer in Silicon Valley? Then you know how hard it is to achieve that goal and make it a reality.  It is much more challenging to sell and buy due to the market’s dynamics.

If you’re a Buyer in Silicon Valley, then you are well aware of how competitive it is to get a house, condo, or townhome. A Buyer may have started with the want list and then quickly condensed it.

What makes buying or move-up buying a challenge?

The Bay Area has limited space to build.  Land is the gold of Real Estate; without land, you cannot build more homes.  So, if you want to own a home around here, be prepared for possible bidding wars.

But if you’re a Buyer with a home to sell first, then you’re really up for a challenge.  But! The Caton Team is here to help you create a plan for success.

Seller EXPECTATIONS in a Seller’s Market

If you’re a Seller these days, you have some expectations, and when the market is in your favor. It’s great.

During a Sellers market, with multiple Buyers for each home, a Buyer must put their best foot forward to succeed, and truly, this goes for any market. Here are some suggestions:

OFFER OVER LIST PRICE – sometimes even more than the Comparative Market Analysis (CMA) warrants.  This can be frightening and can set up a Buyer for some surprises.
The Caton Team always prepares a CMA and gauges market activity to help a Buyer determine their right price. The Buyer will also choose the price they want to offer. We are here to guide you with data.

WAIVE CONTINGENCIES – These days, a Buyer should not ask for repairs but account for them. It’s also hard to request time to sell their current home first.  If a Buyer wants to be a contender, it can feel like they must come in Non-Contingent and ready to close.  Let me rephrase that.  A Buyer should write their best offer, and if that includes a contingency, the Buyer must do what is best for them.  Just know – if there are too many contingencies – generally that offer goes to the bottom of the stack because in a Sellers market, the Seller often has plenty of offers to choose from and does NOT have to accept a Contingent Offer.  (Note, in cooler markets Buyers have more leverage and will have the opportunity to ask for contingencies.)

PROOF OF FUNDS – A Buyer MUST HAVE ALL their down payment, closing costs, and reserve monies ready from DAY 1!  Not only for their bank loan approval, but Buyers also need proof of funds just to write a contending offer!  To be frank, sometimes a great offer is beat out by an offer with “better” proof of funds – IE, money in the bank.

Each Seller and their Realtor will REQUIRE Proof of Funds to be submitted WITH the Offer.  Meaning your Realtor needs recent copies of all your bank statements to be provided in your Offer Package to show the money for the downpayment, closing costs, and reserves are liquid and real. You would too if you were in the Seller seat.  Our job as Realtors is to protect OUR Clients’ best interests.  Meaning, when working with Sellers and reviewing offers, not only does The Caton Team call each lender to verify loan strength – we also want to see Proof of Funds totaling at minimum the monies for said deal AND reserve funds which are healthy and liquid to ensure –  if things go awry – there are funds to close on time.  In other words, the strongest reserves have an impact on what is considered the “Best” offer.  It is not always price that equates to “Best”.  (Curious why?  – Ask us anytime – that topic is for another blog post.)

An example of a Buyer’s surprise is when the appraised value is lower than the offer price.  The Buyer may want to pay the difference between the appraised value and the offer price, and that too is a conversation on what’s best for the client.  There is no “cold feet” in Real Estate; quitting on a Non-Contingent Offer means the Buyer could forfeit all or a portion of their good faith deposit, which is 3% of the total purchase price.  Note – each case is different, and this is just an example.  Bottom line – selling Real Estate is serious business, and being prepared is the first step.

There are several more items that make up the Perfect Offer Package. If you want to stand out and succeed, contact The Caton Team today! We’re eager to chat and develop a personalized plan to help you reach your real estate goals.

Ok, so now you have an idea of what it takes to buy a home around here.  Now, what do you do if you have a home to sell first?  Bear with me on this – it is the hottest topic in Real Estate today.

HOW TO SELL THEN BUY

If you’re lucky enough to already be a Silicon Valley homeowner – congratulations!  You’re ahead of the game.  Right?  Unless you need more space and want to move up.  

The Caton Team has met many clients who opted to add onto their existing homes.  Great!  Unless that is not an option.  Then we are back to square one; how does a Buyer sell, then buy in this market?

As I stated above in Seller Expectations, the “requirements” for contention can feel like a tall order.  If your down payment funds are tied up in the equity of your home, you have several options, but only a few are viable.

DREAM OPTION

Rich Aunt Sally gifts you the money you need for the purchase of the home.  Thank you, Aunt Sally.  But what if we don’t have rich relatives?

SELL FIRST OPTION

This is the cut-and-dry option.  Sell the home.  Close Escrow.  Move out and into a short-term rental or with relatives.  Bank the proceeds of the sale – aka: the future downpayment and enjoy the Home Buying Experience at your own pace, knowing you can A) Prove your Funds are liquid and B) write an offer non-contingent on selling your home first. In a Seller’s market, an offer contingent on selling doesn’t always fly, and if it does, you’ve got to act fast and sell your home, as you will have a time frame. So your current home better be ready to go on the market, packed, inspected, and show-ready.

Oh – Did I mention this option is also terrifying?  A Seller feels as if they are losing their only piece of California – the “what if we don’t get the next one” can be frightening.  So it is important to weigh all options.

Next up…

SELL FIRST WITH RENT-BACK OPTION

Similar to the first scenario – except instead of moving out at the close ofescrow – the Seller is granted Rent Back to live in the home for an agreed-upon and short timeframe for a negotiated price, then move out – whether or not the Seller has acquired their next purchase.  The advantage to this is the closing – the Seller has the proceeds in the bank and can write a non-contingent offer on their next home.  The downside – it is a short-term solution – if the Seller doesn’t find their next home within the time frame, they will have to move out when the tenancy is over, no matter what.  Also, of late, this is frowned upon due to insurance issues or higher premiums since the home is a “rental” in the eyes of the buyer’s bank, and that could equate to a higher interest rate on their loan. We see short-term rentals but longer ones – far less.

OBTAIN AN OFFER TO PURCHASE

This option is often the first step – the proverbial toe in the water.  We, as your Realtors, will try to find a Buyer willing to do the following:

Offer to Purchase the home with an Extended Close of Escrow, giving the Seller time to acquire their next property (most likely contingent on closing on their current home), then quickly close on their next home – a domino closing effect.  The downside, their proceeds are not in the bank, possibly hindering their chances. Their Proof of Funds will be short, and even if the owner writes a Non-Contingent Offer – we as Realtors know – it isn’t over until it’s over.  In other words, when Sellers compare offers, the one with fewer strings attached generally wins.  Even Non-Contingent Offers in this scenario are not as strong as  Buyers ready, willing, and able to close on time.  IE:  Don’t have to close one house before they can close on the other.  Confusing right?

That’s why, inevitably, if a client truly needs more space and cannot add on, they often are forced to sell first, rent, then buy because this market is too competitive to request contingencies from the Seller.

– Please don’t shoot the messenger –

THE BRIDGE LOAN

Another option is to obtain a bridge loan. A bridge loan gives the owner the opportunity to purchase their next home before selling their current home. This can be an expensive option. Interest rates and fees are higher. But it gives the client the peace of mind that they know where they’re going before they sell their current home, and they only move once.

THE LONG ROAD

Now here’s another idea – but it takes a few years, and you truly need to ask your CPA and Financial Advisor about this. The idea is to convert your primary residence into an investment property – then do a 1031 exchange. First, the Seller moves out. The Seller then converts their personal residence into a rental – renting it out for a minimum of 2 years.  (I cannot give tax advice, so please verify with your CPA).  After those two years, the Seller sells their home as a 1031 exchange, then buys their next home as another investment.  The caveat – the Seller cannot move into their new home until it’s been rented for at least 2 years. Again, run this by your CPA, as tax laws change, and I am not a CPA.  Anyway, this is the long-term approach.  The good news, especially if you’re buying in the same community, even if prices rise, hopefully so will the value of your current investment.  

Anyway, can you tell I have several clients in the same boat? Each client situation is unique. This blog post was really just me organizing my thoughts, then I figured – why not share this – if I can help someone make a better decision for their future, then I did my job today.

THINGS TO CONSIDER

No matter what you’re planning to do. The first true step in Real Estate is to apply for your loan and determine your affordability for the next purchase. Figuring out what your monthly payment is and how much of a down payment you need is the most crucial step. This will help us figure out how to move forward on your goal.

Does the home you have to sell have enough equity to be your down payment? Or will you need to bring funds to the table to have a more manageable monthly payment? What is a comfortable monthly payment for you?

There are many choices associated with this, and that is why The Caton Team is here to help. Email us at info@TheCatonTeam.com

Remember, Interest Rates will rise and fall, and impact a Buyer’s monthly outlay. This affects prices. Rates rise, which can diminish a Buyer’s buying power.  As the interest rates rises the amount of the loan reduces.  To remedy this, a Buyer will need to bring in more money towards the downpayment.  Easy, if we have Aunt Sally on speed dial. If rates fall, we praise the Real Estate gods for their moment of affordability.

The Caton Team cannot forecast the future, but we have endured all sorts of markets and aided clients in various stages in our combined 40+ years.  The more homework a client does now, the better. The market is dynamic and always changing. We don’t want to see a Buyer wait themselves out of the market, and in an inclining market, that can happen faster than you think. Timing the market is hard, so it is best to focus on your goals, whether buying or selling, and working within the market you are experiencing.

Bottom line, we are here to help. Ask us all your questions – we’re in the trenches, we know what homes are selling for before the internet gets wind.  It’s wild out there, but we’ve got you covered.  Susan and I (Sabrina) have over 40+ years combined local real estate experience.  We represent our clients with integrity and grace.  Our offer packages stand out and often just have the edge a Buyer needs in this market.  Our Seller Package is successful, our negotiating is skilled, kind, and focused.  We pride ourselves on being effective, efficient, and responsive.

Real Estate is multi-faceted, and this blog is just the tip of the iceberg.  Each client has a unique set of needs.  We value the sit-down appointment to get to know what you need, whether buying or selling a home in the Bay Area.

What Can The Caton Team Do For You?

Thank you for reading and forgiving my typos. I wrote this…

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |

 EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team from our TESTIMONIALS.

Effective. Efficient. Responsive. The Caton Team 🏡  How can The Caton Team help You?

TESTIMONIALS | SELLING YOUR HOME WITH THE CATON TEAM | HOW TO SELL | VIRTUAL STAGING | BUYING YOUR HOME WITH THE CATON TEAM | BUYING INFO | MOVINGTESTIMONIALS

Get exclusive inside access when you follow us on Facebook & Instagram

TESTIMONIALS | SELLING YOUR HOME WITH THE CATON TEAM | HOW TO SELL | VIRTUAL STAGING | BUYING YOUR HOME WITH THE CATON TEAM | BUYING INFO | MOVINGTESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 | EMAIL |  WEB | BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

Website | The Caton Team Testimonials | Our Blog – The Real Estate Beat | Search for Homes | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina | Photography | Photography Blog 

Berkshire Hathaway HomeServices – Drysdale Properties, Redwood City Ca.

DRE # | Sabrina 01413526 | Susan 01238225 | Team 70000218 | Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

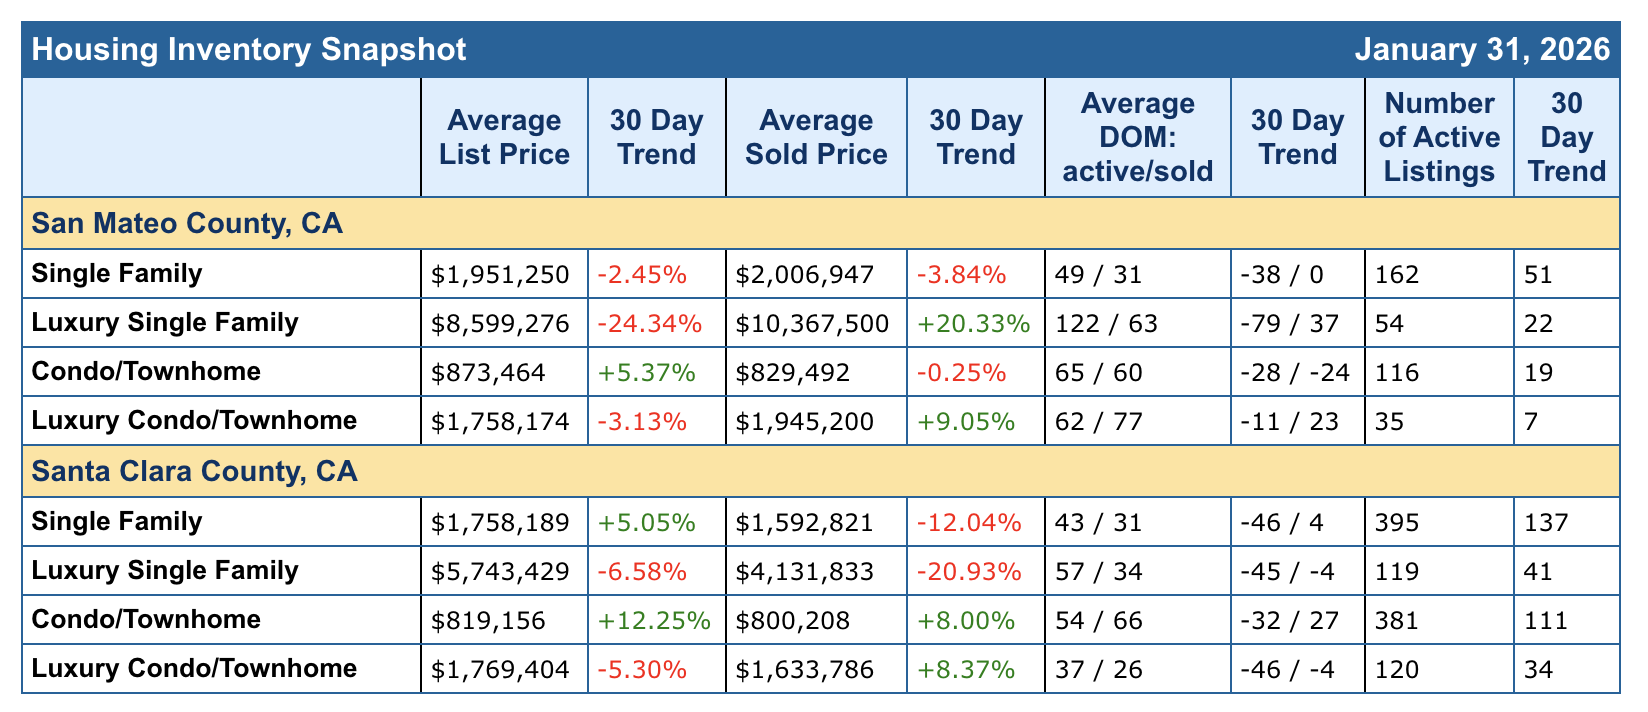
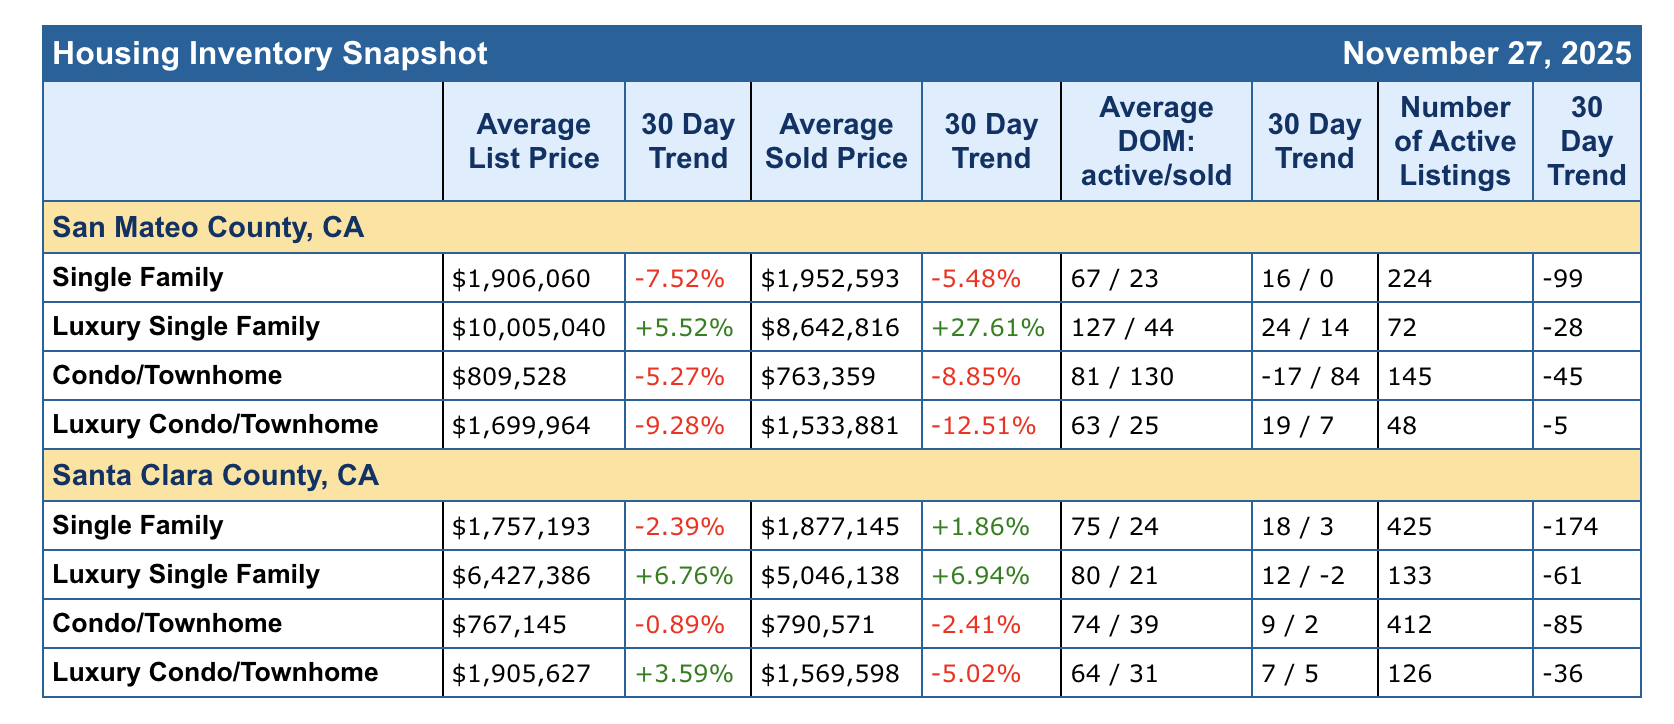
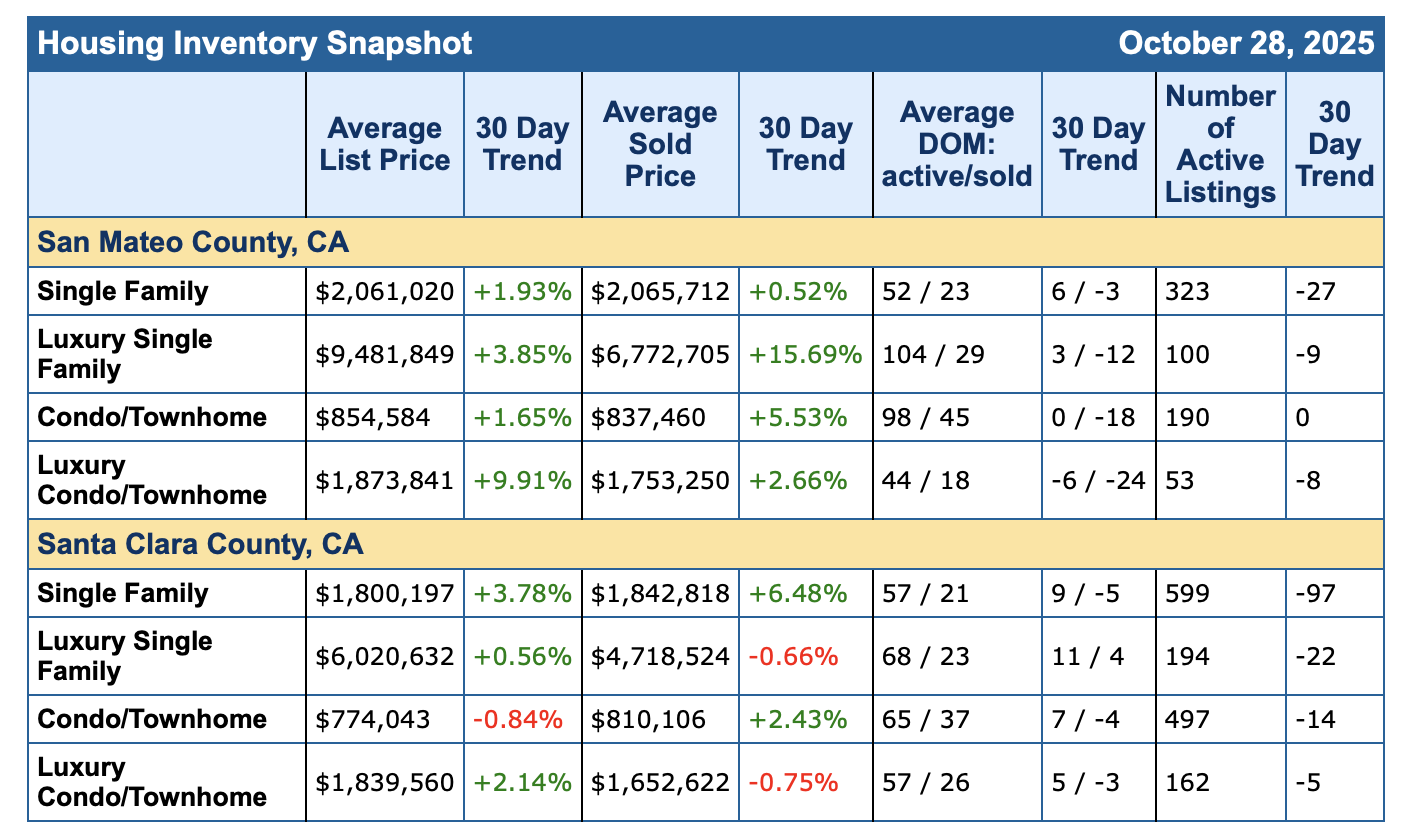
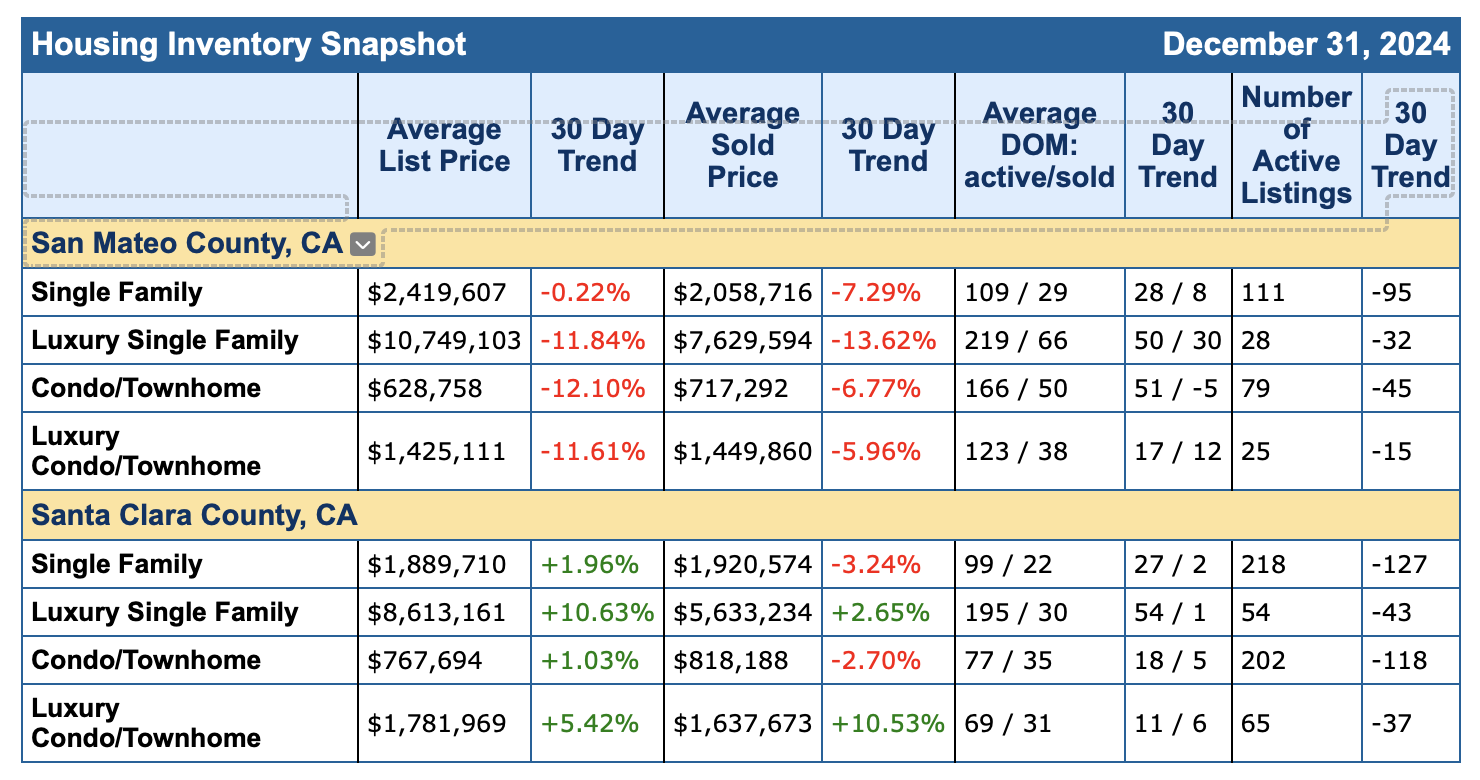
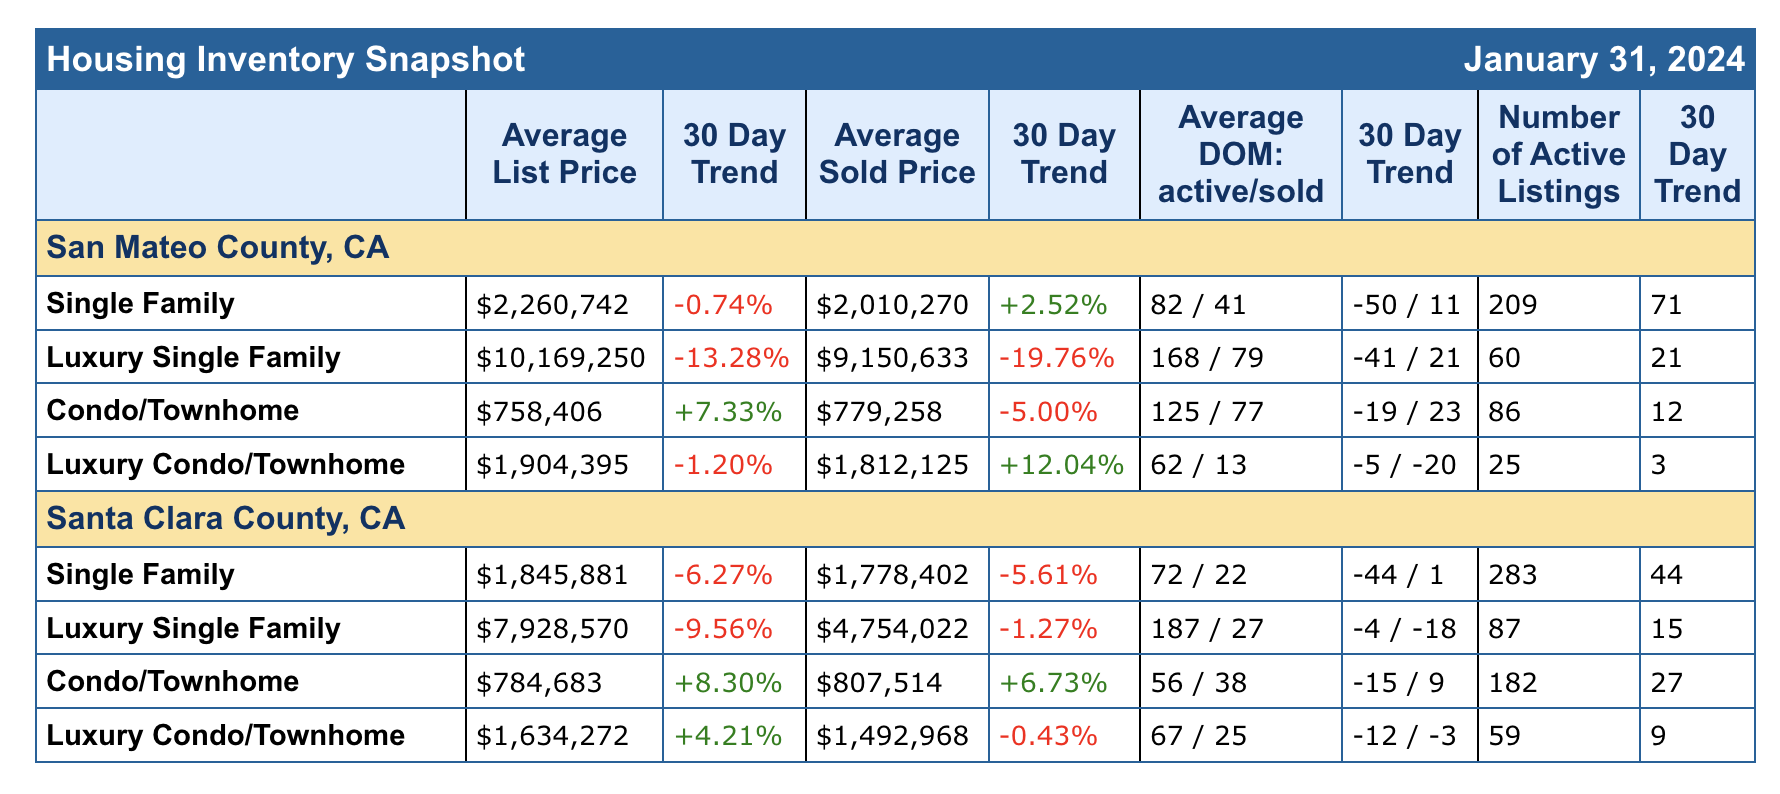
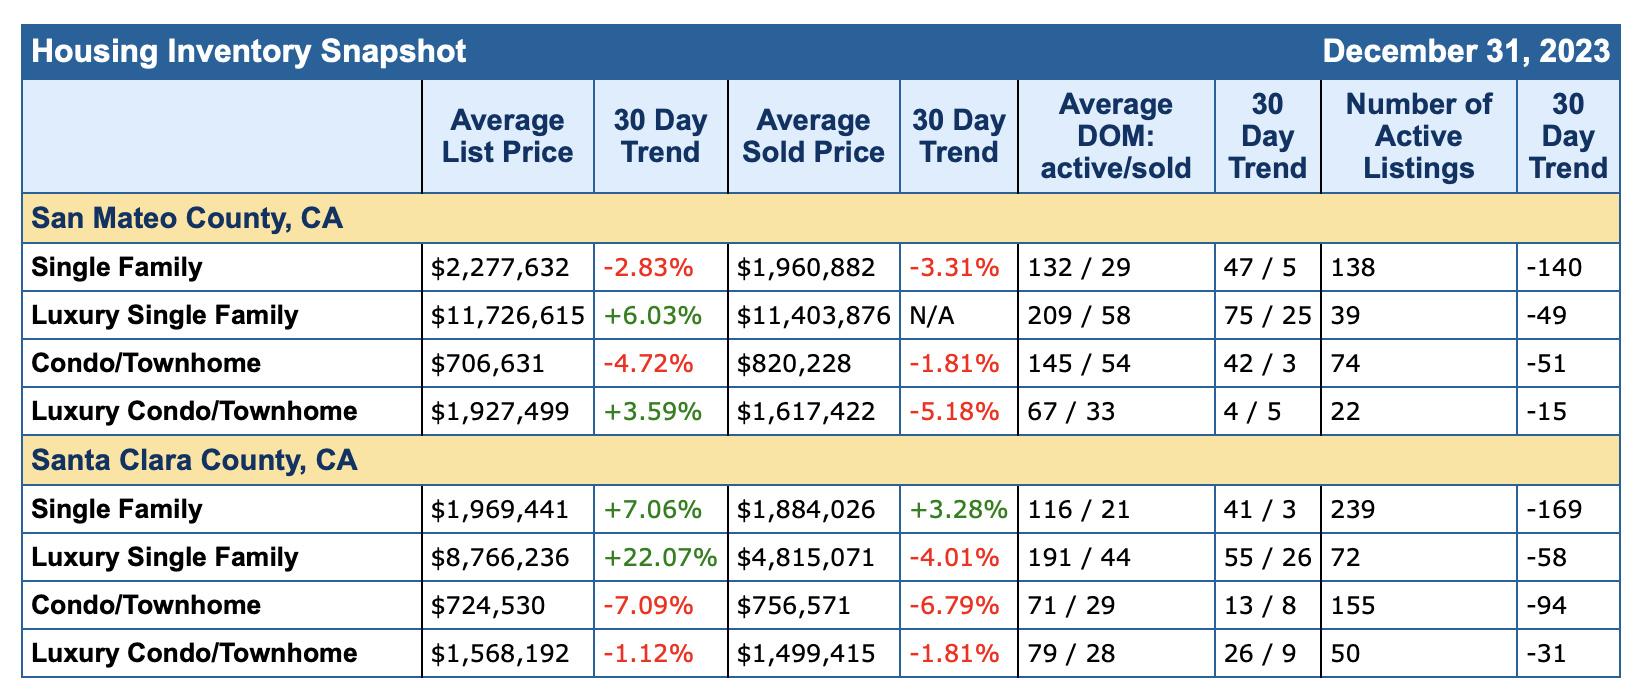
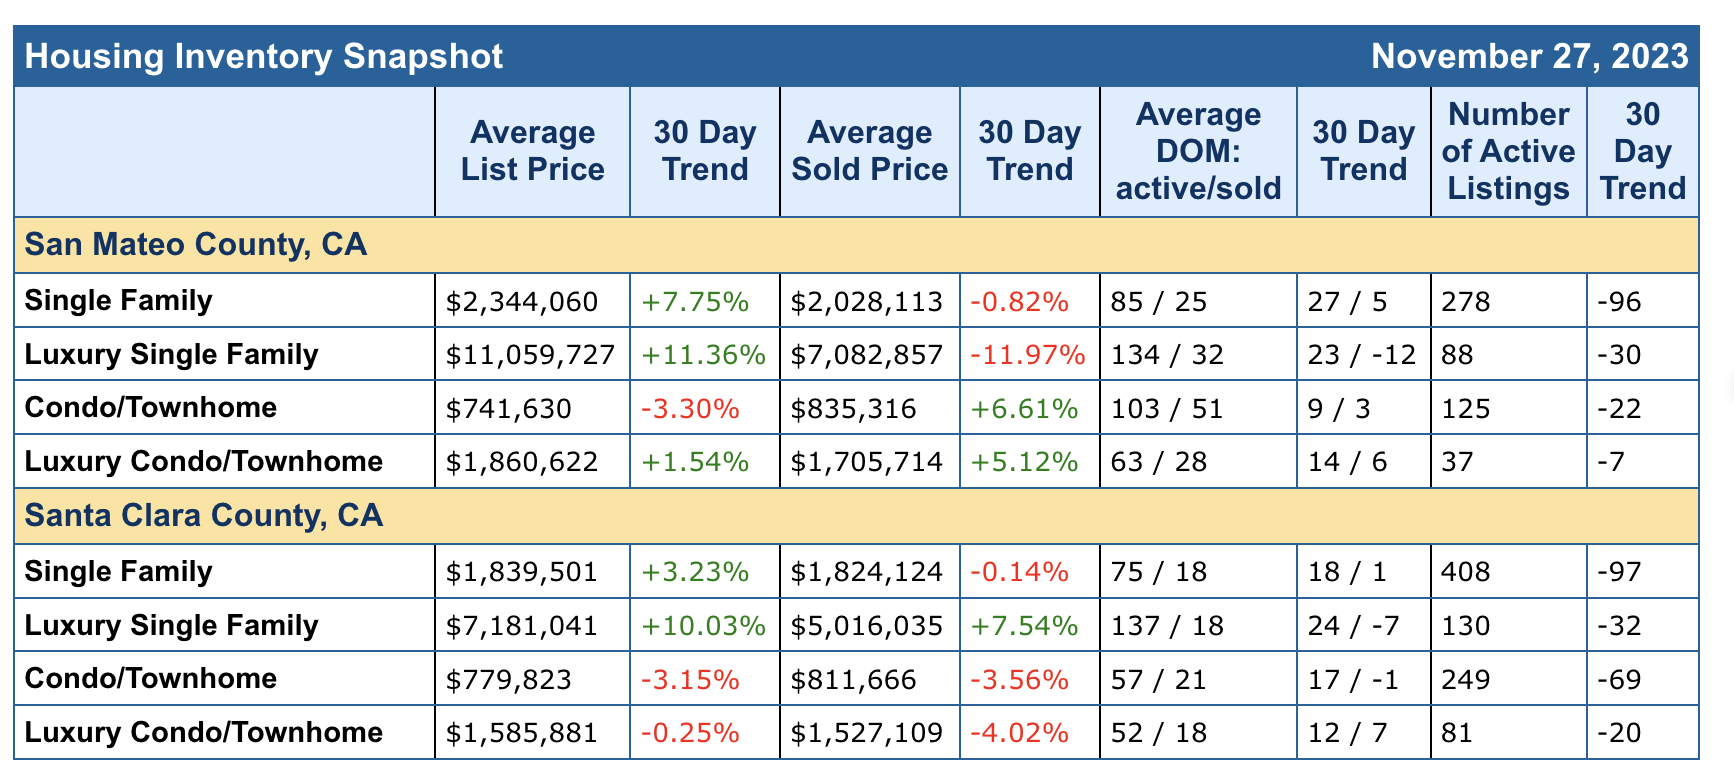
The Stats are In… Market Snapshot for Dec 2025 & Jan 2026

Hello Caton Team Friends,

The stats are in for Jan 2026 and December 2025. We saw a healthy December in San Mateo County with some adjustments in January. In my experience, in line with the habitual behavior of buyers in Winter. Condos are going strong, for those without balcony issues – which is a good indication of growth. We see the condo market as the first step to home ownership so we want to see healthy sales there, as buyers sell their condos and move into larger spaces, opening up that first rung to the next buyer.

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at info@TheCatonTeam.com.

Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 40 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

Home Sales To Remain in Low Gear as Balance Holds – Shared Article

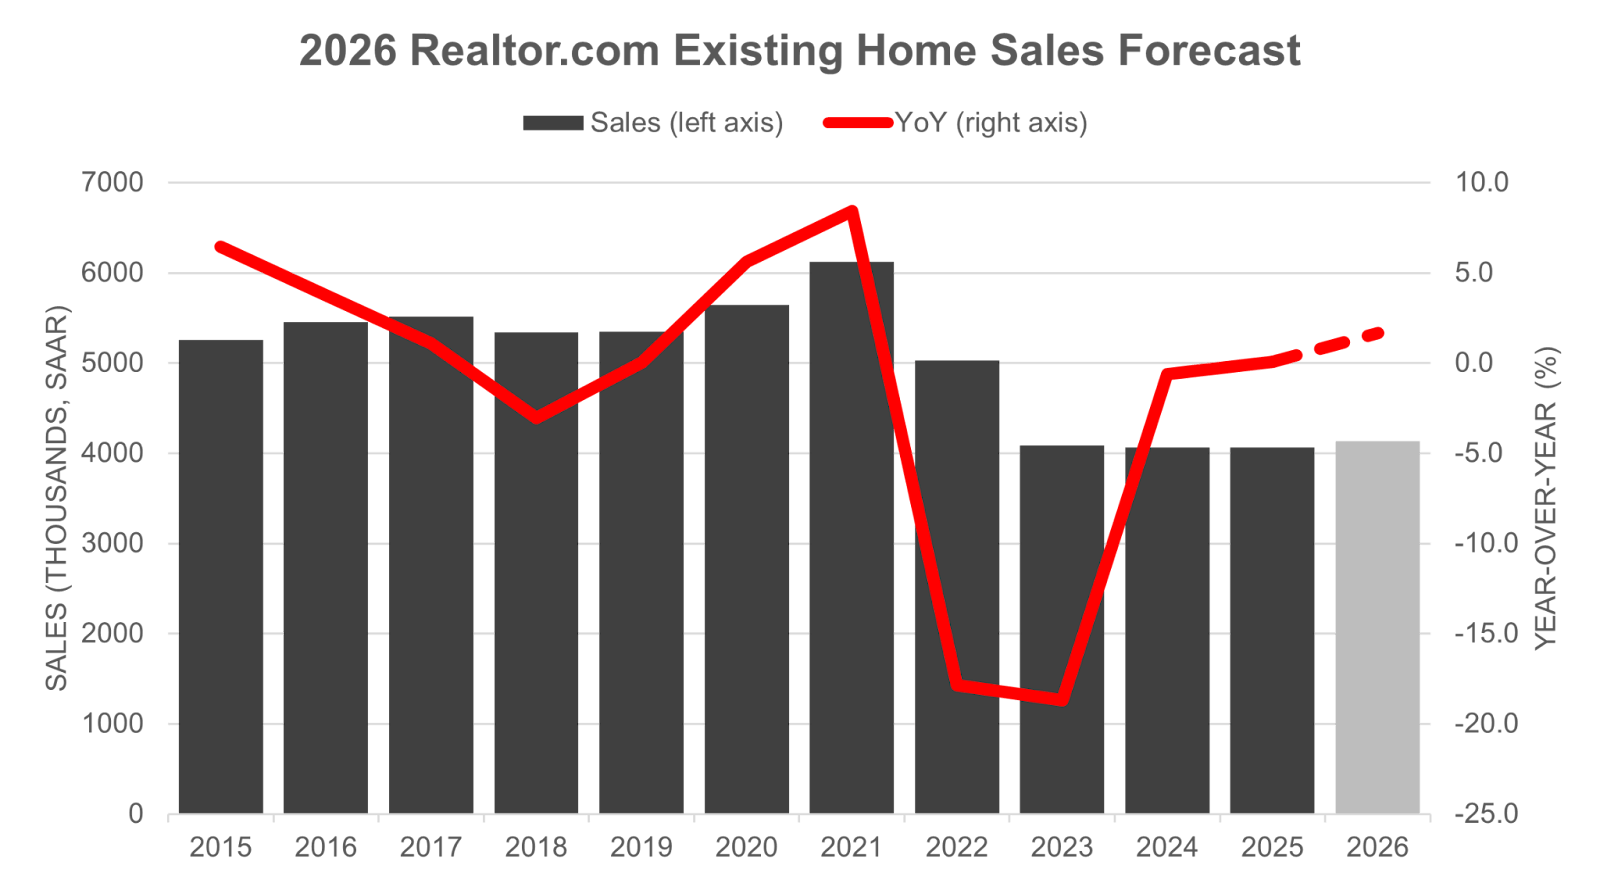
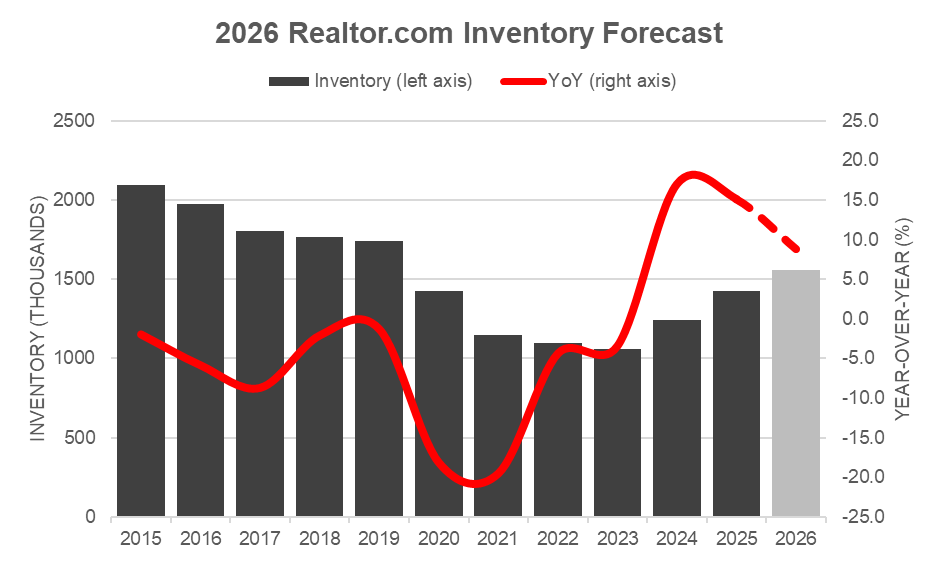
In 2026, we expect a steadier housing market, but it’s not yet off to the races. Mortgage rates are forecast to average 6.3%, easing affordability pressures slightly, while home prices rise modestly by 2.2%. Existing-home sales should climb about 1.7% to 4.13 million, a small but meaningful gain from 2025’s near 30-year low. At the same time, for-sale inventory will continue to recover, up nearly 9% year over year.

I read this article HERE. By Anthony Smith

For homebuyers and sellers, the shift signals a more balanced market—one where price growth steadies, rate relief offers breathing room, and negotiating power tilts subtly toward buyers. Housing affordability improves as incomes outpace inflation, pushing the typical payment share of income below 30% for the first time since 2022. 

Meanwhile, renters benefit from softening rents—especially in the South and West. 

Forecast Table

 2026 Realtor.com Forecast2025 Realtor.com Full-Year Expectations2024 Historical Data2013–19 Historical Average
Mortgage Rates6.3% (avg);
6.3% (year-end)
6.6% (avg);
6.3% (year-end)
6.7% (avg);
6.7% (year-end)
4.0% (avg)
Existing-Home Median Price Appreciation (YoY)+2.2%+2.0%+4.5%+6.5%
Existing-Home Sales (YoY | Annual Total)+1.7%
4.13 million
+0.1%
4.07 million
-0.6%
4.06 million
+2.1%
5.28 million
Existing-Home For-Sale Inventory (YoY)+8.9% +15.2% +15.2%-3.6%
Single-Family Home Housing Starts (YoY | Annual)+3.1%
1.00 million
-4.3%
0.97 million
+6.9%
1.02 million
0.77 million
Homeownership Rate64.8%65.1%65.6%64.2%
Rent Growth-1.0%-1.4%-0.6%+5.2%

Home Sales Rise Modestly From Long-Term Lows

Existing-home sales are expected to edge up 1.7% in 2026 after a nearly flat 2025. Even with this modest rebound, existing-home sales will remain well below normal as high prices and financing costs continue to hold back demand.  

If home sales eke out a gain in 2025, as anticipated, 2024 existing-home sales (4.06 million) will remain the record, 29-year low (in 1995, existing-home sales were 3,849,000). Looking ahead, we expect growth in home sales in 2026. Still, the improvement will be modest nationwide as familiar challenges—diminished affordability due to high prices and still-high mortgage rates—continue to weigh on homebuyers. 

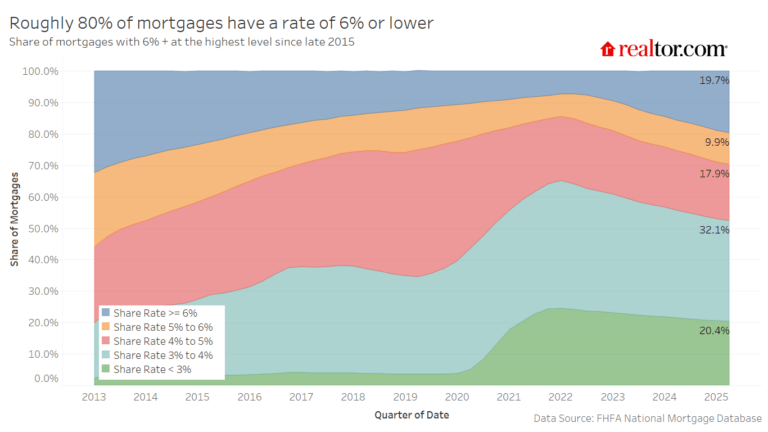
The mortgage rate lock-in effect—caused by market rates that are well above the rates on existing mortgages—has left many homeowners with a strong reason to stay put. In fact, recent data showed that 4 out of every 5 homeowners with a mortgage has a rate below 6%. The share has waned gradually, a trend that will continue in 2026. As a result, turnover will be limited with moves likely to be spurred by life necessities such as job or family changes.  

Home Prices Climb, but Not in Real Terms

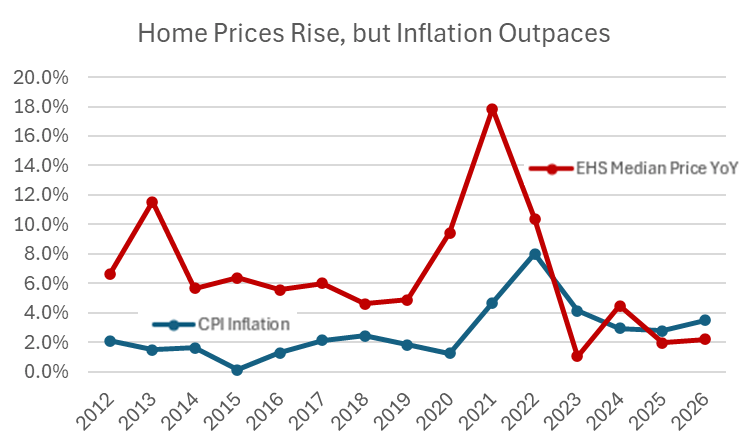
Home prices are expected to continue to climb in 2026, adding 2.2% for the typical home sold. These gains come on top of the 2% increase registered in 2025. However, inflation is expected to outpace these gains, with consumer prices likely growing more than 3%. That means real (inflation-adjusted) home prices will decline slightly for a second consecutive year.

This dynamic—nominal prices rising but real prices slipping—gradually improves affordability, even if it doesn’t feel like a dramatic shift to most buyers or sellers. Put simply, the sticker price of homes keeps going up, but the overall price level and incomes rise faster, meaning that it takes a smaller chunk of each paycheck to buy a home. The slow normalization process helps buyer incomes catch up.

Affordability Improves as Mortgage Rates Steady and Incomes Grow

Even though home prices are expected to go up, affordability is set to improve modestly in 2026. After higher-than-expected interest rates in most of 2025, mortgage rates finally relaxed in the second half of the year, dropping into the low 6% range. We expect the average 30-year fixed mortgage rate to remain roughly in this range throughout 2026, averaging 6.3%, as slowing economic growth and the end of the Fed’s quantitative tightening offset rising U.S. government debt and inflationary pressure that’s expected to be temporary. While this puts the average 30-year fixed mortgage rate on par with the last few months of 2025, it will mark a drop from 6.6% on average throughout 2025 as a whole. 

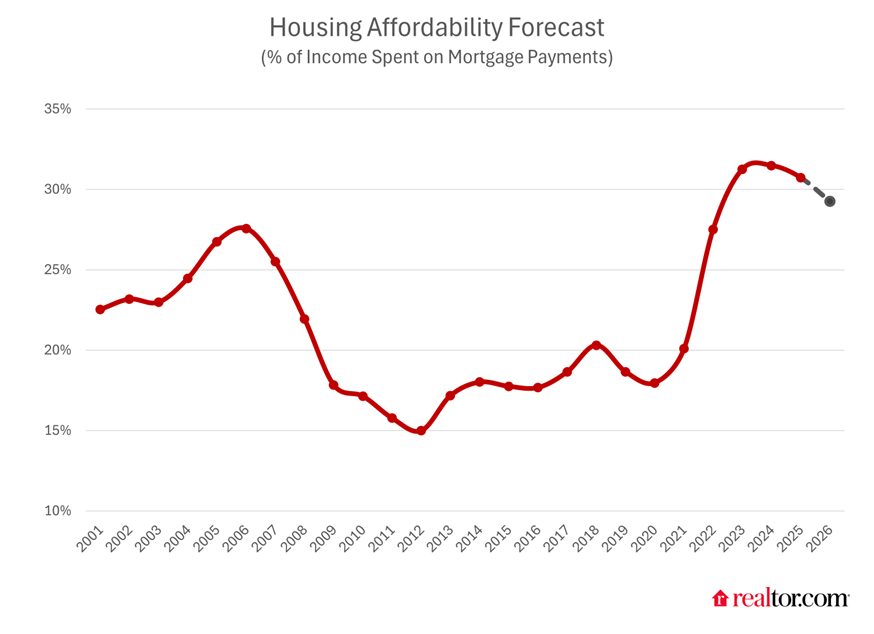
The typical monthly payment to buy the median-priced home sold is expected to fall 1.3% year over year as home price growth moderates and mortgage rates drop on average. This will mark the first decline in monthly payments on average across the year since 2020. Furthermore, rising incomes, which should outpace inflation, give buyers more purchasing power, helping to shrink the share of a paycheck that has to be put toward the mortgage. The monthly payment to buy the typical home is expected to slip to 29.3% of median income, its first year below the 30% affordability threshold since 2022, when mortgage rates shot higher. The gains may be modest, but they mark an important shift toward better conditions for homebuyers.

For-Sale Inventory Recovery Slows, but Still Outpaces Sales

Even though we saw some sellers delist rather than accept disappointing terms in 2025, the housing inventory recovery continued. The number of active for-sale listings marked two years of consistent growth in October, and the pace of annual unsold inventory recovery is likely to match 2024. Nevertheless, the pace of recovery has slowed as the market approaches pre-pandemic norms, and we expect this to continue in 2026. 

We project an 8.9% increase in active listings in 2026, marking a third consecutive year of gains. The pace of improvement has slowed, however, as the market edges closer to pre-pandemic norms. By year’s end, nationwide inventory levels are expected to remain roughly 12% below pre-2020 averages, an improvement from a 19% gap in 2025 and nearly 30% in 2024.

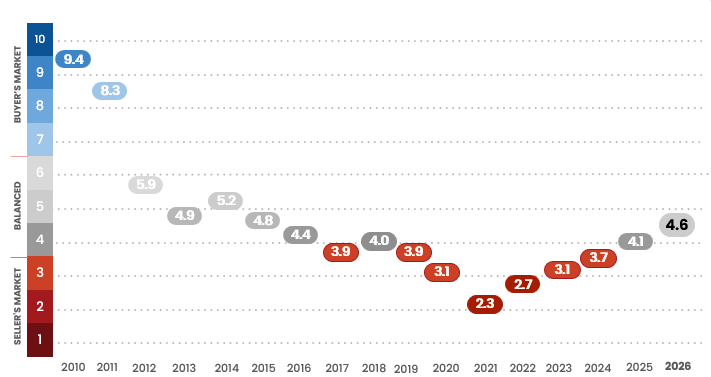
The national housing market will remain in balanced territory in 2026, averaging 4.6 months of supply across the year. Even so, momentum in the housing market is expected to tilt toward buyers as a more substantial growth in the number of homes for sale than homes sold shifts the balance of supply and demand. Housing affordability will remain a stumbling block for many, especially younger and first-time buyers, but negotiating power is expected to improve.

National Rent Softening Creates Mobility Opportunities Concentrated in the South and West

Renters are likely to see continued relief from declining rents in 2026, as a robust multifamily construction pipeline adds to rental supply and helps drive rents down. With more new units entering the market, vacancy rates are expected to approach—or even exceed—the long-term average of 7.2% observed between 2013 and 2019 by the end of 2026.

With rents declining for over two years and trends expected to continue in 2026, renter mobility is set to rise as more renters seek affordable housing or upgrades. Renters can find opportunities in markets such as Las Vegas, NV, Atlanta, GA, and Austin, TX, which have experienced the largest price drops from their peaks. At the same time, cross-market rental demand is expected to remain strong in metros like Raleigh, NC, and Richmond, VA, both emerging as top destinations for recent college graduates seeking affordability and career opportunities, as well as in Nashville, TN, which ranks among the nation’s top rental markets.

However, regional trends are expected to be a factor in the rental market in 2026. For renters living in expensive, high-density markets such as New York City, elevated rents will continue to pose significant affordability challenges. Even with rent freezes citywide—a policy preferred by Mayor-elect Zohran Mamdani—and sustained income growth, it would take decades—not years—for rents in New York City to become truly affordable.

New-Construction Trends

New-home construction has faced headwinds in 2025, from new tariffs on lumber and home finishings to a pullback in buyer demand resulting from high mortgage rates and low consumer sentiment. Builders have responded by pulling back on permitting and starting new projects at the same time that they push to sell completed inventory by offering incentives to buyers like mortgage rate buydowns and cash at closing. 

New construction has emerged as an affordable alternative to resale homes, with the price per square foot of new builds actually falling below that of existing homes. With the number of newly built homes for sale near an all-time high, builders are motivated sellers—and they provide healthy competition to sellers in the resale market. The inventory of existing homes for sale is lacking low-priced, entry-level options in many markets, so builders are likely to continue to fill that gap, offering smaller and more affordable homes such as townhomes and rowhomes, which have been growing in popularity.

The Economy Continues To Grow Even as It Shows Strains From a Period of Rapid Adjustment

Nominal economic growth in 2025 slowed modestly as the economy weathered sizable changes to trade, immigration, and tax policy. The slowdown moved real, after-inflation economic growth back to trend from a period of above-trend growth.  A similar on-trend economic performance is expected in 2026. 

Inflation, which has been a thorn in the economy’s side for nearly a half-decade, reached a significant low point in spring—headline inflation hit 2.3%, per the consumer price index. This progress wasn’t sustained, however, and inflation picked back up as new tariffs affected the costs of goods, a trend we expect to see in 2026. 

As economists debate the degree to which the Fed needs to respond or look through these price shifts, wages have continued to outpace inflation, creating real additional spending power for consumers. This has enabled household budgets to continue to catch up from the recent inflation-driven squeeze. 

But a softening jobs market driven by companies paring back hiring and in some cases shrinking their workforce as they plan to right-size in the face of expanding AI capabilities and investment has put a question mark on whether wage growth will continue with the same strength. 

Our outlook for 2026 expects median household income growth of more than 3.6%, which is just expected to exceed inflation, as it edges back up past 3%. Unemployment, which was at 4.3% in August, is expected to climb further, but not exceed 5% in 2026. In aggregate, consumers look to be in good shape, but lower-income and younger individuals may be more vulnerable as the labor market cools.

But Economic and Policy Risks Abound

The U.S. economy has weathered notable challenges in 2025, and several risks could cloud the 2026 outlook. Policy uncertainty around fiscal and trade measures may influence both inflation and consumer confidence. While the federal government has reopened, the recent shutdown caused some permanent economic loss, and the temporary nature of the continuing resolution means fiscal risk looms again at the end of January

The possibility of a Federal Reserve policy misstep—either remaining too tight or easing prematurely—remains a key concern. Further, the Fed will experience a leadership transition as Jerome Powell’s chairmanship ends on May 15, 2026. A successor has yet to be named, although several candidates have been publicly discussed. The chair plays a strong role as the lead public voice of the Federal Open Market Committee, the body that makes monetary policy decisions, but the chair is also just 1 vote of 12, so the role’s impact on monetary policy is more indirect and will vary depending on the characteristics of the person who fills the role.  

A softening labor market poses another risk: If job losses accelerate or wage growth stalls, consumer spending could weaken, potentially dampening both housing demand and economic growth. Additionally, inflation could fluctuate depending on how tariffs, energy costs, and global supply conditions evolve.

While a full-blown recession is not the base case, the economy is in a period of accelerated adjustment where a “misshift” in policy or sentiment could cause a temporary setback that would have implications for the housing market.

Housing Perspectives

What will the market be like for homebuyers, especially first-time homebuyers?

Homebuyers will see modest improvement in their bargaining power in 2026, as affordability and inventory inch higher, building on the gains they saw in 2025. Although the national housing market will remain in balanced territory, there will be substantial regional variation. Already in 2025, at least seven major housing markets have crossed into buyer-friendly territory, and that list is likely to grow in 2026. This doesn’t mean that the housing market will be “easy” for buyers, but we do expect to see more sales in 2026, a sign that more buyers will be able to successfully navigate the market’s challenges.

How can homebuyers prepare?

As affordability remains a top concern, buyers want to be financially ready to find success in the 2026 housing market, and that means not only knowing your budget numbers but also understanding the market norms and cheat codes. Where will extra financial effort pay off, and which goals are not worth pursuing? 

Recent data shows that down payments have leveled off as some of the market competitiveness releases pressure to compete here. Buyers don’t need a record-high amount of cash to successfully buy a home, but the down payment size can still affect monthly housing costs. A larger down payment can reduce monthly costs by lowering the amount borrowed and also the mortgage rate buyers may be able to secure. Research shows that even as the typical homebuyer does not get all the way to a 20% down payment, those who are close to that threshold will see a big drop in their mortgage rate if they meet the 20% target

New construction is another option to consider, especially for buyers in the South and West, where builders have been particularly active. As builders see the number of for-sale homes climb, they are trying to compete and are increasingly offering incentives to help buyers get to the closing table. A recent Realtor.com® study showed that mortgage rate buydowns—when a builder offers special, below-market rate financing—are among the most commonly offered buyer incentives

Buyers in the Northeast and Midwest may find new construction harder to come by since it generally comprises a smaller share of for-sale listings in these regions. However, metros in these regions tend to have more abundant fixer-uppers. Buying a home that needs work isn’t without challenges, but it may be a move to consider for those with skills and the readiness for a project.

What will the market be like for home sellers?

In 2025, sellers faced a year of rising home inventory and sluggish sales. These trends combined to nudge the housing market away from a seller’s market to a balanced market for the first time in nine years, as we anticipated in our 2025 housing forecast. This momentum is likely to continue in 2026, when sellers will face a market moving even further into balanced territory.  

Sellers who definitely want to sell will want to pay attention to the competition when setting a price, and they may need to be prepared to adjust expectations based on market feedback. The degree of adjustment will depend on their geography and their price point. Recent data shows that price cuts are somewhat more common among lower-priced homes, and comparatively rare among homes priced above $1 million.

Sellers who list, but are inflexible on price or other terms, may not find a buyer willing to meet them. An increasing number of sellers in 2025 chose to delist and walk away from the market, and this trend could continue in 2026. Fortunately, the lengthy average tenure among today’s homeowners suggests that many are in a position to walk away with good money if they were to choose to sell.  

One source of demand that has remained relatively steady comes from investors who comprise just over 1 in 10 homebuyers in the most recent quarter nationwide, and up to twice that share in some metros.

What will the market be like for renters?

In 2026, rental supply is expected to continue outpacing demand, driving down rents and increasing renter mobility—especially cross-market rental demand. While more new multifamily units are anticipated to enter the market, a slowdown in permitting activity—potentially linked to tariffs on construction materials—could pose headwinds to future rental supply growth and exert upward pressure on rents.

Nevertheless, rental affordability is expected to continue improving in 2026making renting a consistently cost-effective option compared with buying in the short term across most markets. Young adult renters, who lack access to historically high home equity to purchase a home, could take advantage of this trend by searching for more budget-friendly options and saving money in the process.

When evaluating housing options, it’s important to consider both market trends and how long you plan to stay in your next home. The Realtor.com Rent vs. Buy Calculator helps individuals and families compare the costs and benefits of renting versus buying, showing how long it may take before buying becomes the more financially advantageous choice. By providing tailored insights, the tool helps users weigh current and future trade-offs.

Local Market Predictions

All real estate is local, and while the national trends are instructive, what matters most is what’s expected in your local market. See below for a list of the largest metro sales and price growth predictions in 2026.

Metro2026 Sales Growth % YoY2026 Price Growth % YoY
Akron, Ohio0.6%5.1%
Albany-Schenectady-Troy, N.Y.-4.1%7.5%
Albuquerque, N.M.-4.3%3.5%
Allentown-Bethlehem-Easton, Pa.-N.J.-13.6%5.9%
Atlanta-Sandy Springs-Roswell, Ga.-3.5%-0.1%
Augusta-Richmond County, Ga.-S.C.-4.9%1.3%
Austin-Round Rock, Texas-7.0%2.0%
Bakersfield, Calif.1.8%4.3%
Baltimore-Columbia-Towson, Md.-2.6%8.3%
Baton Rouge, La.7.1%2.2%
Birmingham-Hoover, Ala.0.0%6.2%
Boise City, Idaho3.7%-0.8%
Boston-Cambridge-Newton, Mass.-N.H.4.7%2.6%
Bridgeport-Stamford-Norwalk, Conn.1.0%6.9%
Buffalo-Cheektowaga-Niagara Falls, N.Y.-0.2%1.9%
Cape Coral-Fort Myers, Fla.-0.8%-10.2%
Charleston-North Charleston, S.C.-7.6%3.3%
Charlotte-Concord-Gastonia, N.C.-S.C.-2.4%1.1%
Chattanooga, Tenn.-Ga.0.4%5.6%
Chicago-Naperville-Elgin, Ill.-Ind.-Wis.-2.3%4.4%
Cincinnati, Ohio-Ky.-Ind.-3.2%3.1%
Cleveland-Elyria, Ohio-2.0%6.3%
Colorado Springs, Colo.-4.2%-0.4%
Columbia, S.C.0.3%7.2%
Columbus, Ohio-2.1%4.0%
Dallas-Fort Worth-Arlington, Texas-5.4%1.8%
Dayton, Ohio-1.3%6.3%
Deltona-Daytona Beach-Ormond Beach, FL-0.5%-3.6%
Denver-Aurora-Lakewood, Colo.-2.9%-3.4%
Des Moines-West Des Moines, Iowa-4.7%-0.9%
Detroit-Warren-Dearborn, Mich-1.2%4.2%
Durham-Chapel Hill, N.C.1.0%2.9%
El Paso, Texas-7.0%2.8%
Fayetteville-Springdale-Rogers, AR0.5%6.3%
Fresno, Calif.2.1%2.8%
Grand Rapids-Wyoming, Mich6.9%3.7%
Greensboro-High Point, N.C.-10.9%4.4%
Greenville-Anderson-Mauldin, S.C.-8.1%3.1%
Harrisburg-Carlisle, Pa.1.0%4.0%
Hartford-West Hartford-East Hartford, Conn.7.6%9.5%
Houston-The Woodlands-Sugar Land, Texas-0.6%0.4%
Indianapolis-Carmel-Anderson, Ind.-6.4%6.6%
Jackson, MS-0.4%4.6%
Jacksonville, Fla.-6.9%-1.4%
Kansas City, Mo.-Kan.1.7%5.4%
Kiryas Joel-Poughkeepsie-Newburgh, NY-10.8%0.7%
Knoxville, Tenn.-6.4%3.9%
Lakeland-Winter Haven, Fla.1.5%-0.2%
Las Vegas-Henderson-Paradise, Nev.-2.5%0.6%
Little Rock-North Little Rock-Conway, Ark.3.9%4.6%
Los Angeles-Long Beach-Anaheim, Calif.1.8%1.8%
Louisville/Jefferson County, Ky.-Ind.5.1%3.5%
Madison, Wis.2.7%2.2%
McAllen-Edinburg-Mission, Texas3.3%4.6%
Memphis, Tenn.-Miss.-Ark.-7.7%1.8%
Miami-Fort Lauderdale-West Palm Beach, Fla.-7.1%1.1%
Milwaukee-Waukesha-West Allis, Wis.3.5%7.0%
Minneapolis-St. Paul-Bloomington, Minn.-Wis.3.8%1.2%
Nashville-Davidson–Murfreesboro–Franklin, Tenn.-3.5%0.5%
New Haven-Milford, Conn.2.3%7.7%
New Orleans-Metairie, La.-4.4%5.8%
New York-Newark-Jersey City, N.Y.-N.J.-Pa.-4.4%5.2%
North Port-Sarasota-Bradenton, Fla.0.8%-8.9%
Oklahoma City, Okla.-6.1%1.1%
Omaha-Council Bluffs, Neb.-Iowa3.1%-0.4%
Orlando-Kissimmee-Sanford, Fla.-4.7%-1.6%
Oxnard-Thousand Oaks-Ventura, Calif.2.5%0.9%
Palm Bay-Melbourne-Titusville, Fla.1.6%-1.0%
Philadelphia-Camden-Wilmington, Pa.-N.J.-Del.-Md.-5.1%5.7%
Phoenix-Mesa-Scottsdale, Ariz.4.9%-2.3%
Pittsburgh, Pa.4.0%5.7%
Portland-South Portland, Maine4.7%4.6%
Portland-Vancouver-Hillsboro, Ore.-Wash.-2.5%0.2%
Providence-Warwick, R.I.-Mass.7.1%4.1%
Raleigh, N.C.-4.4%-3.7%
Richmond, Va.3.6%6.9%
Riverside-San Bernardino-Ontario, Calif.-1.4%1.5%
Rochester, N.Y.5.3%10.3%
Sacramento–Roseville–Arden-Arcade, Calif.1.5%-3.3%
St. Louis, Mo.-Ill.2.2%3.1%
Salt Lake City, Utah4.2%1.7%
San Antonio-New Braunfels, Texas0.4%0.2%
San Diego-Carlsbad, Calif.2.3%0.7%
San Francisco-Oakland-Hayward, Calif.2.5%-2.5%
San Jose-Sunnyvale-Santa Clara, Calif.0.0%0.7%
Scranton–Wilkes-Barre–Hazleton, Pa.-6.2%10.9%
Seattle-Tacoma-Bellevue, Wash.4.2%-0.3%
Spokane-Spokane Valley, Wash.8.1%-3.5%
Stockton-Lodi, Calif.-5.7%-4.1%
Syracuse, N.Y.-5.7%12.4%
Tampa-St. Petersburg-Clearwater, Fla.-3.1%-3.6%
Toledo, Ohio-1.2%13.1%
Tucson, Ariz.-1.5%-0.5%
Tulsa, Okla.2.2%2.3%
Urban Honolulu, Hawaii2.3%2.6%
Virginia Beach-Norfolk-Newport News, Va.-N.C.-3.6%6.6%
Washington-Arlington-Alexandria, DC-Va.-Md.-W. Va.-1.3%5.1%
Wichita, Kan.-3.2%3.1%
Winston-Salem, N.C.-0.2%7.7%
Worcester, Mass.-Conn.12.6%2.4%

Methodology

The Realtor.com model-based forecast uses data on the housing market and overall economy to estimate values for these variables for the year ahead. The forecast result is a projection for annual total home sales increase (total 2026 existing-home sales vs. 2025) and annual median home sales price increase (2026 median existing-home sales price vs. 2025).

Got Questions? The Caton Team is here to help.

Cell| Sabrina 650.799.4333 | Susan 650.796.0654 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team from our TESTIMONIALS.

Effective. Efficient. Responsive. The Caton Team 🏡  

How Can The Caton Team Help You?

TESTIMONIALS | HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TRUST AGREEMENTS | HEALTH CARE DIRECTIVESTESTIMONIALS

Get exclusive inside access when you follow us on Facebook & Instagram

TESTIMONIALS | HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TRUST AGREEMENTS | HEALTH CARE DIRECTIVESTESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or some guidance – we are here for you. Contact us at your convenience – we are but a call, text, or click away!

The Caton Team believes, in order to be successful in the San Francisco | Peninsula | Bay Area | Silicon Valley Real Estate Market, we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Cell | Sabrina 650.799.4333 | Susan 650.796.0654 | EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

Website | The Caton Team Testimonials | Our Blog – The Real Estate Beat | Search for Homes | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina | Photography | Photography Blog 

Berkshire Hathaway HomeServices – Drysdale Properties, Redwood City Ca.

DRE # | Sabrina 01413526 | Susan 01238225 | Team 70000218 | Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

The Stats are In… Market Snapshot for November 2025

Hello Caton Team Friends,

The stats are in for November 2025. We are seeing the normal pre-holiday activity or lack there of. Affordability is still an issue here, the interest rates haven’t moved enough to make any headway. The luxury end is holding up – but our more affordable price points are feeling it. With the cost of living on the rise I am curious what 2026 will bring. What are your thoughts?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home.


For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.


If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at info@TheCatonTeam.com.

Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 40 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.