Portable Mortgages Sound Great. The Math Is Messier – Shared article

Thank you for tuning in – I am sharing this article featured on my friends blog – lender Christian Carr – visit his lending blog here.

The MOVE Act, introduced by Representative Tom Kean Jr., aims to address homeowners’ frustrations about being locked into low-rate mortgages. However, it only proposes future portable mortgages that won’t retroactively help current borrowers. While this could assist mobility, it doesn’t eliminate financing gaps or selling costs for new homes.

Infographic showing a homeowner selling a $1.2 million home with a $500,000 mortgage at 3%, using roughly $630,000 to $640,000 in net equity toward a $1.6 million replacement home, and still needing about $460,000 to $470,000 in new financing.
A portable mortgage may preserve a low existing rate, but it does not eliminate the financing gap on a more expensive replacement home. Selling costs reduce usable equity, and the remaining balance may need to be financed at a higher rate.
There is a reason H.R. 10028 is getting attention.
It speaks directly to one of the biggest frustrations in housing today: homeowners who are effectively locked into their current homes because the mortgage they already have is far more attractive than the mortgage they would have to take on if they moved.
It’s a real problem affecting household mobility, inventory turnover, and the willingness of would-be move-up buyers to make a change even when life is pushing them in that direction.
So when Representative Tom Kean Jr. introduced H.R. 10028, the MOVE Act, the headline was naturally compelling. The pitch is simple enough for a cocktail conversation: what if a homeowner could take their mortgage with them when they move?
At first glance, that sounds like a breakthrough. If someone has a $500,000 mortgage at 3.00%, why should they be forced to give that up just because they want to buy a different house? Why not let them transfer that loan balance, rate, and remaining term to the next property?
It is a smart political message because it sounds like common sense. It also happens to leave out some very important details.
The first and most important issue is that the bill does not appear to do what many casual listeners will assume it does. H.R. 10028 does not say that every existing low-rate mortgage suddenly becomes portable. It directs Fannie Mae and Freddie Mac to begin purchasing and securitizing conventional mortgages that are designed to allow portability. That is a very different idea.
In plain English, this looks much more like a proposal for a future mortgage product than a retroactive rescue plan for today’s 3% borrowers.
That distinction matters.
A homeowner hearing the phrase “transfer your existing mortgage rate, term, and balance to a new property” could easily assume Congress is trying to let them keep the mortgage they already have. But the economics of the mortgage market make that far more complicated. Existing low-rate mortgages are not simply sitting on a bank’s balance sheet waiting to be modified out of generosity. In most cases, those loans have already been sold into the secondary market and are owned, directly or indirectly, by investors who purchased cash flows based on a certain set of assumptions. One of those assumptions is that when the borrower sells the home, the loan generally gets paid off.
Portable mortgages change that.
That is the overlooked angle here. Portability is not just a consumer perk. It is a borrower option, and options have value. If a borrower can keep a below-market mortgage even after selling the home, the investor loses one of the most common paths to getting principal returned and redeployed at current yields. If market rates are 6.75% or 7.00% and the investor is stuck collecting 3.00% for years longer than expected, that is not a small issue. It is the entire pricing issue.
Which is why portability is not free.
Analysts looking at portable mortgages have already suggested that borrowers would likely pay for that flexibility upfront, probably in the form of a somewhat higher interest rate at origination. In other words, if portable mortgages become a standard future product, the borrower may be buying the right to preserve that mortgage later. Useful, yes. Free, no.
Even that, however, is only the first layer of the story.
The second layer is the one I think gets missed almost entirely in the public conversation: portability helps only on the portion of the new purchase that can be covered by the old mortgage balance. It does not solve the rest of the transaction.
Let’s walk through a realistic example.
Suppose a homeowner sells a current home for $1.2 million. They have an existing first mortgage of $500,000 at 3.00%. On paper, that leaves about $700,000 of gross equity. But nobody gets to move “gross equity” into the next house. Selling costs come first. Between commissions, escrow, title, transfer charges, and other transaction costs, it would not be hard to see $60,000 to $70,000 disappear before the homeowner ever touches the proceeds.
So now the net equity available is closer to $630,000 to $640,000.
Assume that homeowner then buys a new home for $1.6 million. If the $500,000 mortgage is portable, great. That old loan balance moves over. The homeowner also applies roughly $630,000 to $640,000 in net proceeds from the sale. But the new purchase price is still $1.6 million.
The gap does not vanish.
At that point, the borrower still needs roughly $460,000 to $470,000 in additional financing.
That is where the clean political story starts to get messy.
The homeowner is no longer financing the new purchase at 3.00%. They are financing part of it at 3.00% and part of it at whatever the market demands for the new money. And because that new money may need to come in as a second lien or other subordinate structure, the rate on that gap financing may be meaningfully higher than the rate on a standard first mortgage.
Now we are talking about the actual capital stack, not the campaign version.
Let’s use $465,000 as the new financing amount. If that money potentially carries an 8.10% rate (or higher), which is not unreasonable for higher-risk secondary financing, the borrower’s balance-weighted blended rate would look attractive on paper. You would have $500,000 at 3.00% and $465,000 at 8.10%, producing a rough blended rate of about 5.46%.
That sounds pretty good relative to financing the full amount at today’s first-mortgage rates.
But rate is only part of the story. Payment matters more.
The old portable mortgage would not magically become a fresh 30-year loan. If that mortgage has 24 years remaining, then that is likely the remaining term coming into the new property. If the additional $465,000 is financed separately at 8.10%, the amortization period on that second piece becomes crucial.
If the $500,000 portable first has 24 years remaining at 3.00%, the principal and interest payment is about $2,438 per month. If the $465,000 gap financing is set up at 8.10% over 20 years, the principal and interest payment is about $3,918 per month. Combined, the borrower is at roughly $6,356 per month in principal and interest.
Now compare that with a single new $965,000 mortgage at 6.75% over 30 years. That payment would be roughly $6,259 per month.
Read that again. The borrower “kept the 3% mortgage,” and the monthly payment still comes out slightly higher in this structure than simply taking one new 30-year first mortgage at current rates.
That is not because portability has no value. It absolutely can. It is because the value of the portable piece can be weakened or even overwhelmed by the structure, pricing, and amortization of the gap financing.
And if the second piece is amortized more gently over 30 years instead of 20, the payment improves. In that case, the $465,000 loan at 8.10% would be about $3,444 per month, bringing the combined payment to around $5,882. Now portability is helping more clearly. But even then, the borrower still has to manage a more complex financing structure, potentially with two liens, two different terms, and the complications that come with that.
This is the part of the conversation that deserves more attention.
Portable mortgages are easy to understand at the slogan level. They are much harder to evaluate in an actual transaction.
Who underwrites the gap financing? Does it come in behind the portable first as a true second lien? What does that do to combined loan-to-value limits? How is the borrower requalified? What happens if the new property is a condo with its own approval issues? What happens if values soften and the subordinate lender becomes more conservative? What if the second lien is adjustable, or requires a shorter payoff horizon? What if the borrower later wants to refinance one piece but not the other?
Those are not side questions. Those are the deal.
That is why I think the real story around H.R. 10028 is not that portable mortgages are a bad idea. In concept, they are actually a very interesting idea. They recognize that a mortgage is not just debt; under the right circumstances, it can also be a valuable financial asset. A homeowner sitting on a 3.00% loan in a 7.00% world clearly owns something economically valuable.
The problem is that Washington has a habit of selling the headline benefit of a financing innovation while understating the cost, complexity, and tradeoffs underneath it.
We have seen versions of this before. A 40-year mortgage can be pitched as a lower-payment solution, but extending duration changes the economics of the loan and the way investors price the risk. The payment may go down relative to a shorter term, but the borrower pays for longer, builds equity more slowly, and can end up carrying more interest over time. The wrapper changes. The economic realities do not disappear.
Portable mortgages raise a similar issue. If you give borrowers a valuable option, someone has to absorb that cost. If you preserve only part of a low-rate financing structure, someone still has to fund the rest. And when that additional capital sits in a riskier position, it usually commands a higher rate.
That is the story.
The MOVE Act, authored by Representative Tom Kean Jr., is politically sharp because it taps into a genuine frustration in the housing market. Homeowners feel trapped by the success of their old financing. They know their current mortgage is too good to casually surrender. Any policy proposal that seems to honor that reality is going to attract attention.
But attention and execution are two different things.
If portable mortgages eventually become a viable conventional product, they may help mobility for some borrowers. They may improve transaction flow. They may allow some homeowners to preserve a meaningful portion of their financing advantage when they move. That would be a real benefit.
What they will not do is magically turn a move-up purchase into a 3.00% financing event. They will not erase selling costs. They will not eliminate the need for new capital. And they will not prevent the market from pricing the risk associated with that structure.
The cleanest way to say it is this: portability may preserve the cheap money you already have, but it does not make the next house cheap.
For borrowers, advisors, and anyone trying to think clearly about housing policy, that is the conversation worth having. Not whether portable mortgages sound good. They do. The better question is whether the full financing stack still makes sense once the math, structure, and incentives are laid out honestly.
That is where the real answer lives.

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 45 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

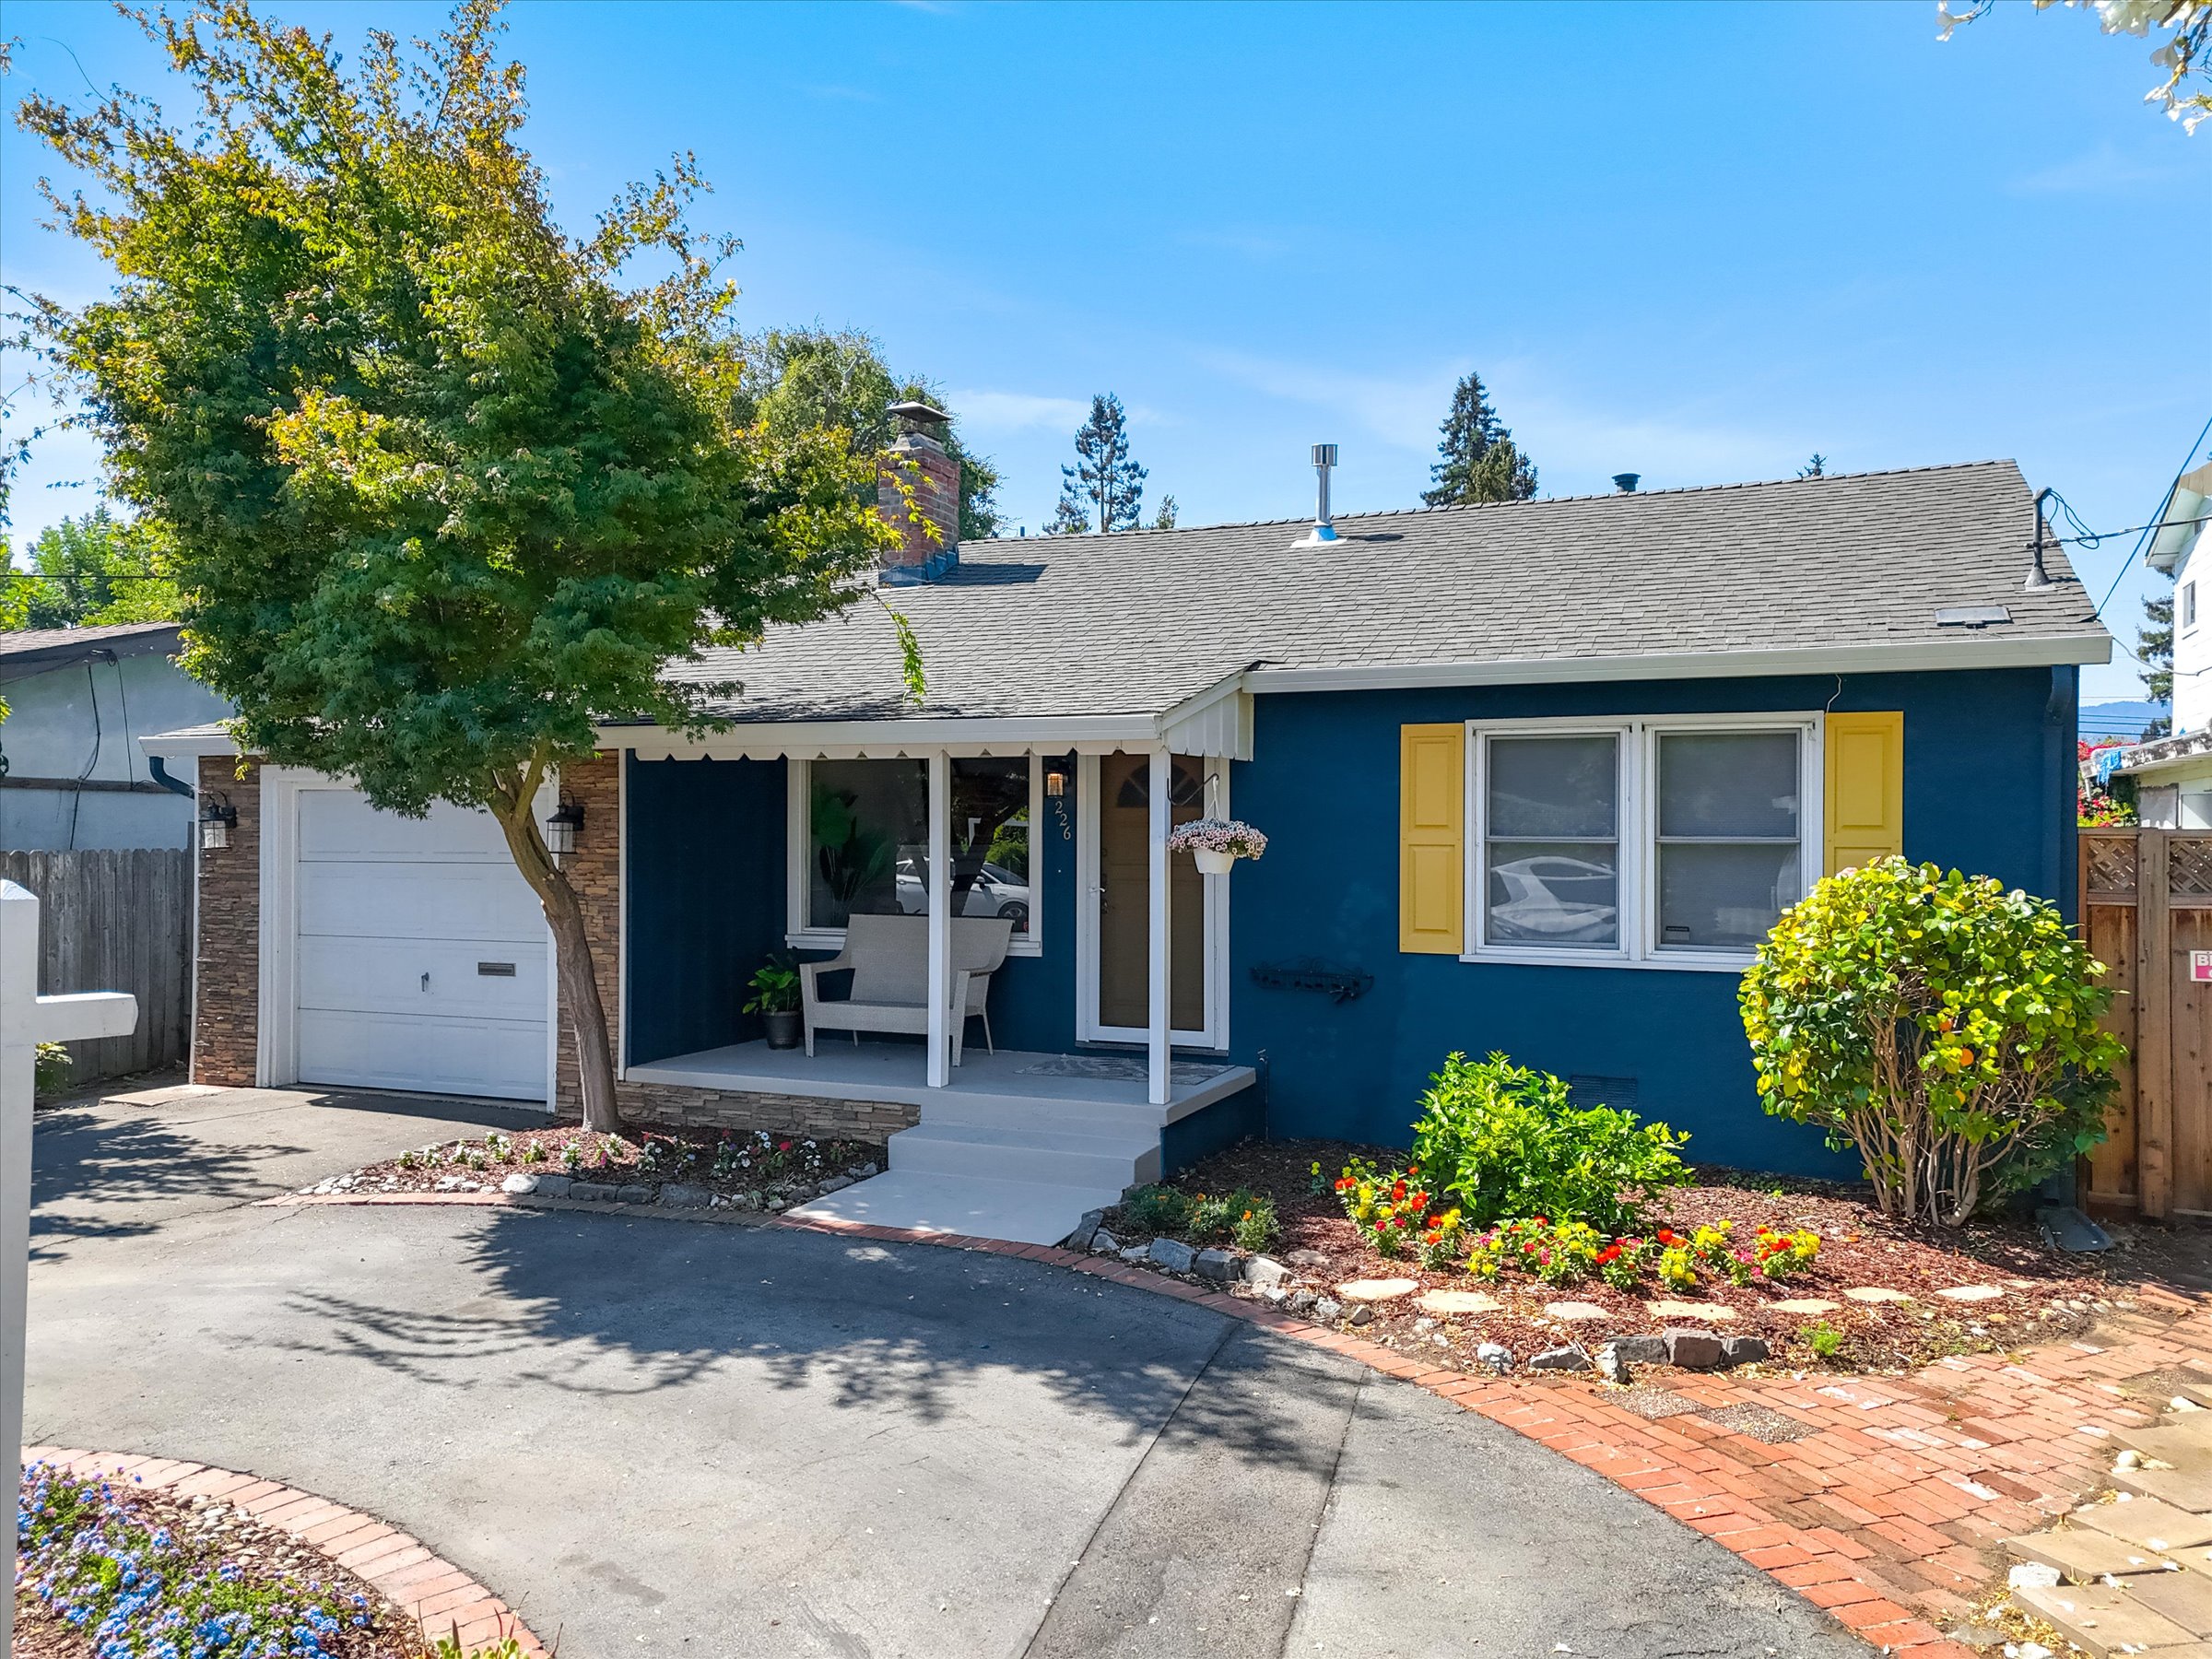
RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

Why Big Banks Are Pouring Billions Into Reviving the Housing Market – Shared Article By Tristan Navera

Thank you for tuning in – sharing this article – I read here.

JPMorgan Chase, the nation’s largest bank, is a name typically attached to big numbers. But a new plan to invest $750 billion into housing market initiatives in the next decade stands out.

The bank announced this summer it would deploy $750 billion into the housing market through 2035. Its “American Dream Initiative” aims to build or preserve 1 million affordable housing units and help 500,000 customers purchase homes, 200,000 of them for the first time.

It’s not alone. Wells Fargo, Citibank, and Bank of America—which, with JPMorgan, comprise the “big four” of American finance—have each announced major housing initiatives. And, like the $5 trillion JPMorgan Chase, they’re directing tens of billions toward the problem.

The nationwide housing supply shortage, as well as rampant pessimism among young people, make the issue too big to ignore, says Sam Sheets, a strategy executive for Community & Affordable Lending at JPMorgan Chase.

“At the end of the day, it’s a function of supply and demand,” Sheets says. “Supply is the big issue—and supply of homes at the right price point.”

Housing has long been a major focus for banks. Bank of America, for instance, has provided $15 billion in loans and grants since 2019 to support down payments, closing costs, and affordable mortgage options for homebuyers. It partners with 300 housing counseling groups in the process.

But banks are now also expanding their support for efforts like zoning reform, building code changes, and new homebuilding in an effort to restore affordability to the housing market—and potentially expand the pool of mortgage borrowers, which has been shrinking lately.

“It’s driven by slower new construction but also just a lock-in effect, which has forced families to stay put when they would have moved and upsized,” Sheets says.

The business case for bank intervention

Reading between the lines, banks may be concerned about the decline in mortgage business in recent years.

The number of annual new mortgage accounts at large banks has hovered below 500,000 for the past three years, well below the million-plus levels typically seen in a single year before the pandemic, according to tracking from the Philadelphia Fed.

The sharp drop-off in big bank mortgages is due in part to increased competition from specialty lenders, but the main culprit may be the overall decline in homebuying activity since 2022.

Bernard Nossuli, COO at lending data company iEmergent, notes the mortgage business has been racked by the uncertain market, including high interest rates and limited signals from the Federal Reserve about when that might change.

Roughly 581,000 home purchase loans were originated from January through March 2026, down 19% from the previous quarter and a 12-year low. With many younger buyers priced out, and older buyers “locked in” to homes with low rates, supply-side solutions seem to be the easiest lever to pull right now.

But while those policies might seem straightforward, “the reality is a lot more complicated than that,” Nossuli says.

Large Bank Mortgage Originations Chart

Beyond mortgages

Obviously, banks have always played a major role in the housing market via the mortgages they provide. But as the nation confronts a major affordability crisis with complex causes and difficult solutions, banking leaders have sought a more proactive role.

The $49 trillion housing market has been the bedrock of Americans’ financial prosperity for generations. But the shortage of millions of homes, as well as millions of affordable rentals, has meant more Americans’ financial lives are being stifled because housing eats into their ability to save and invest.

At a Washington, DC, conference hosted by the Bipartisan Policy Center in June, Edward Skyler, head of Enterprise Services for Citi, said the private sector has roles to play around the edges.

“We need American ingenuity and entrepreneurship to help us build cheaper,” Skyler said. “We need to apply some of this great intellectual capacity and allocate some of that brain power to housing, because it is ripe for innovation.”

This year, Citi launched its “Blueprint for Housing Opportunity Initiative,” a $60 billion plan to support the preservation and construction of 250,000 homes. Last year, it financed $7 billion to support 30,000 units, and the new initiatives would double the pace, Skyler said.

Citi also committed $50 million to support housing nonprofits, including “seed funding” to support pre-development work like architecture and zoning studies on new housing projects. That support helps those companies prepare developments to turn dirt. Their role in their cities makes their housing pitches more likely to be successful, Skyler said.

“This is an issue that is really harming Americans across the country, and not just in the big cities,” he noted.

Banks push for policy change

In the case of JPMorgan, the bank has leaned into thought leadership. It has backed housing market analysis through a policy center that advocated for reducing regulatory barriers and encouraging manufactured housing innovation.

“We’re really trying to look at what levers, and particularly state and local levers, that can reduce the cost drivers of what it takes to build housing,” Olivia Barrow Strauss, vice president of Housing Policy at JPMorgan, recently told Realtor.com®.

And for Citi, policy advocacy is part of its plan, too. Its blueprint encourages lawmakers to consider changes to the Low Income Housing Tax Credit, a tool that helps finance affordable housing development. Allowing it to be transferrable would encourage more banks and other investors to put money behind the credit that developers can use, Skyler said.

“We’re seeing a lot of money left on the table,” he noted. “Our idea is simply to … try and create a market for them.”

The banks are also backing the private sector. Wells Fargo has awarded $53 million to back innovations in home construction and financing through its “Housing Affordability Breakthrough Challenge.” Its foundation has contributed $830 million toward housing efforts since 2019.

The initiatives aren’t just a philanthropic effort, either. Dennis Shea, co-leader of BPC’s Terwilliger Center for Housing Policy, says the housing shortage has major macroeconomic effects that limit labor mobility, productivity, and economics. That in turn limits bank customers and stifles growth of the broader private sector.

At Chase, Sheets says the bank is aggressively trying to grow its mortgage business. It originated $52.8 billion in mortgage volume in 2025, up from $40.8 billion in 2024, according to its most recent financial reporting.

The bank’s housing initiatives offer it “a more comprehensive view” for how it can positively influence housing supply, he says.

I read this here.

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 45 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

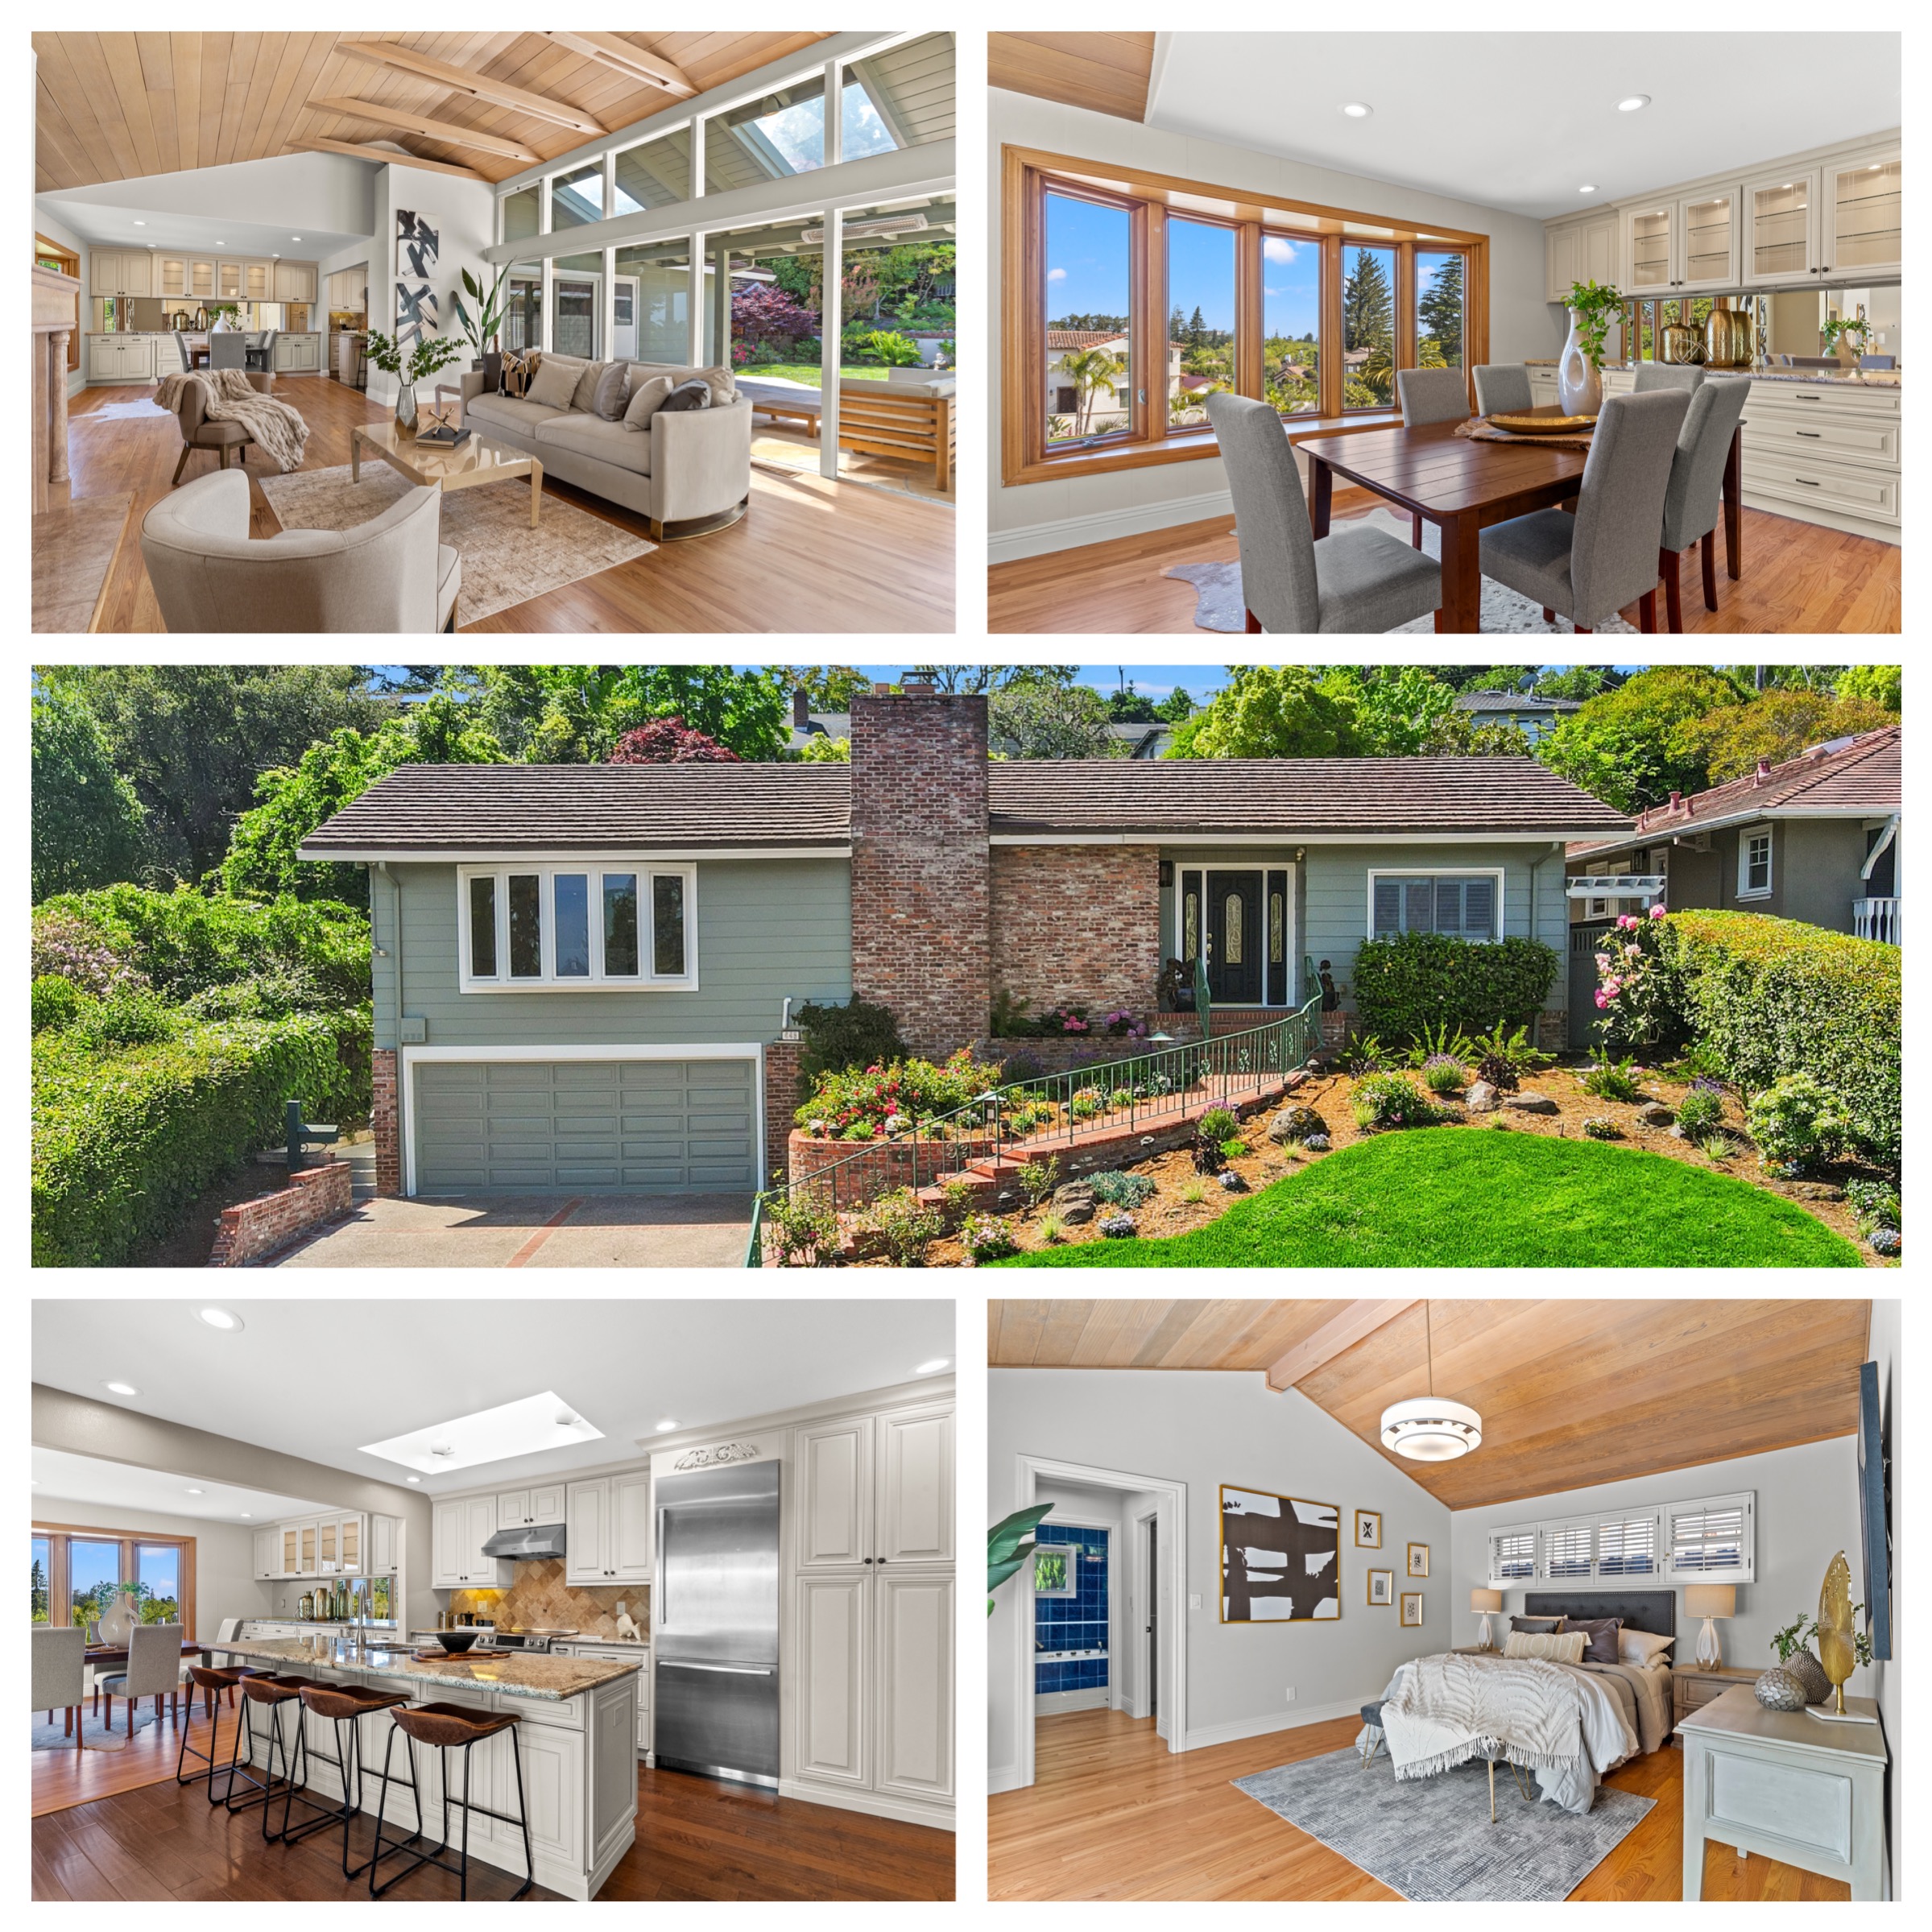
RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

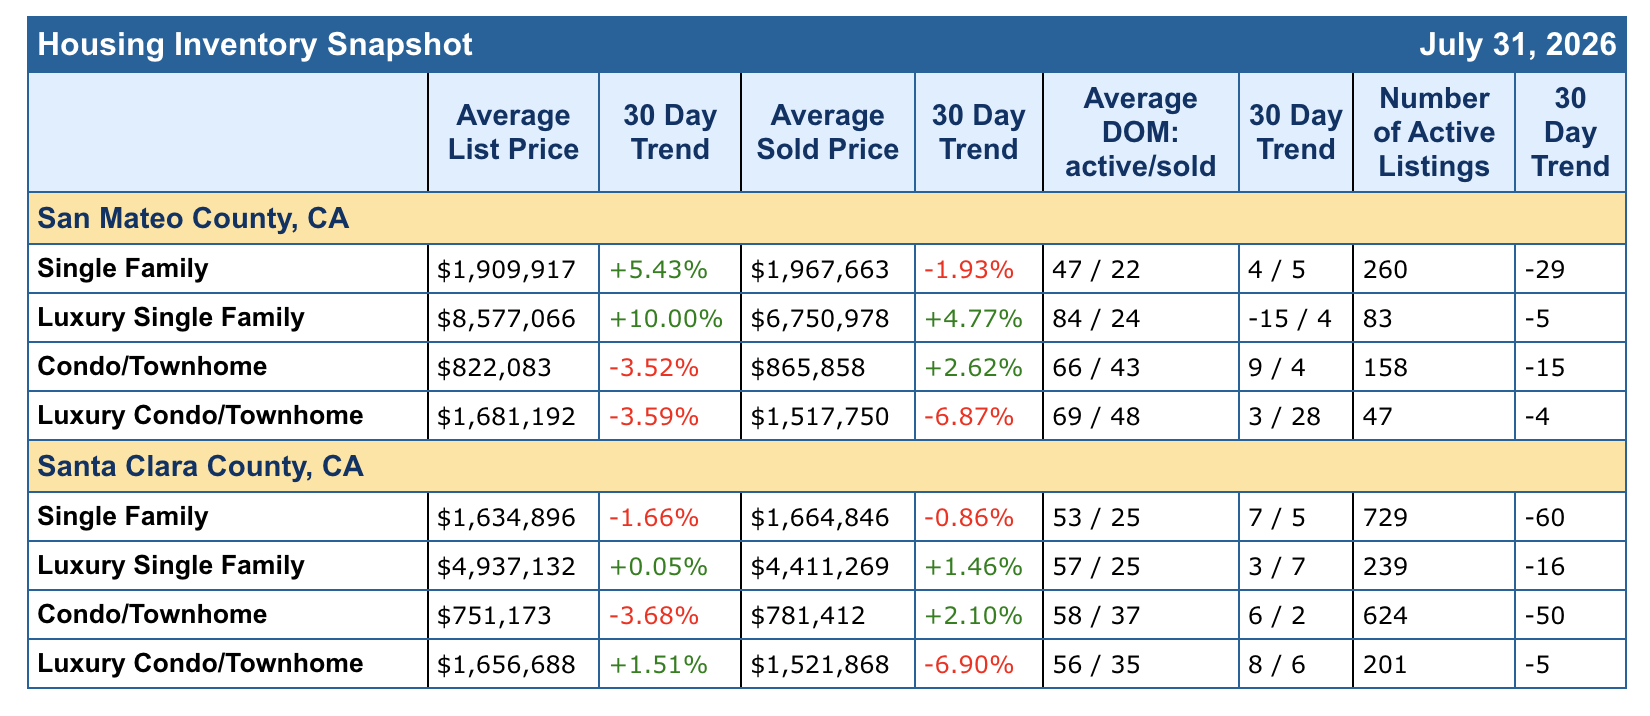
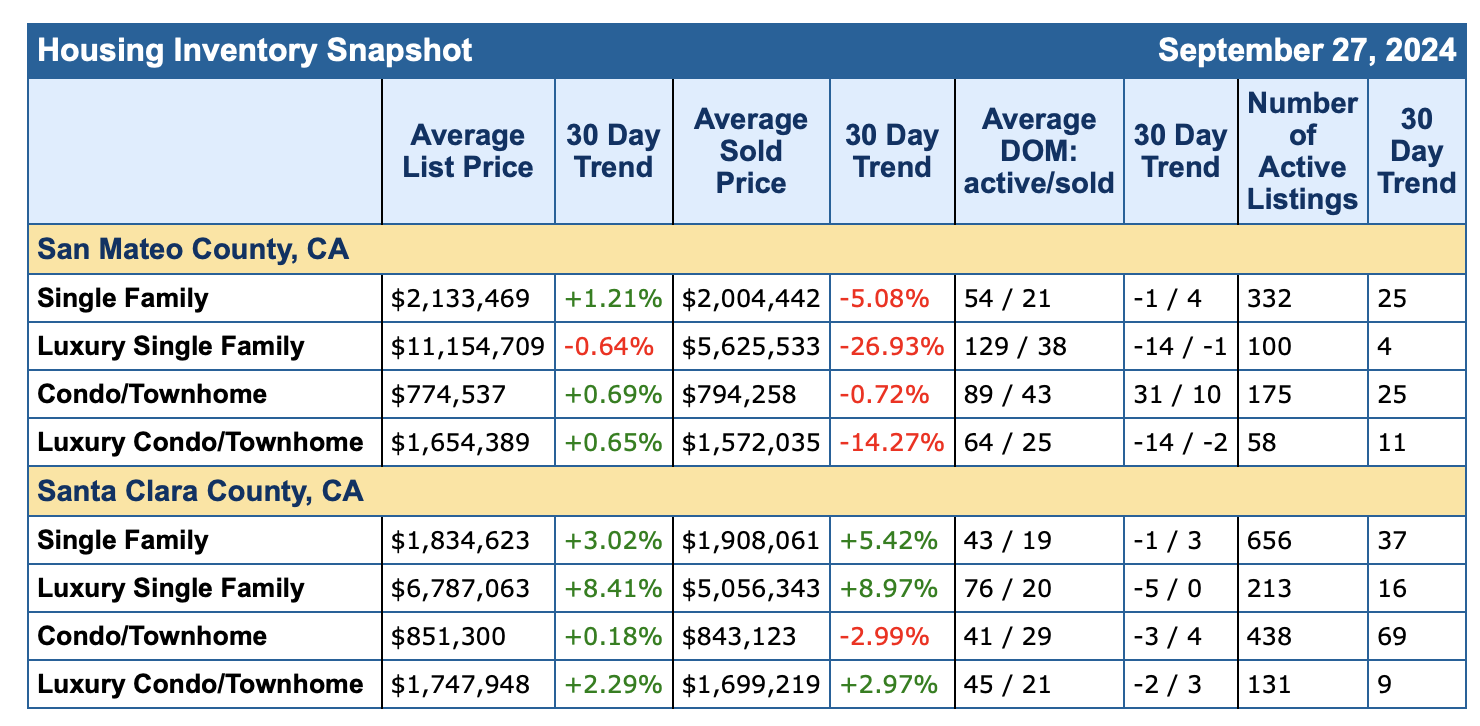
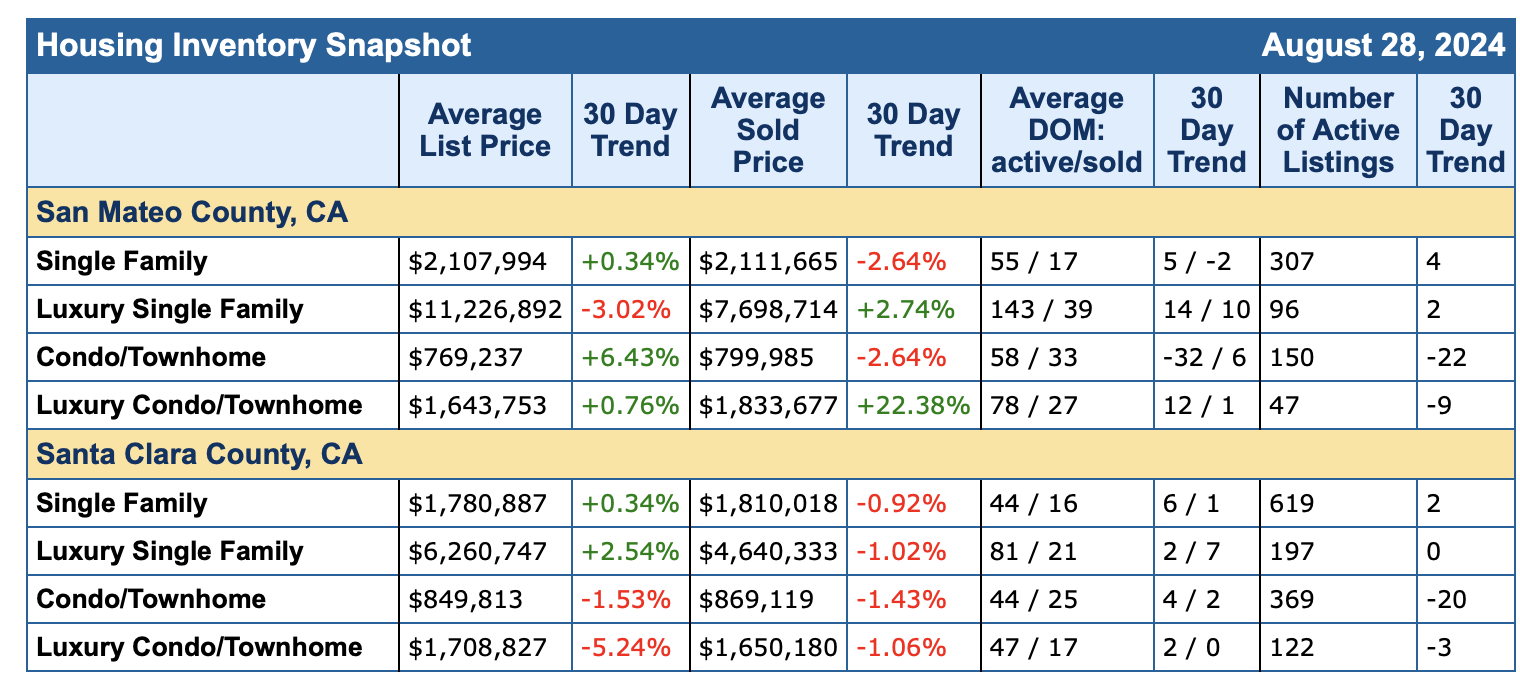
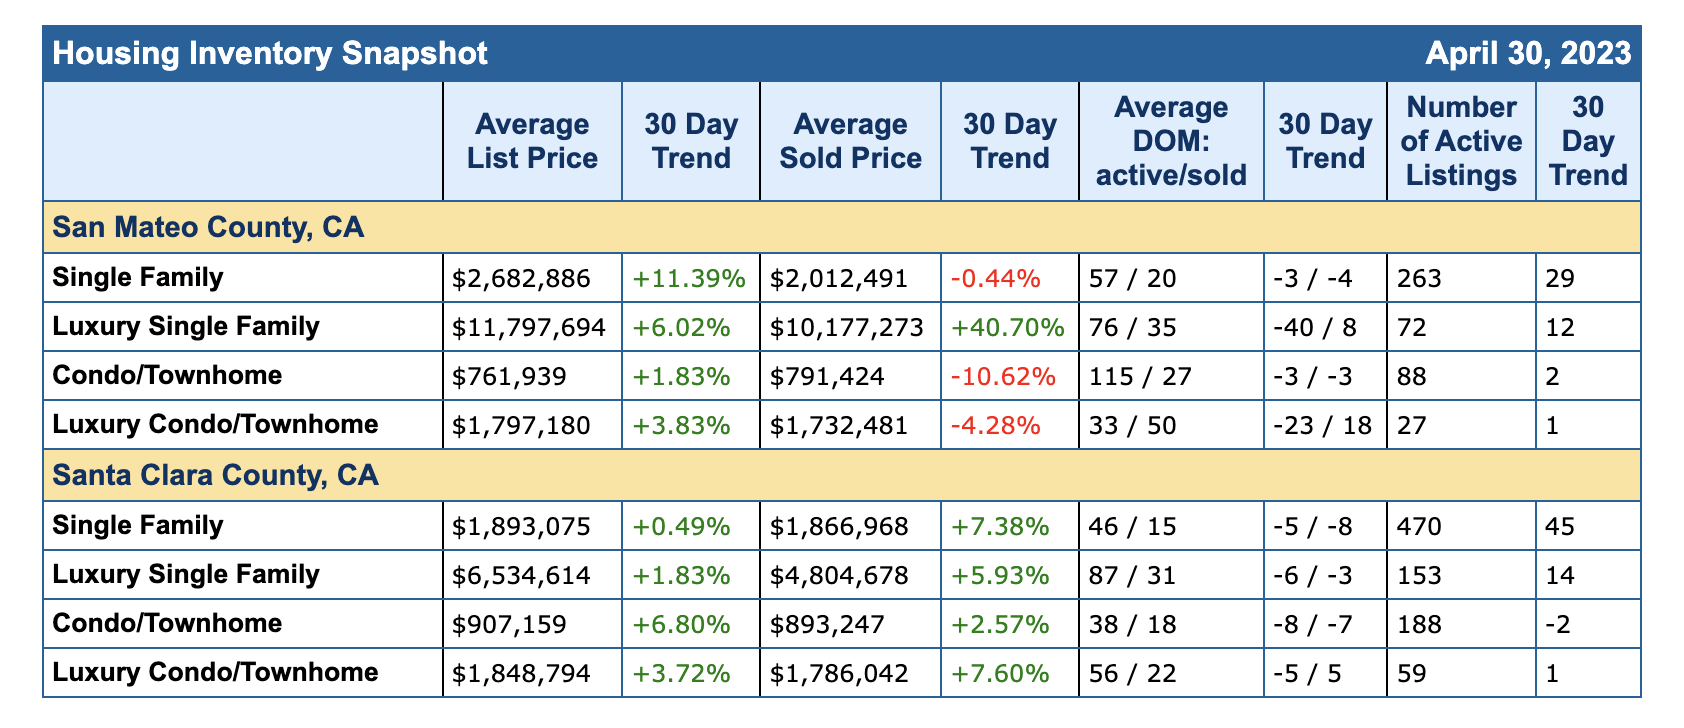
The Stats are In… Market Snapshot for July 2026

Hello Caton Team Readers,

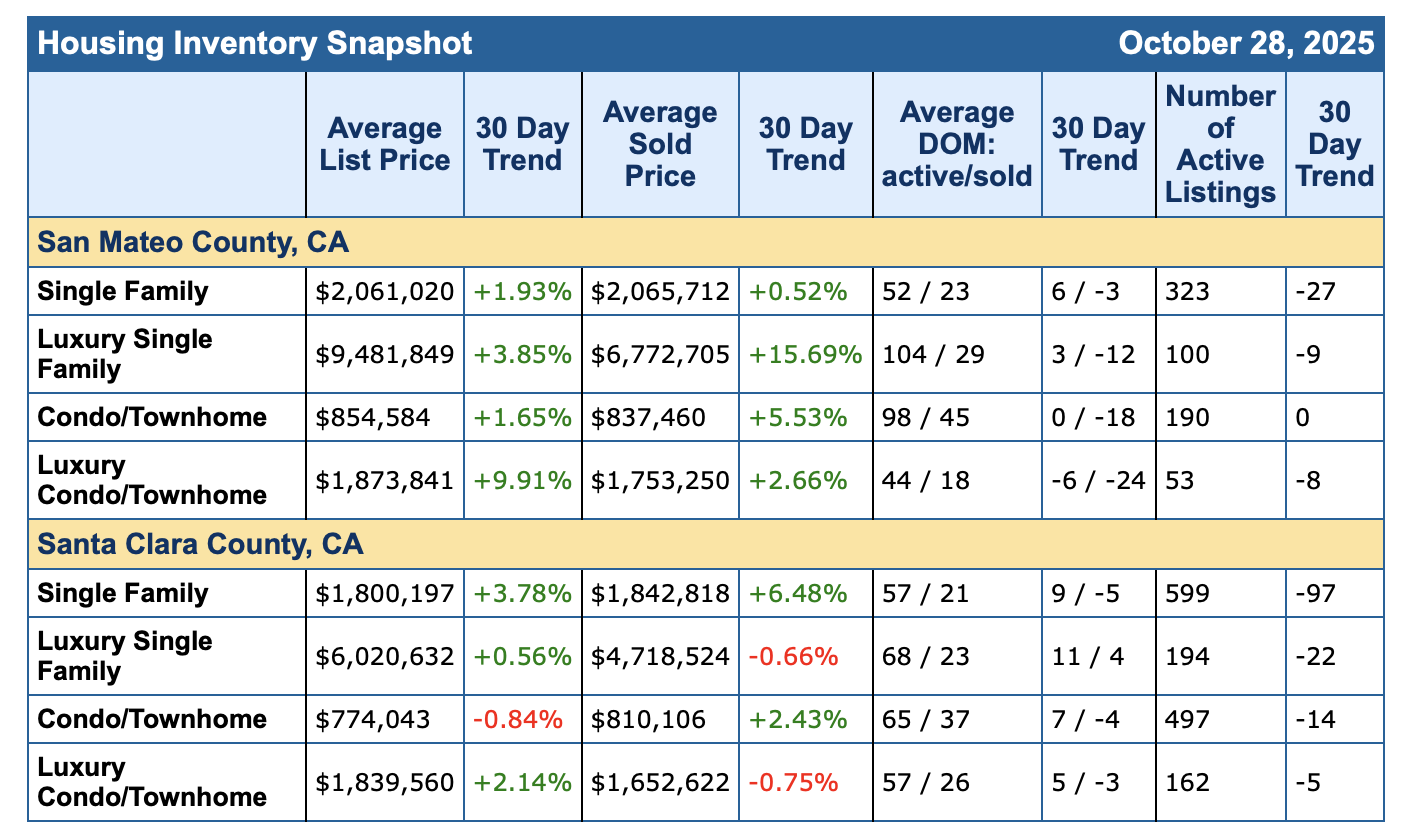
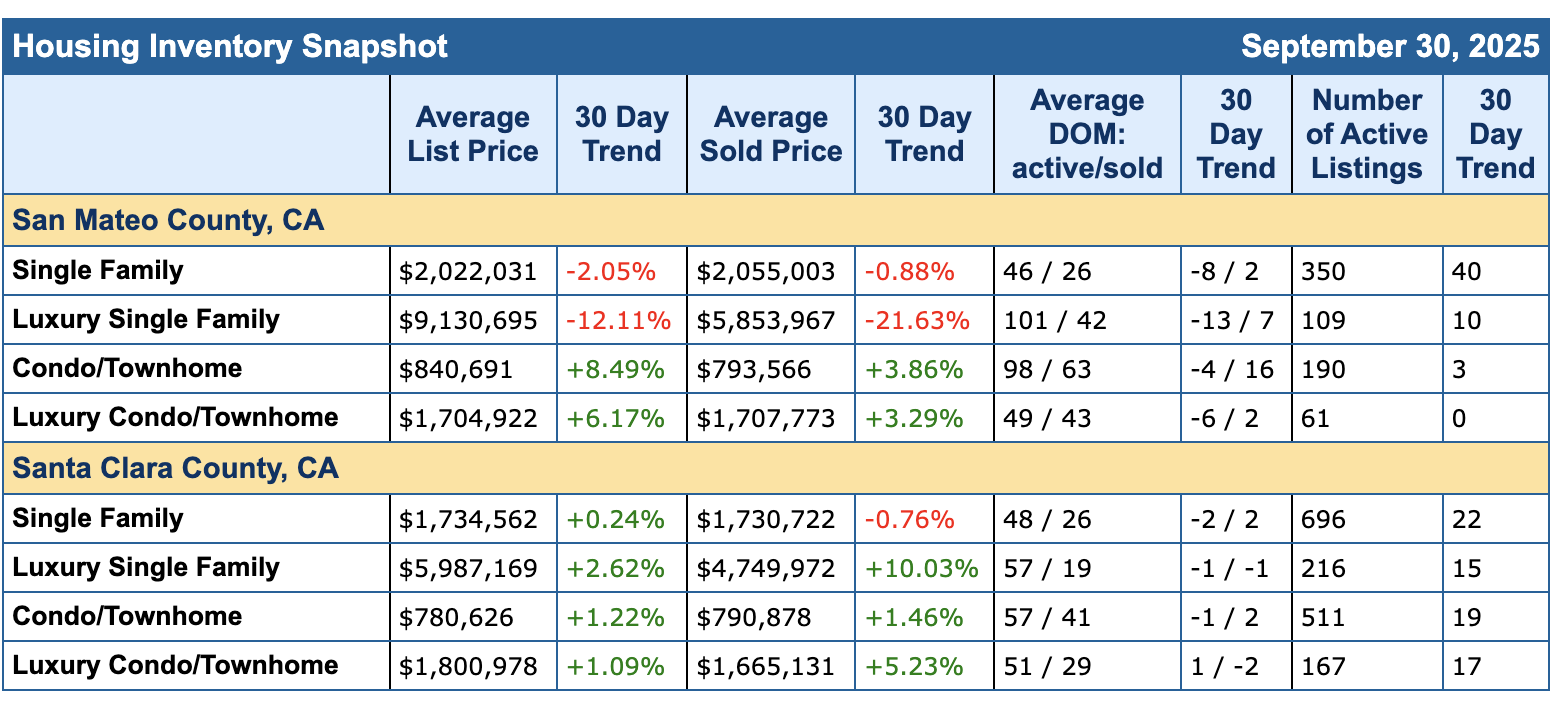
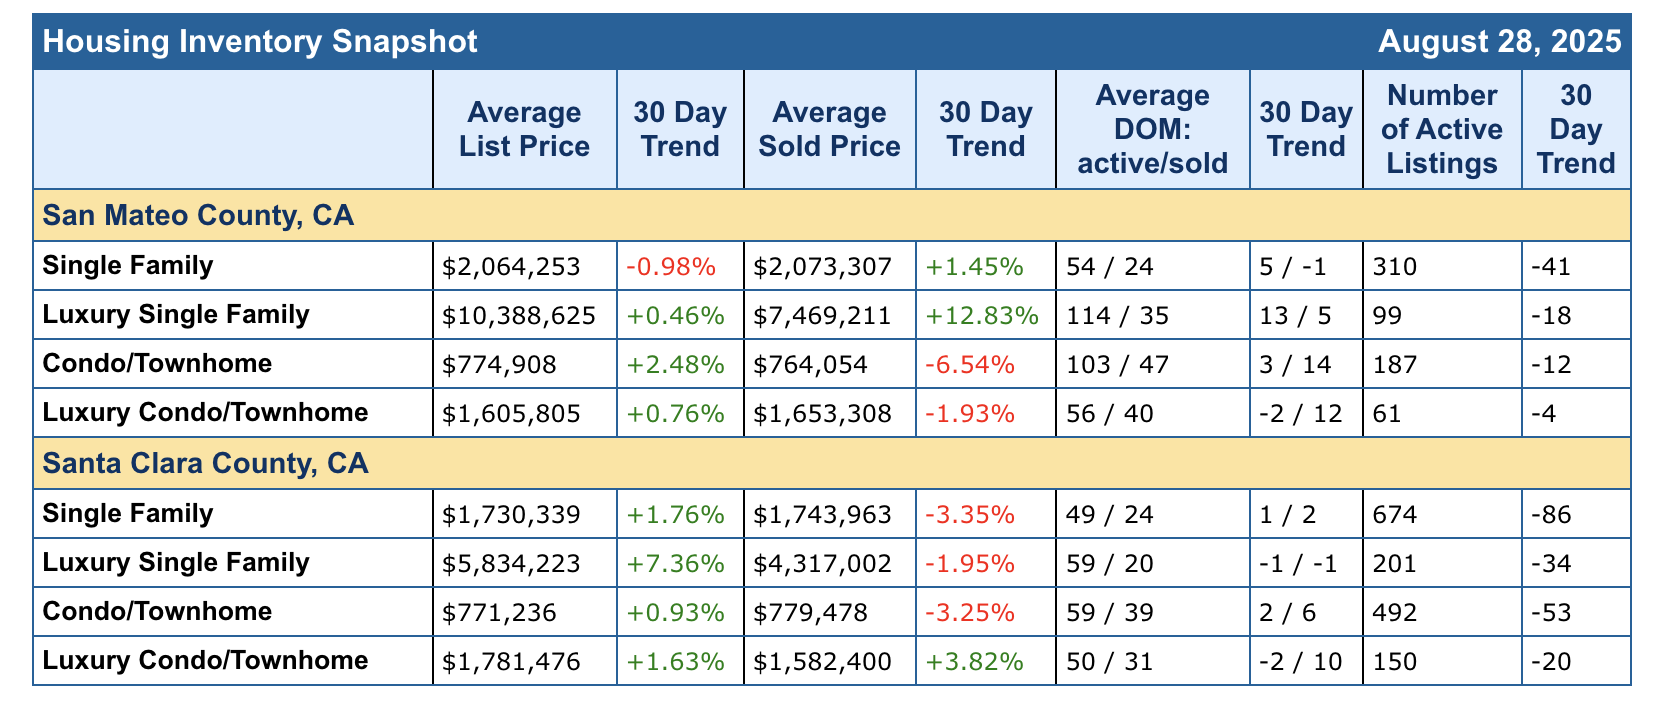
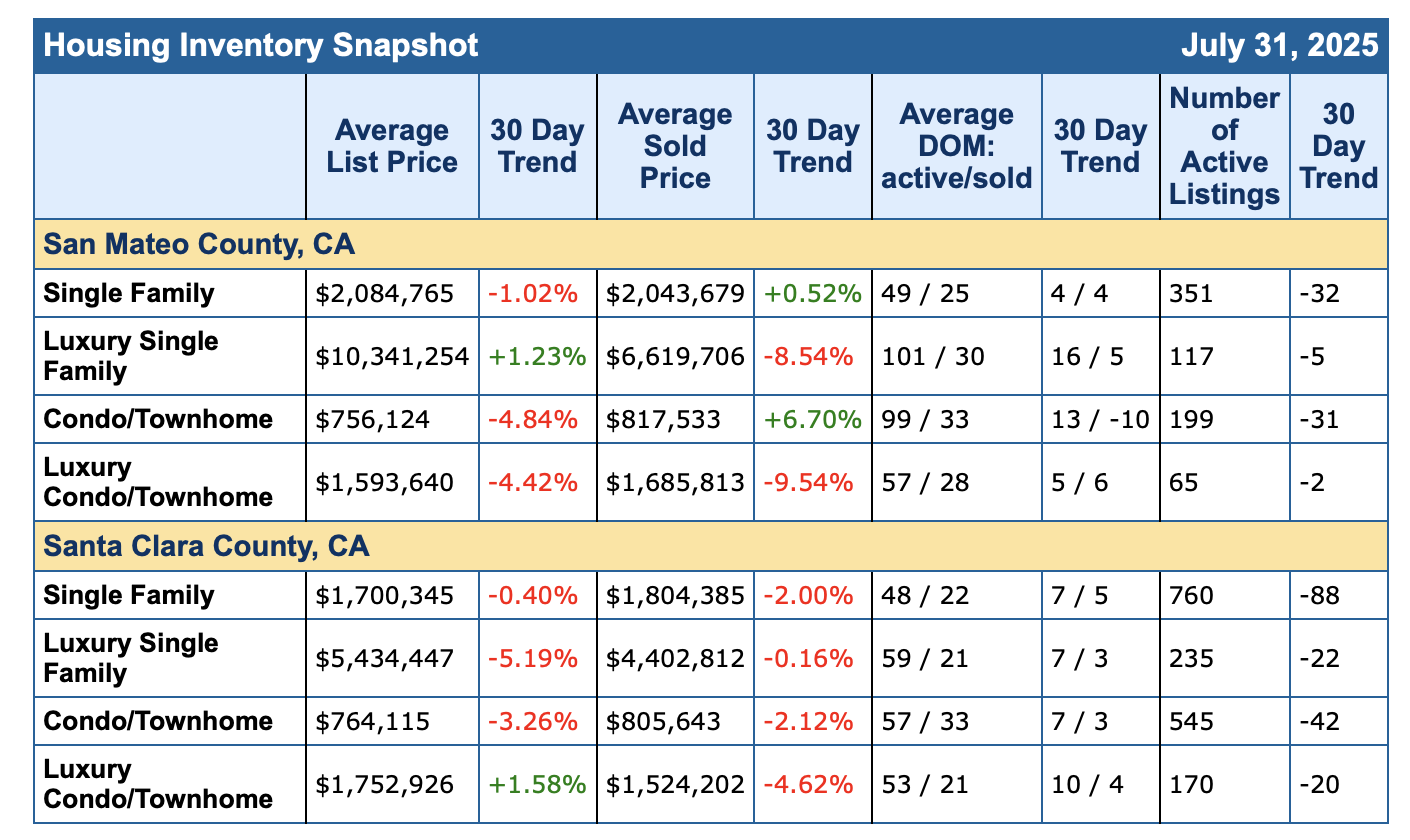
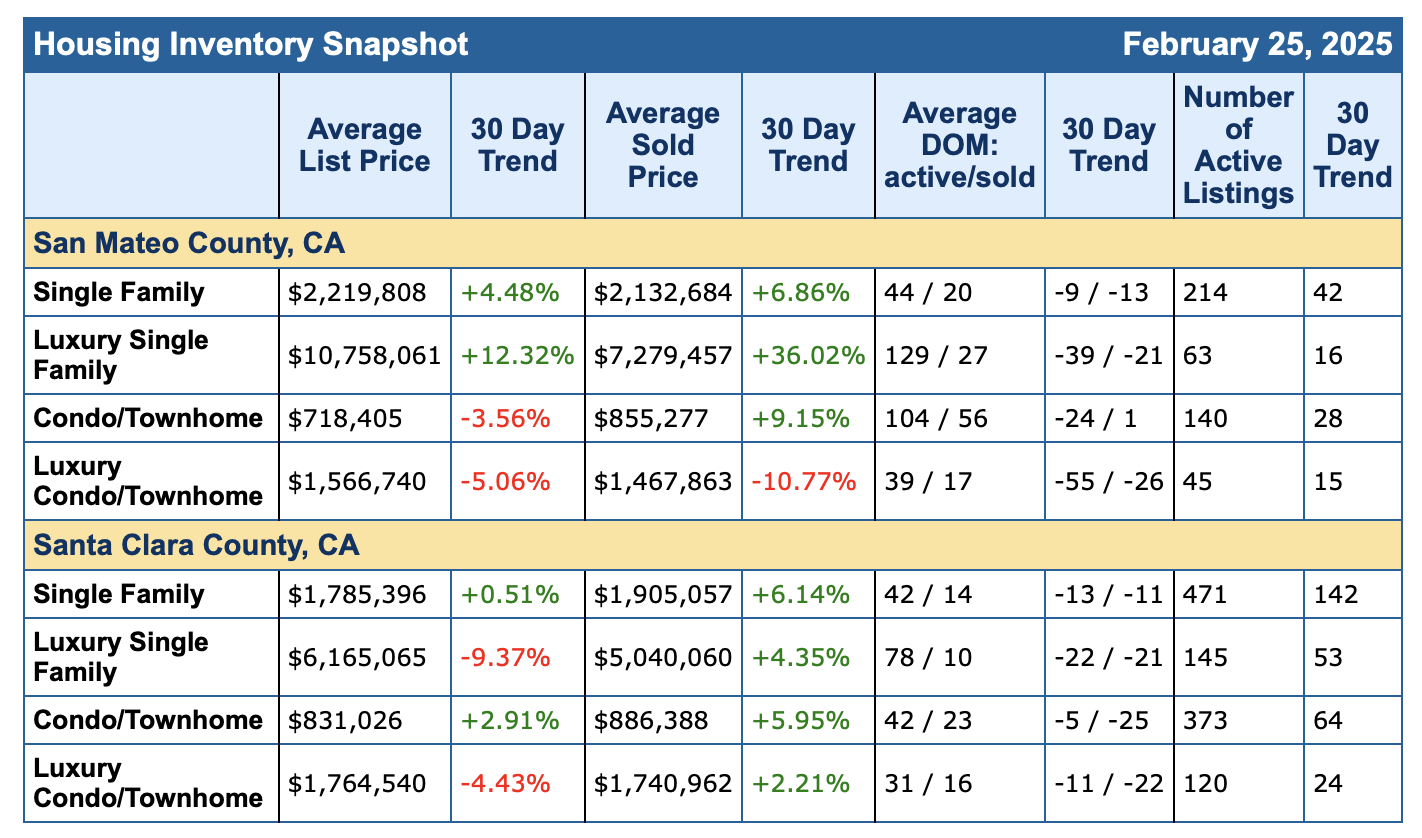
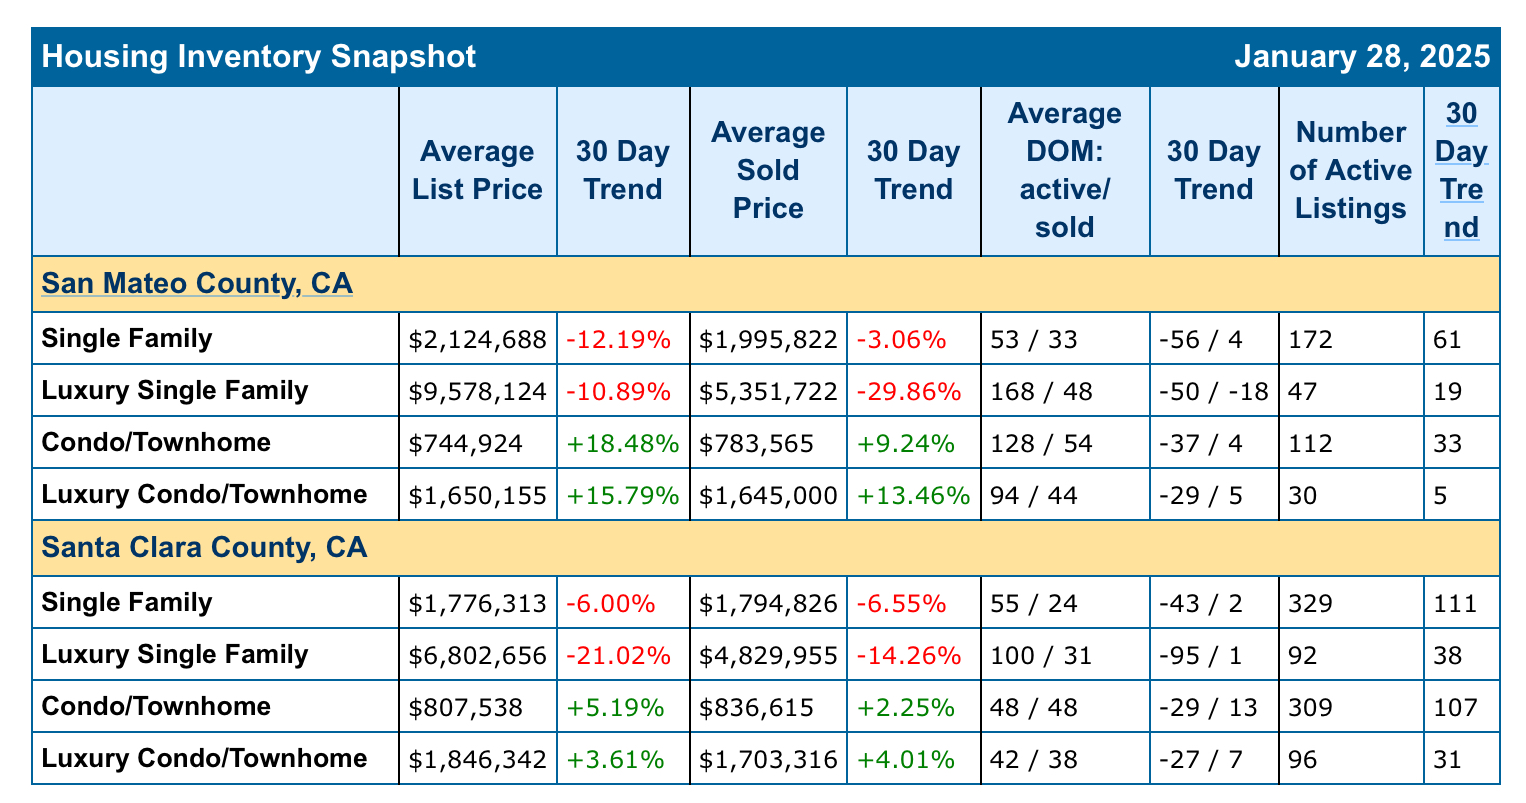
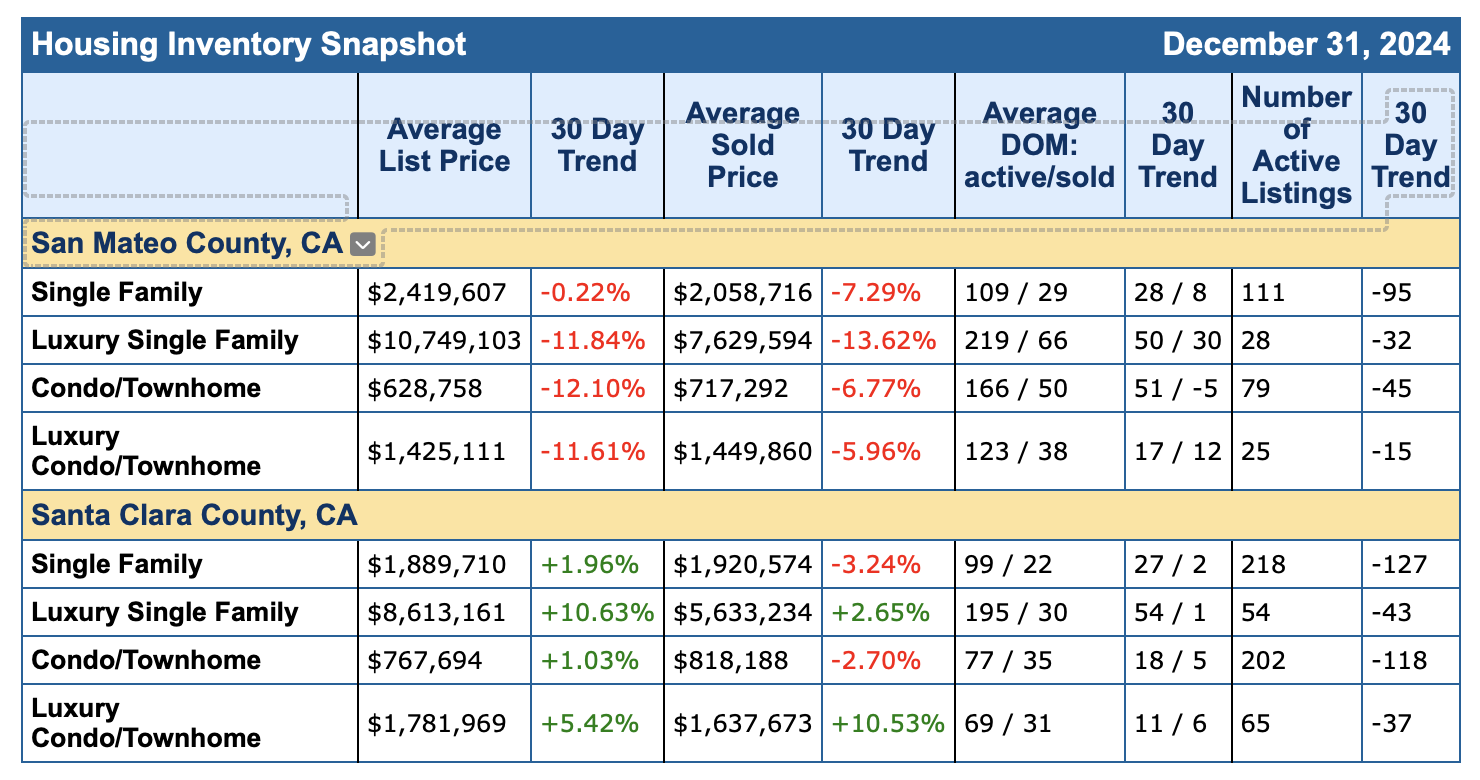
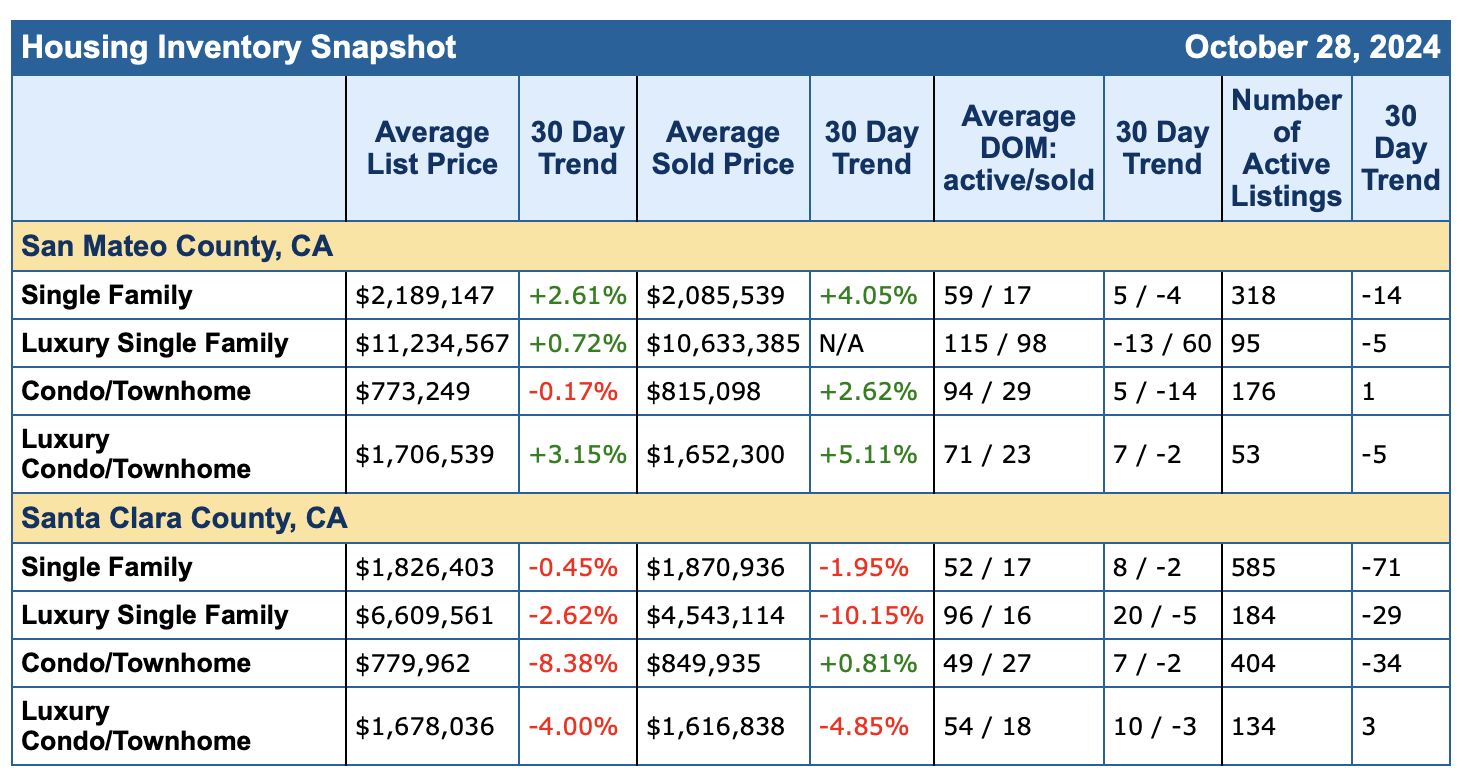
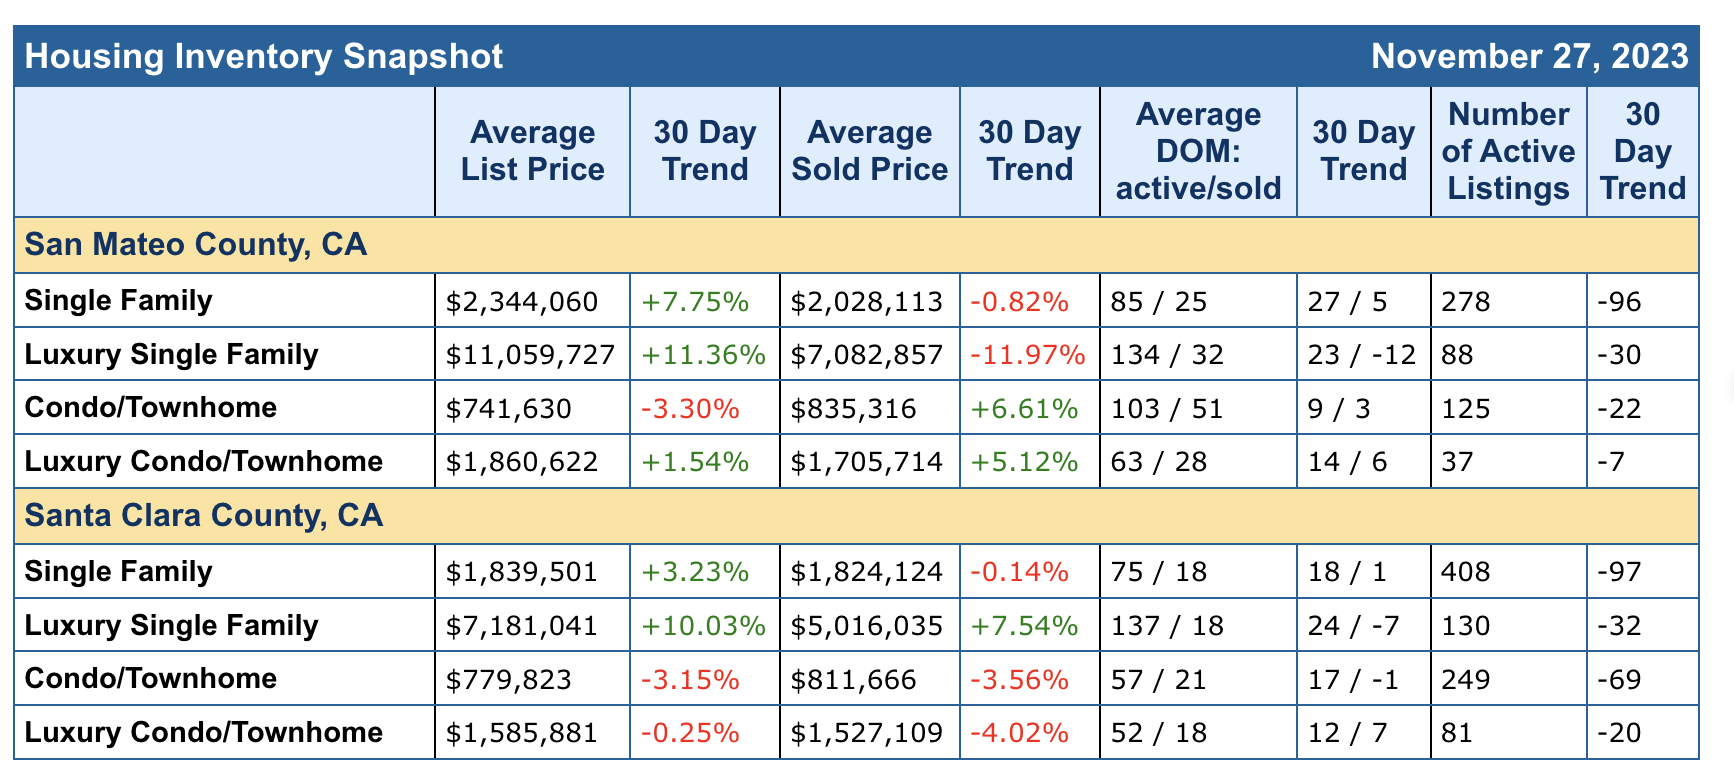
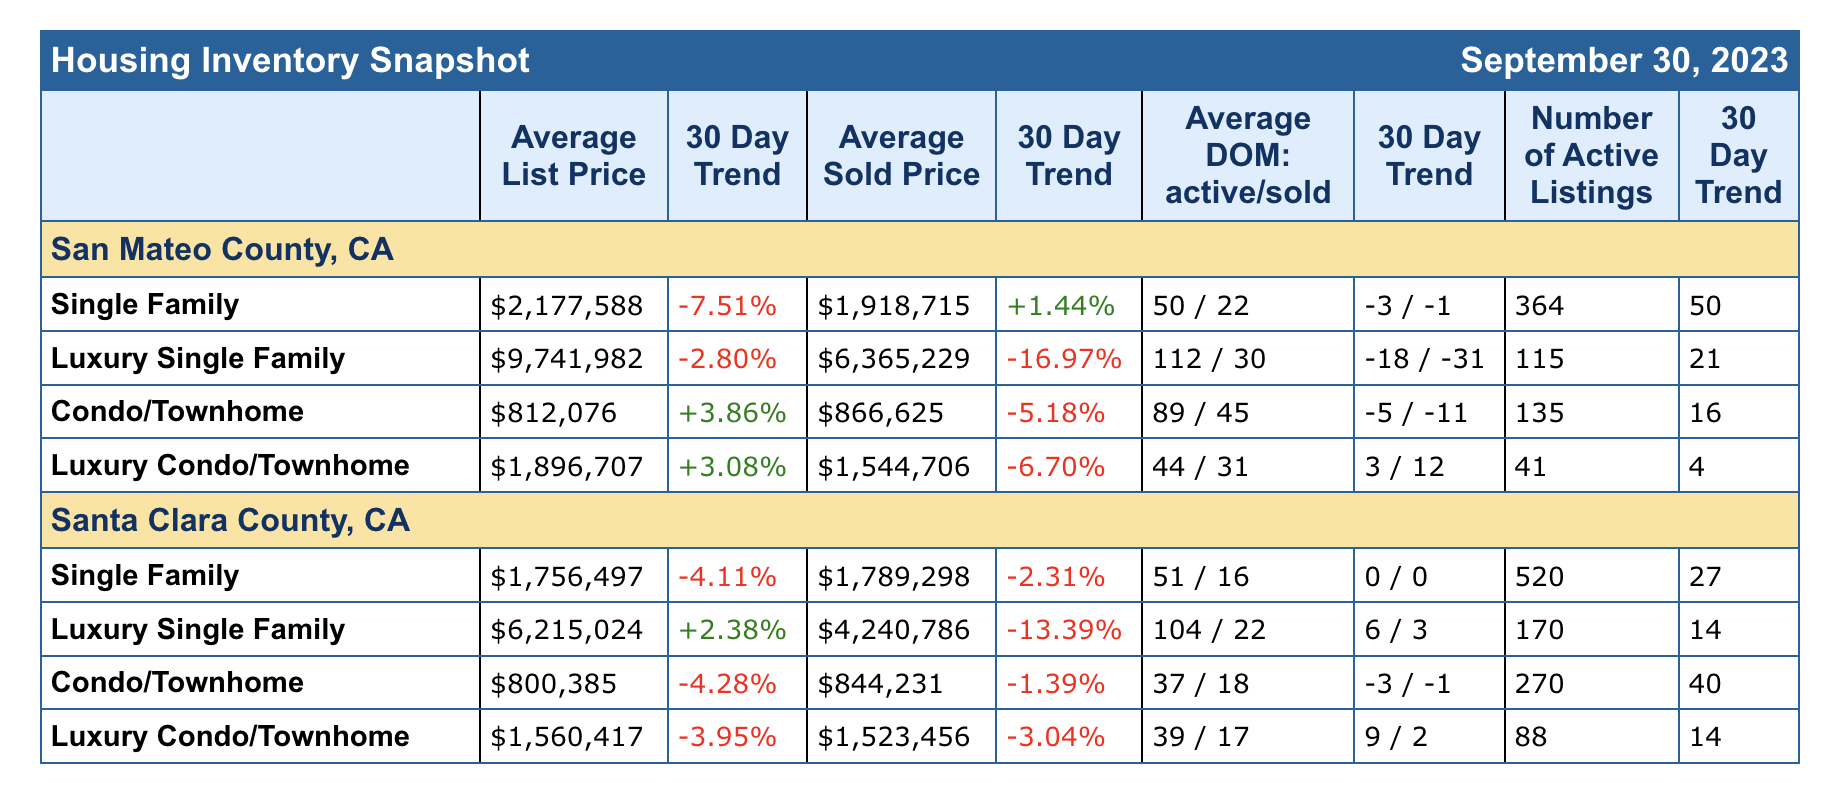
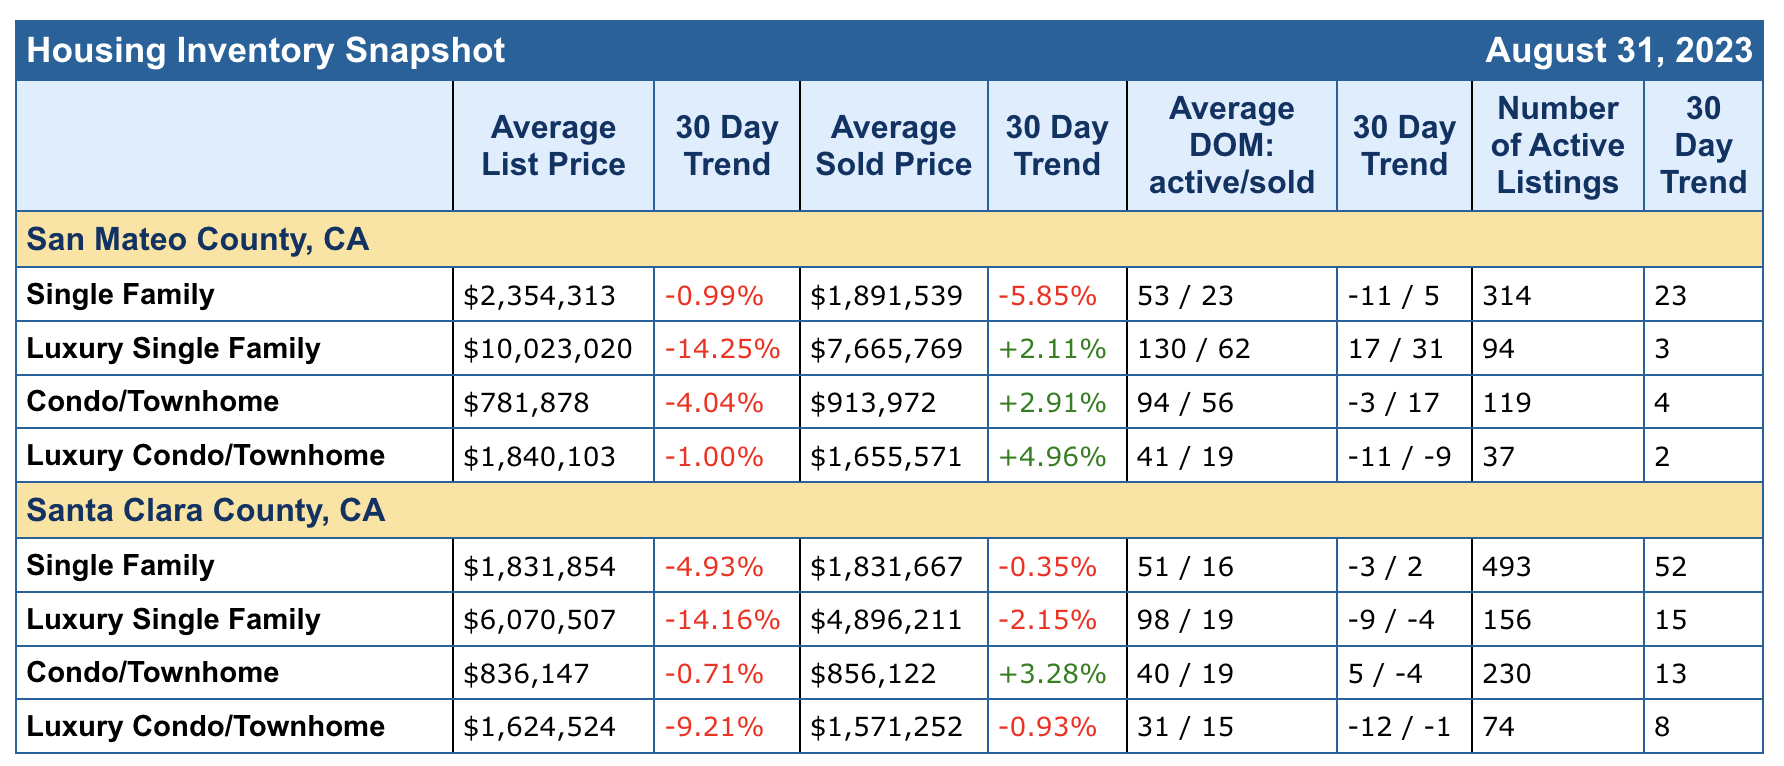
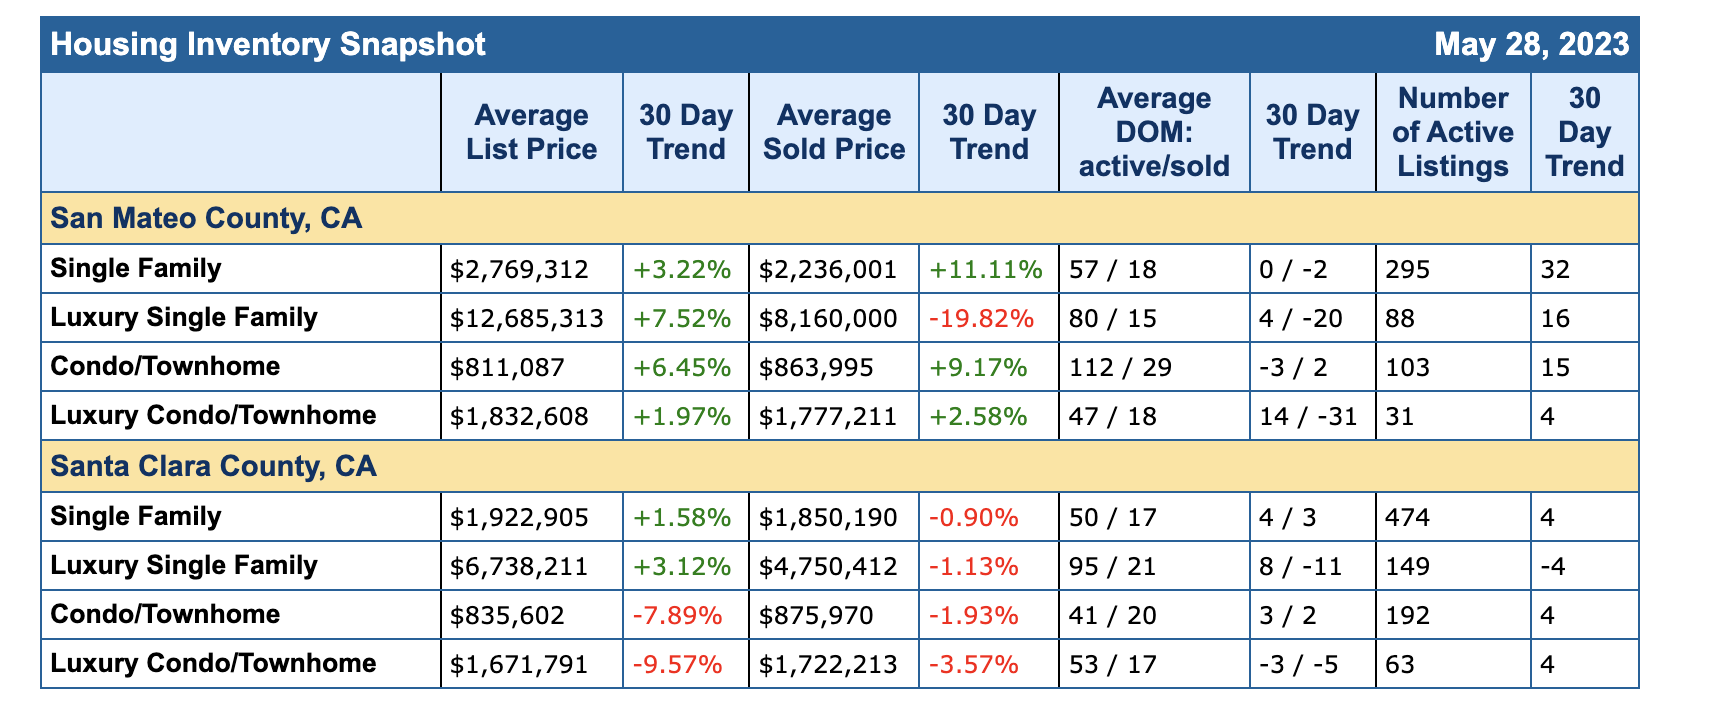
Thank you for tuning in. The stats are in for July 2026.

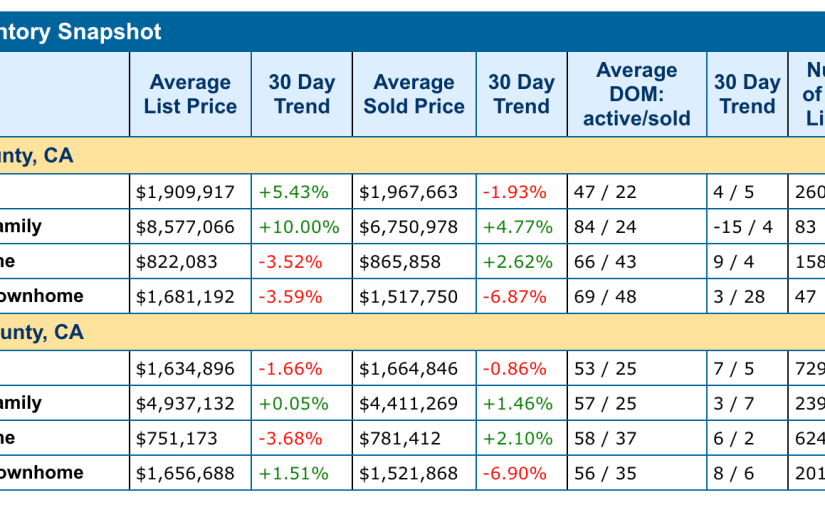
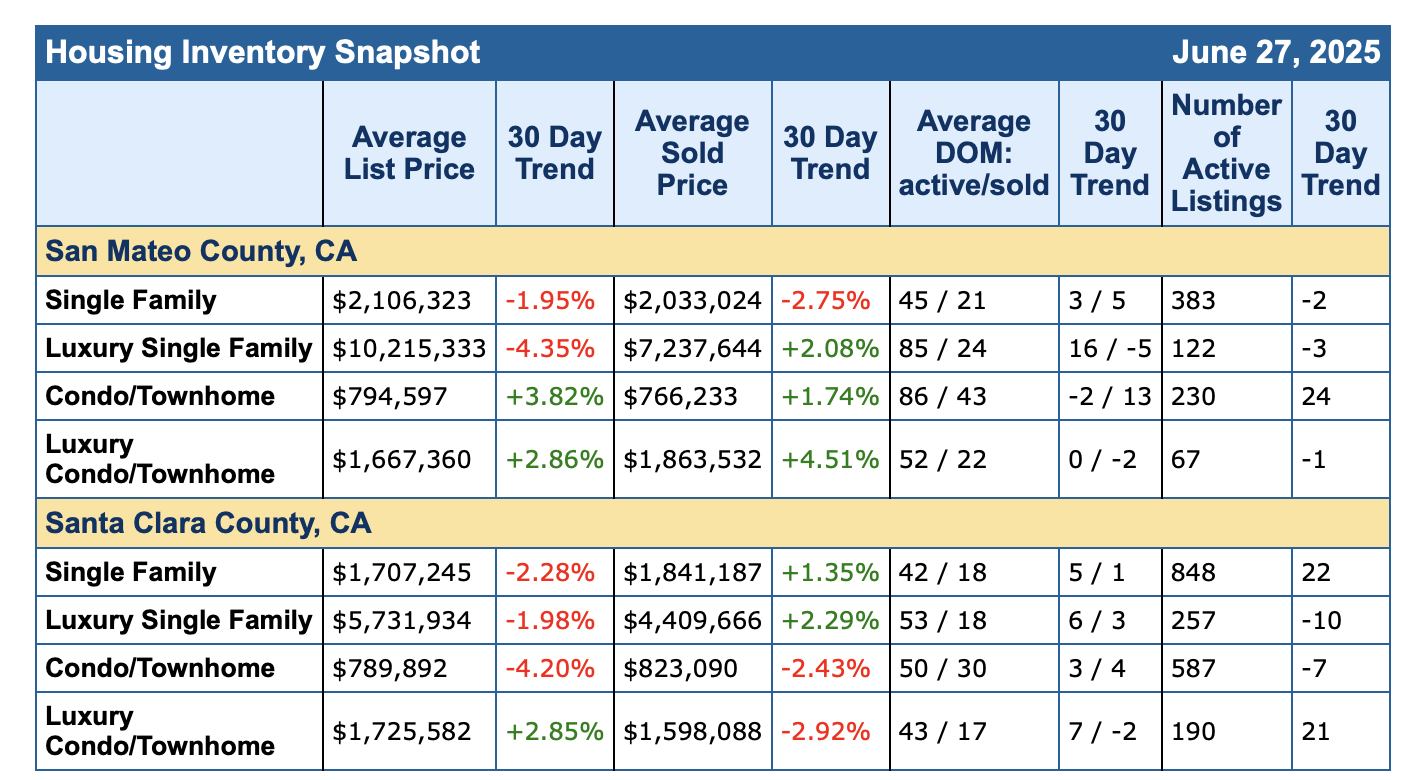
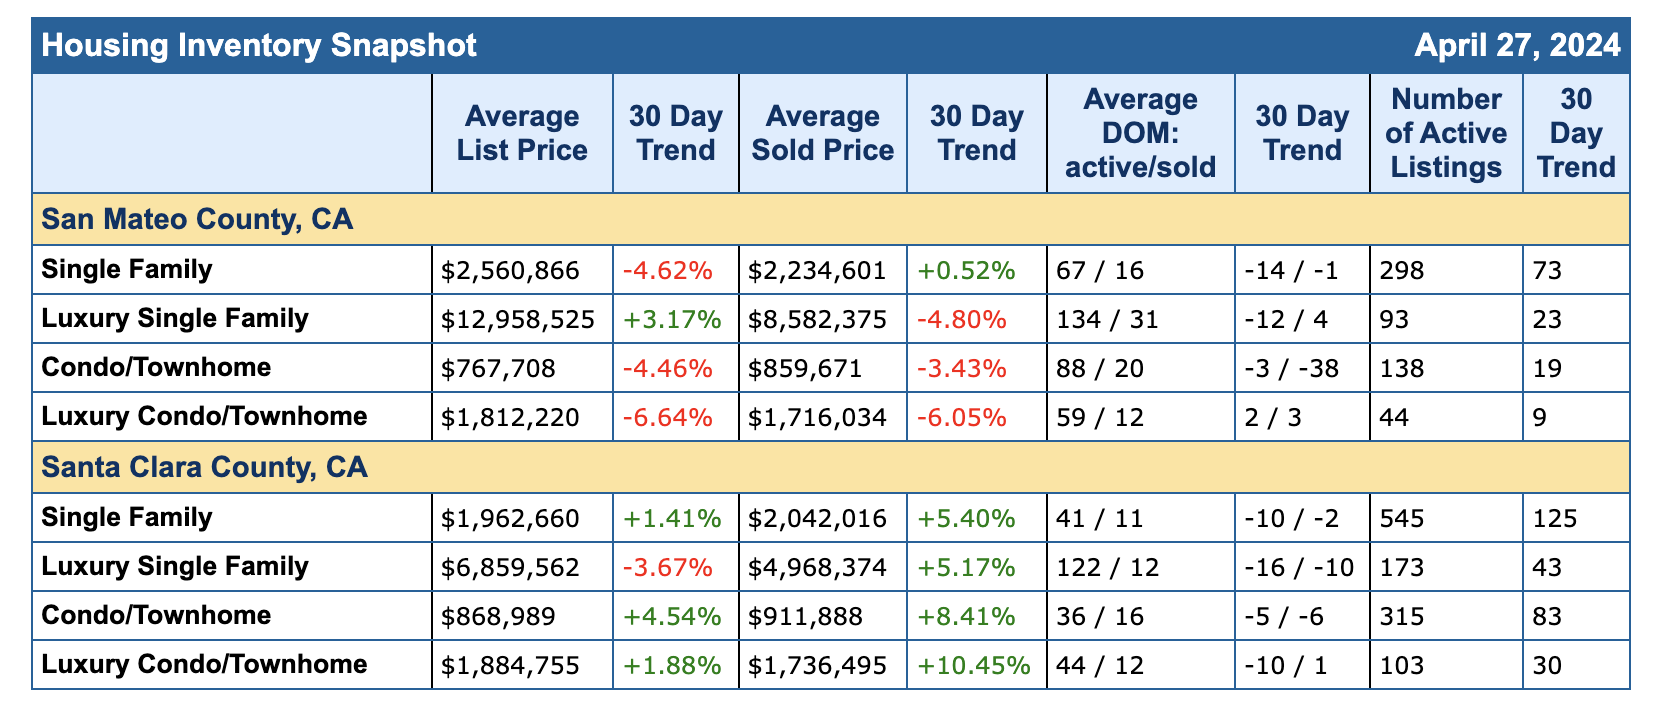
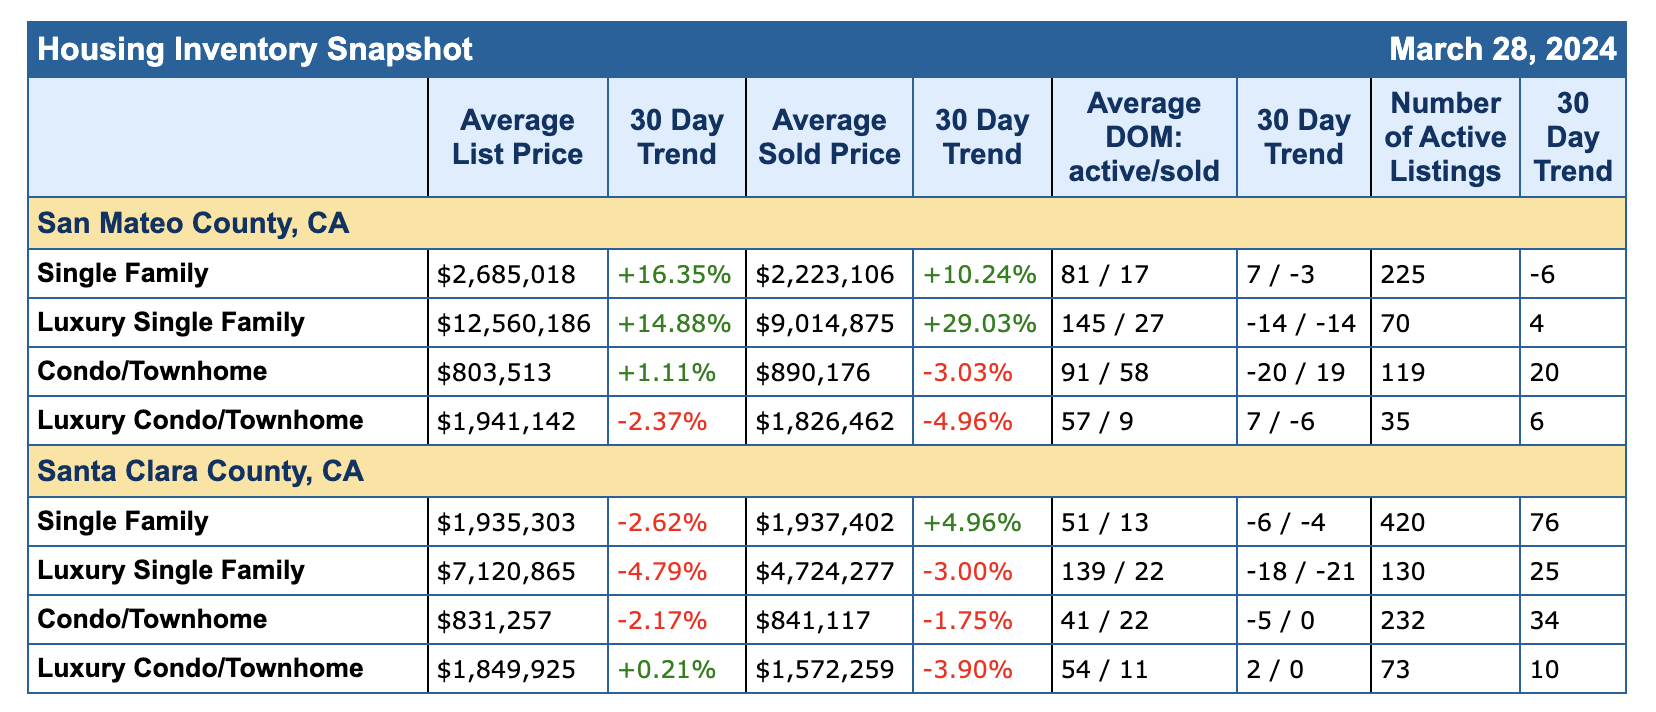
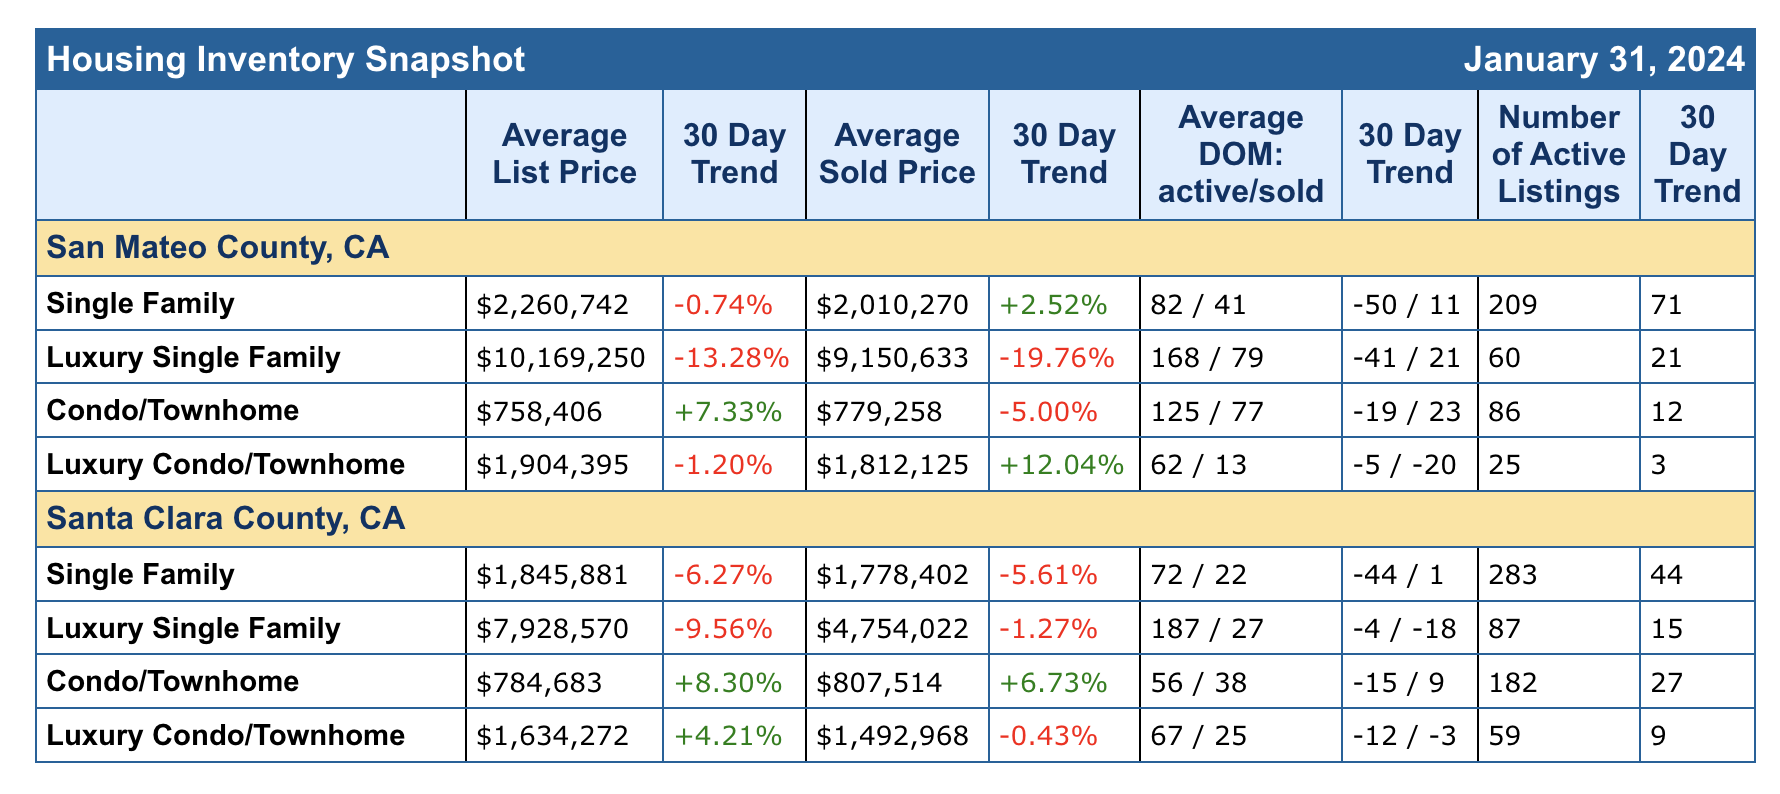
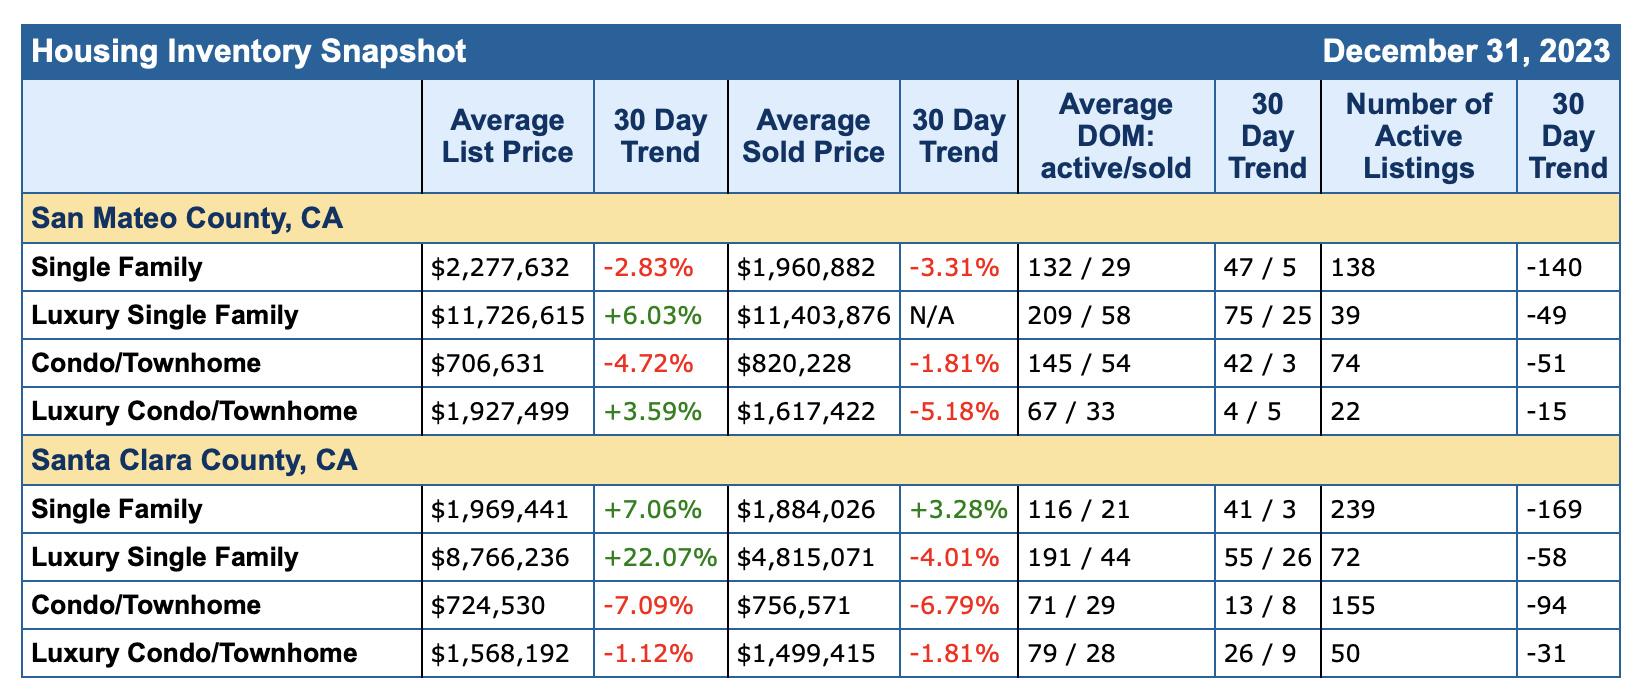
I am happy to see some growth in home sales for San Mateo County. I am not surprised about the dip in the townhome / condo market as they are faced repairs due CA legislation SB 326 (read more here). Small dip in Santa Clara County home sales. The luxury condo market in the South Bay are often newer developments so that may account for the growth there – they may not be faced with repairs due to older buildings.

As Summer comes to and end and Fall begins. I am curious where are market will go. I’ve seen an increase in buyers getting approved for loans, but also many opting to rent and save in order to buy something more to their liking. That can be a tricky move as waiting one year will impact purchase power if homes continue to appreciate and I think they will – it is the pace that I see slowing down. Homes in California have been appreciating since 1849 (I kid but you get it) – it just may not be as steep. Add some tech lay offs and we stand by to see the impact. However…

If you want to live in the Bay Area, if you have a steady job here and want to grow roots here – NOW – is a great time to buy. There are properties sitting, there are price reductions – this is an opportunity for a buyer to get a house, even under list with contingencies! As long as you see yourself here for about 7-10 years – that is a realistic time it takes to see appreciation. The longer you hold onto a home, the better. So when the market is soft and you have long terms goals here – let’s jump in.

The Caton Team provides free buying and selling consultations – to determine the current value of your home if you are selling or if you’re in the market to buy – where you get the most bang for your buck.

Remember, each neighborhood is different, if you are considering a purchase – let us guide you through this and help you find your way home.

If you’re in the market to sell – each area and price point has it’s own pros and cons – let us help you figure out your next steps.

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home. We have before and we will again. We move with the market.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined, local Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at sabrina_caton@yahoo.com.

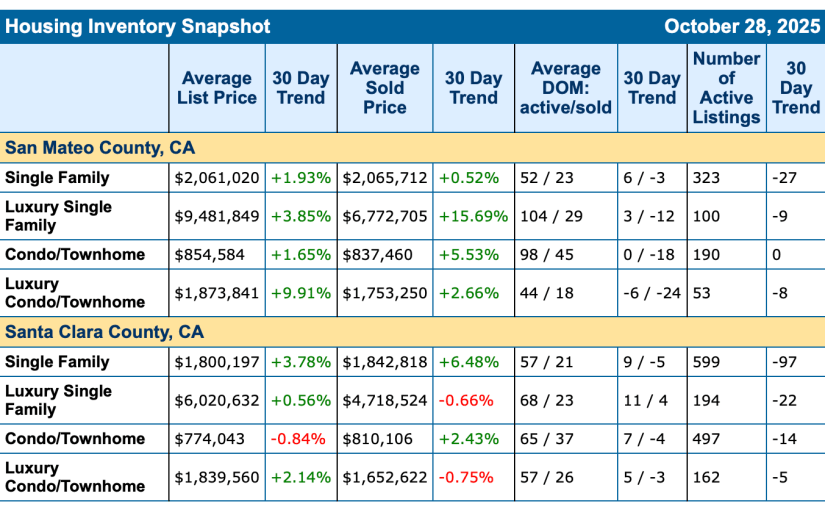
Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 45 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home

Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

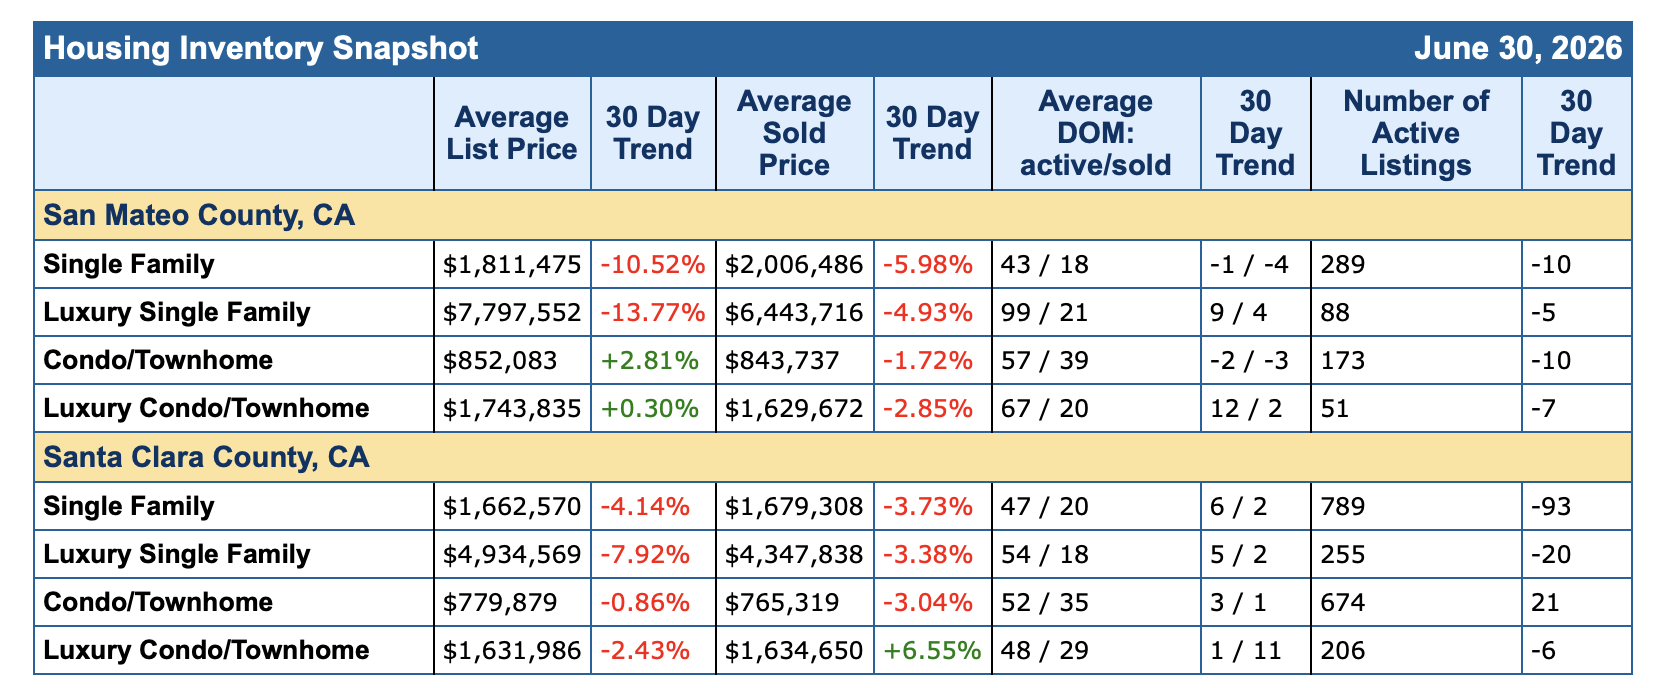
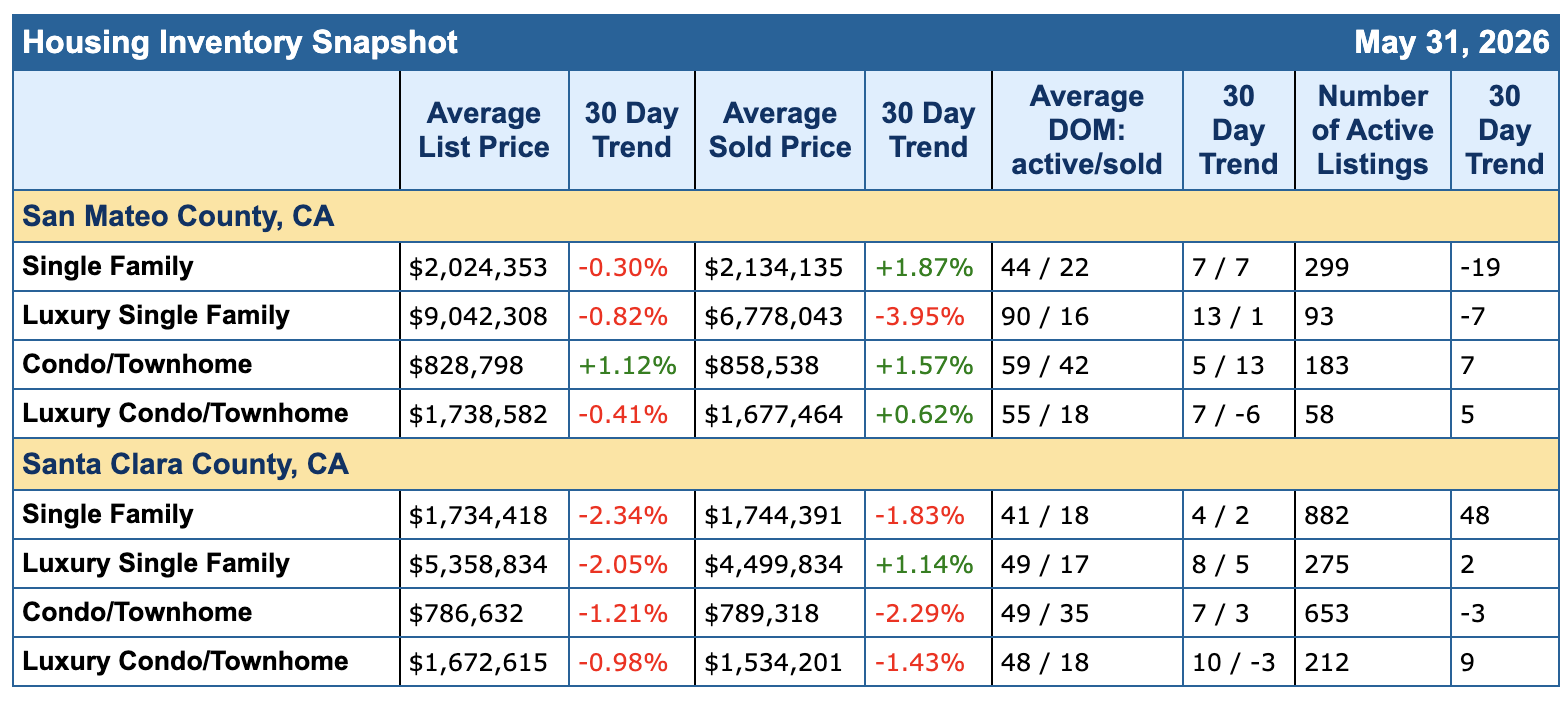
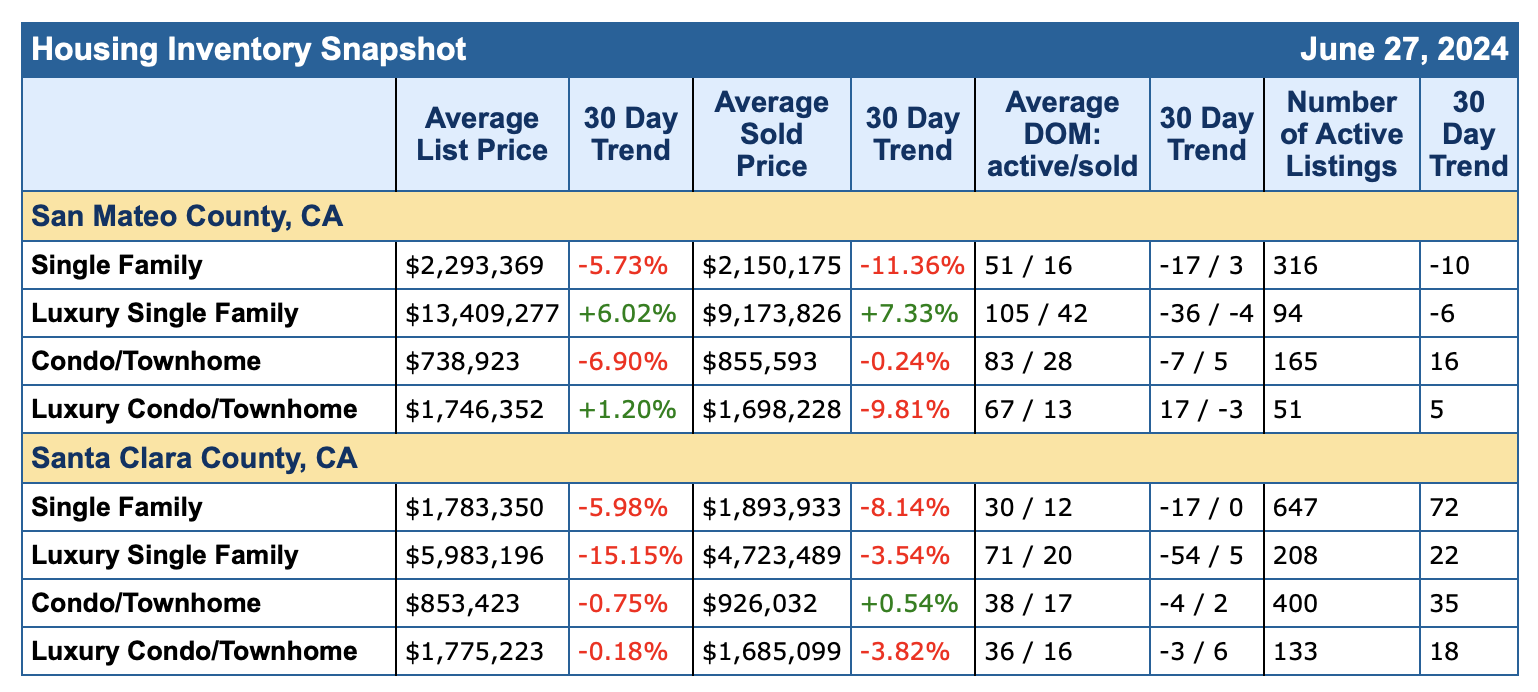
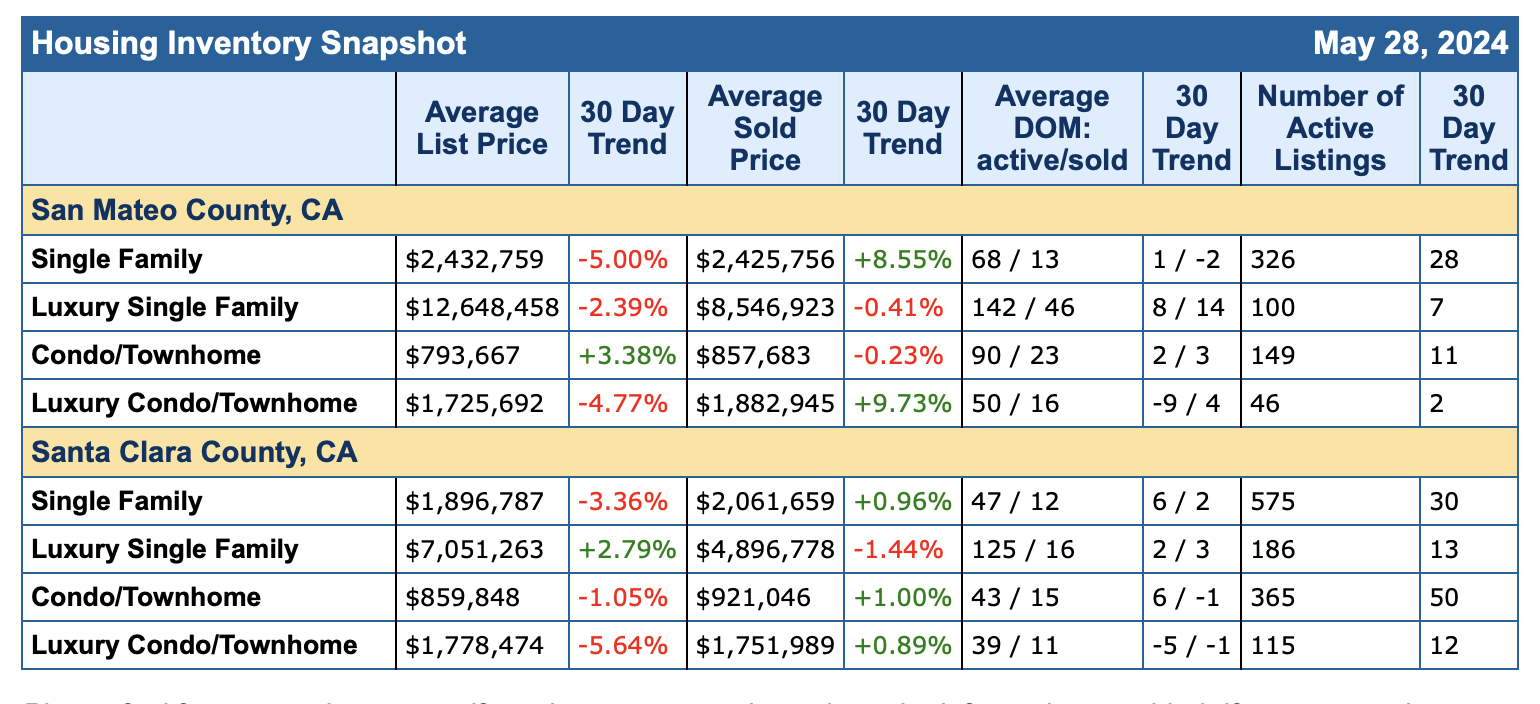
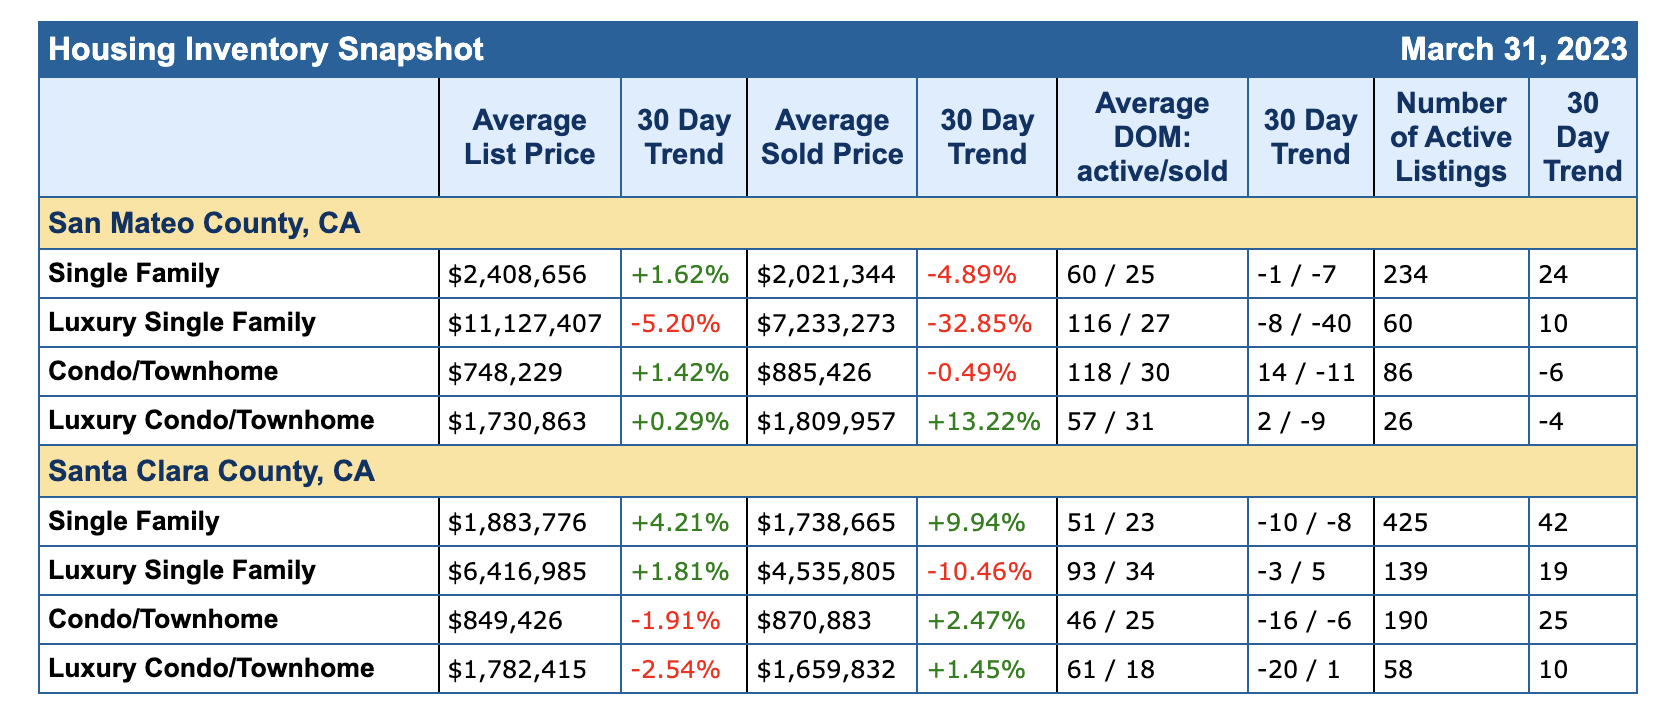
The Stats are In… Market Snapshot for May & June 2026

Hello Caton Team Blog Readers,

Thank you for tuning in. The stats are in for May and June 2026.

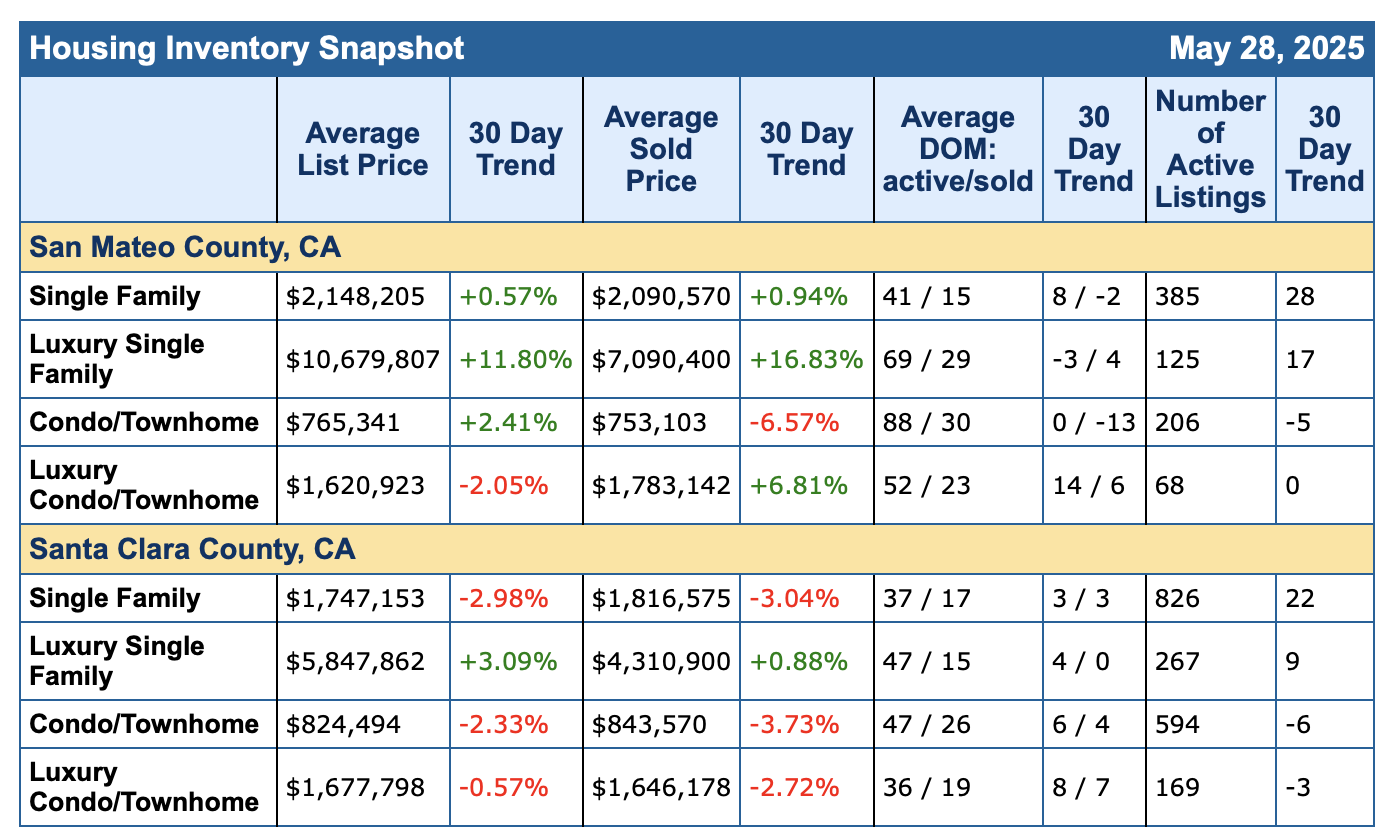
Welp – in May we saw all market points take a dip. With a slight rise in May and June for Condos / Townhomes. Across the board we are seeing a dip in sales. Is it seasonal? Doesn’t feel that way – we often see a good boost in sales each May – as that is the start of selling season and June often holds steady but this year is a bit different. There is so much going on in the world, economically and socially.

With no expected drop in interest rates and the cost of gas and groceries at an all time high. Folks are feeling it. When fear prevails, or concern, we see a dip in sales, and a dip in active buyers. Oddly enough – this sort of data makes the market ripe for buyers but not everyone feels they can take the plunge.

When the market is weird, it is actually a great time to buy in the Bay Area. Some homes still get multiple offers but some do not – and instead of waiting for a price drop – when you work with professional Realtors like The Caton Team – we search those over looked properties – and show them. Don’t wait for a price drop – if you’ve watched a home and it has not sold in 2 -3 weeks – have your agent contact their agent and get the whole picture. We do not wait for price reductions – we are proactive and will see if there is middle ground a buyer and seller can stand on.

With values dipping .8% – 13% – that is a market for buyers! Sellers are not seeing the demand we once had when rates were lower and if a seller has to sell, they are taking a moment to grieve their lost value and hopefully moving forward. The market is the people and what the people are feeling.

If you want to live in the Bay Area, if you have a steady job here and want to grow roots here – NOW – is a great time to buy. There are properties sitting, there are price reductions – this is an opportunity for a buyer to get a house, even under list with contingencies! As long as you see yourself here for about 7-10 years – that is the normal time it takes to see appriciation. The longer you hold onto a home, the better. So when the market is soft and you have long terms goals here – let’s jump in.

The Caton Team provides free buying and selling consultations – to determine the current value of your home if you are selling or if you’re in the market to buy – where you get the most bang for your buck.

Remember, each neighborhood is different, if you are considering a purchase – let us guide you through this and help you find your way home.

If you’re in the market to sell – each area and price point has it’s own pros and cons – let us help you figure out your next steps.

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home. We have before and we will again. We move with the market.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at sabrina_caton@yahoo.com.

Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 45 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

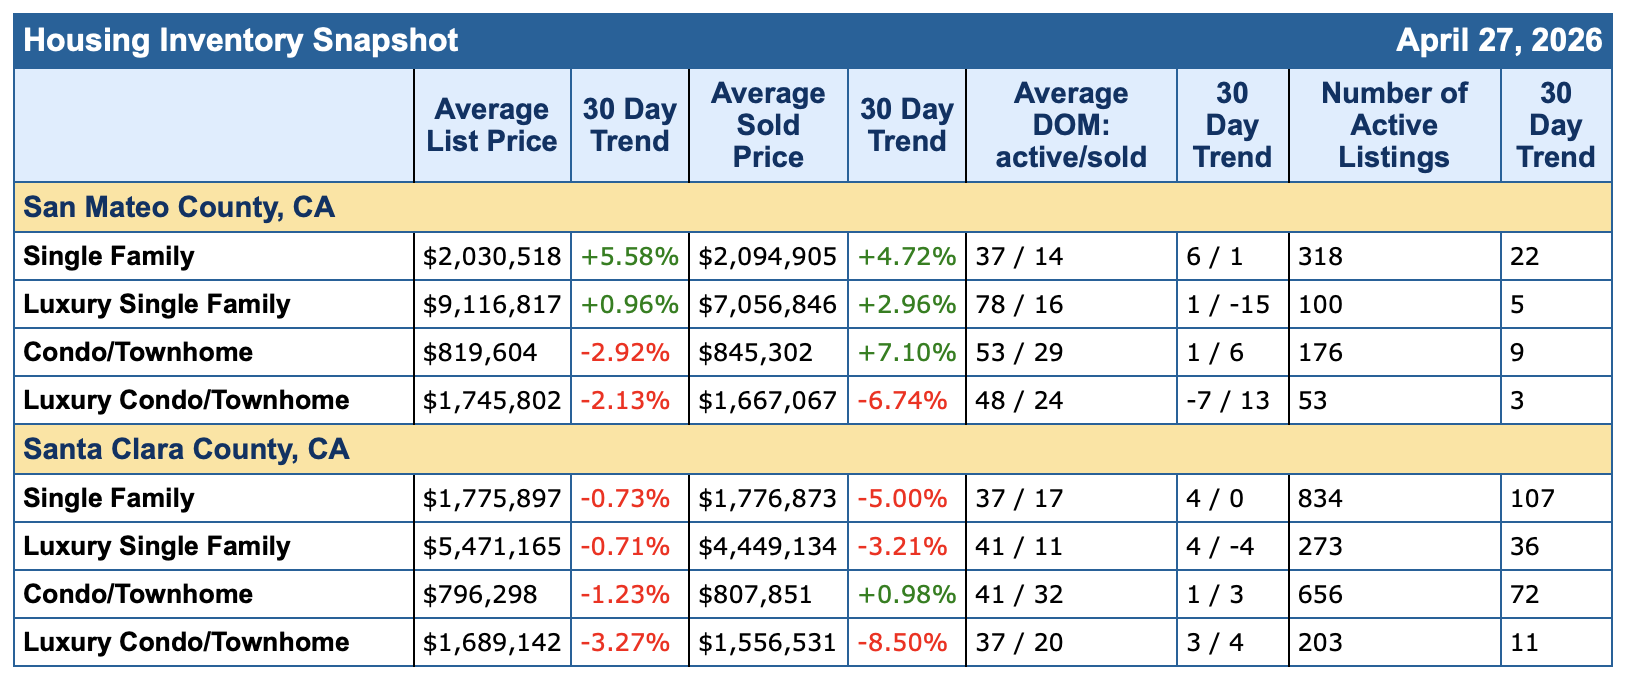
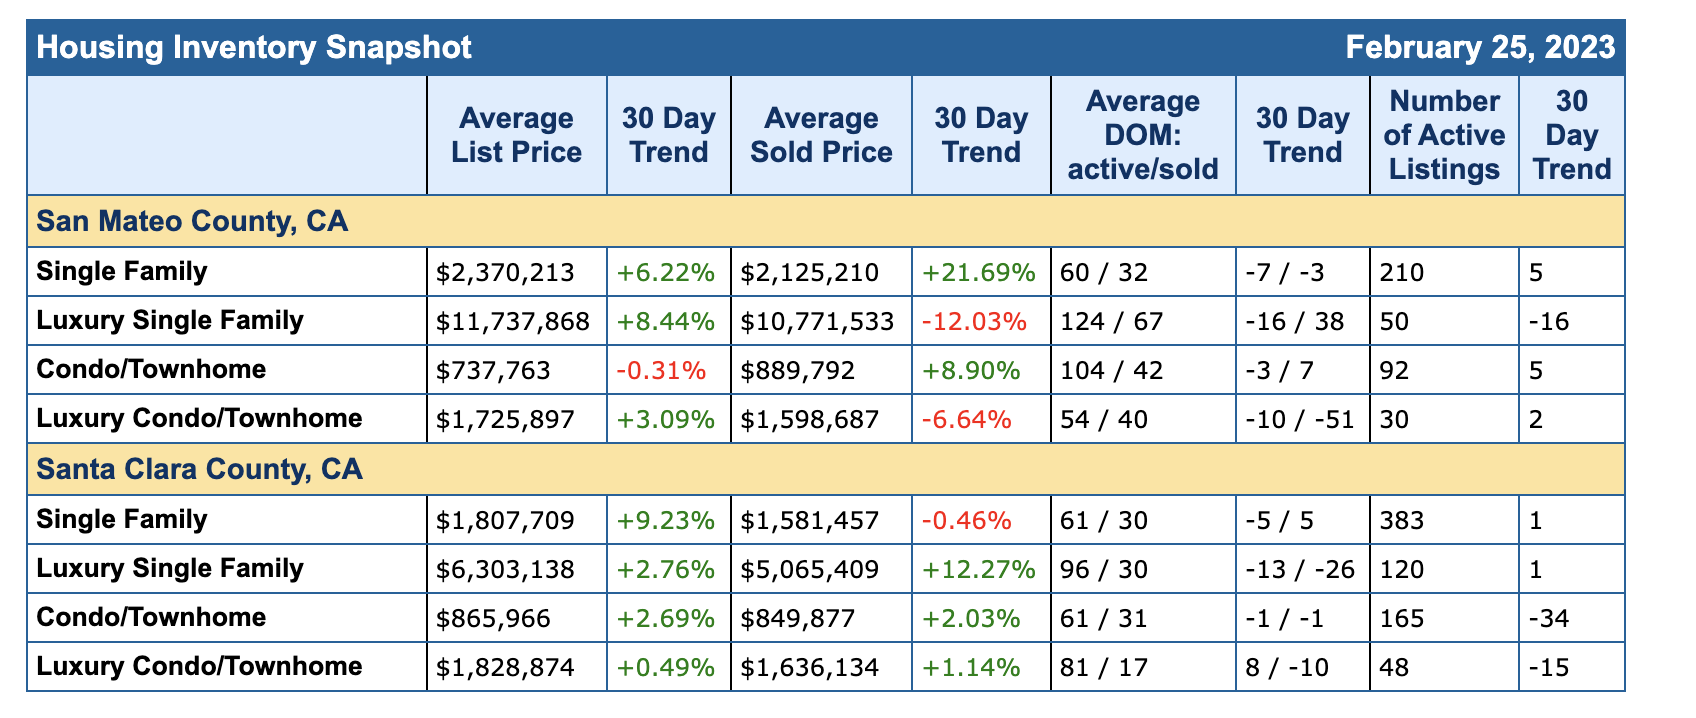
The Stats are In… Market Snapshot for April 2026

Hello Caton Team Blog Readers,

The stats are in for April 2026.

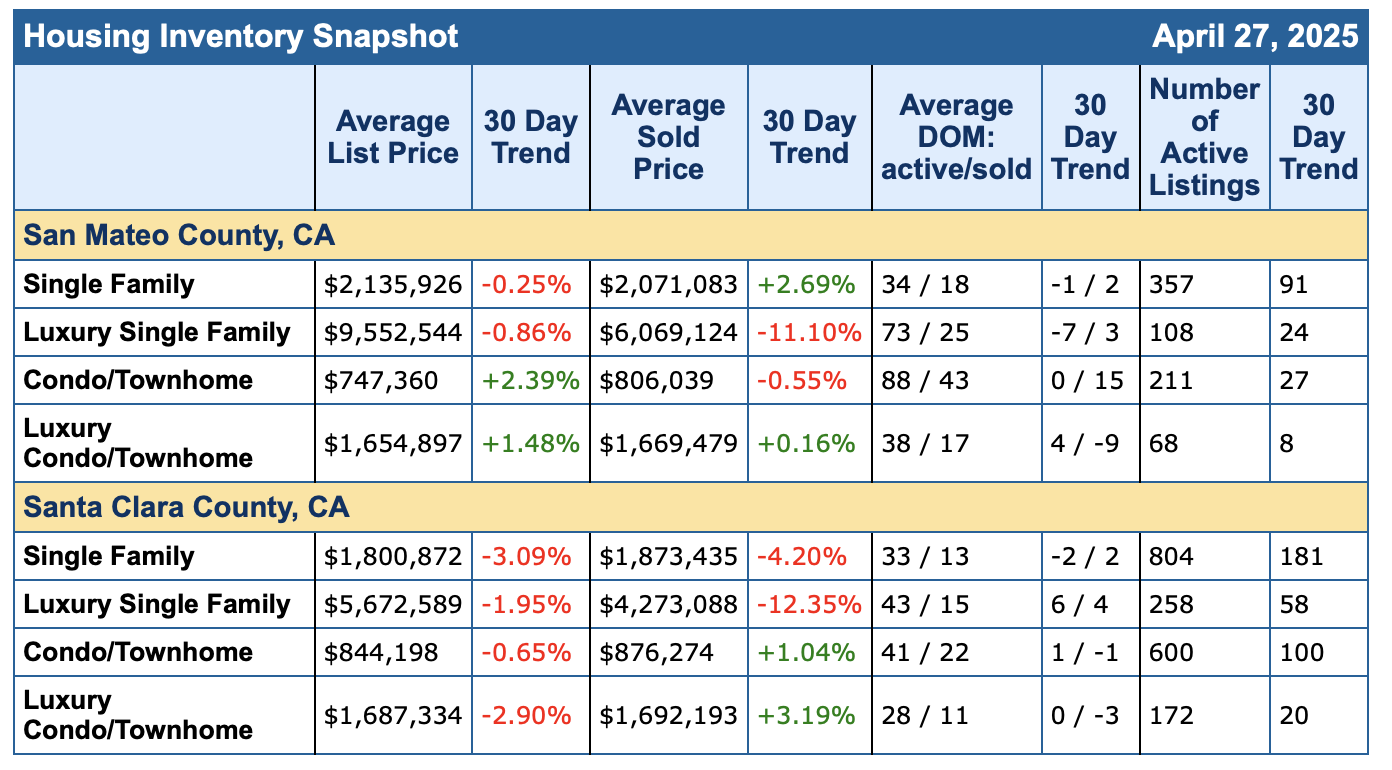
Oddly enough – the high-end sector is doing great! Homes above 2 million are selling and with multiple offers.

However – with the cost of gas and groceries – we’re seeing some adjustment in the market. Interest rates are holding where they are – so no relief in sight for the buyers on that front. Which oddly enough makes it a bit of a buyers market. So keep saving, keep looking and if you are in the market to buy – each neighborhood is different, so let us guide you through this and help you find your way home.

If you’re in the market to sell – each area and price point has it’s own pros and cons – let us help you figure out your next steps.

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at info@TheCatonTeam.com.

Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 40 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

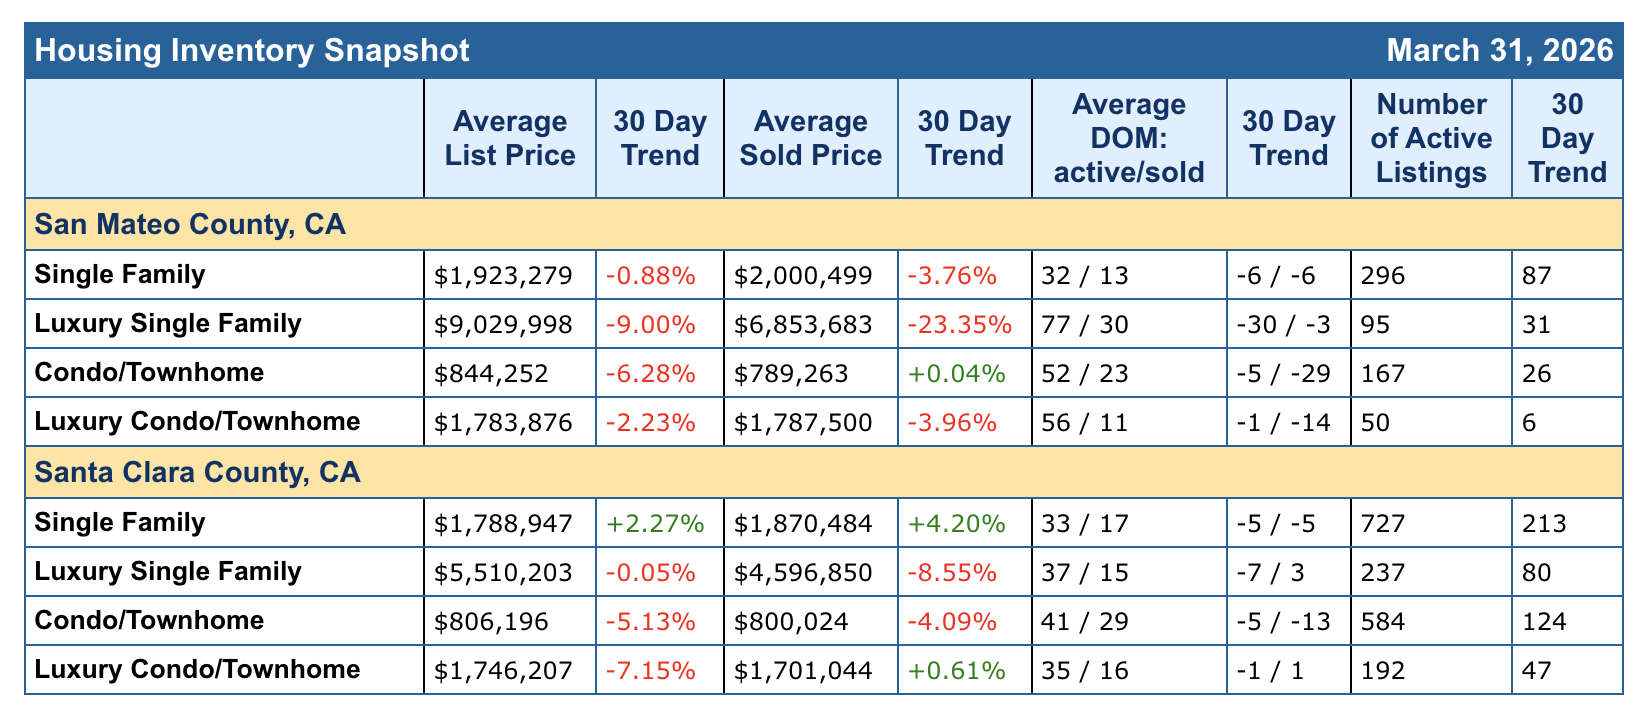
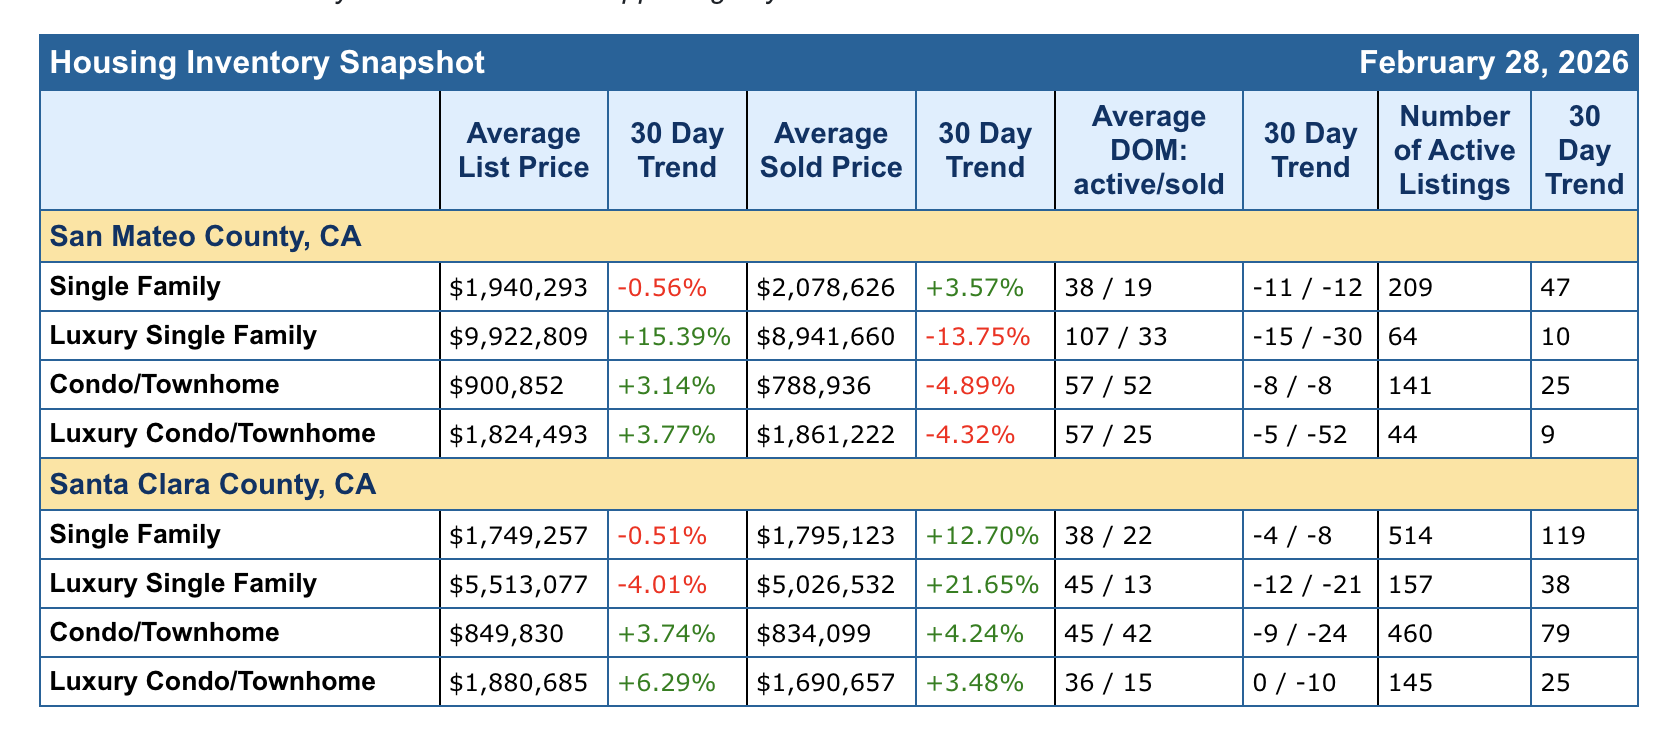
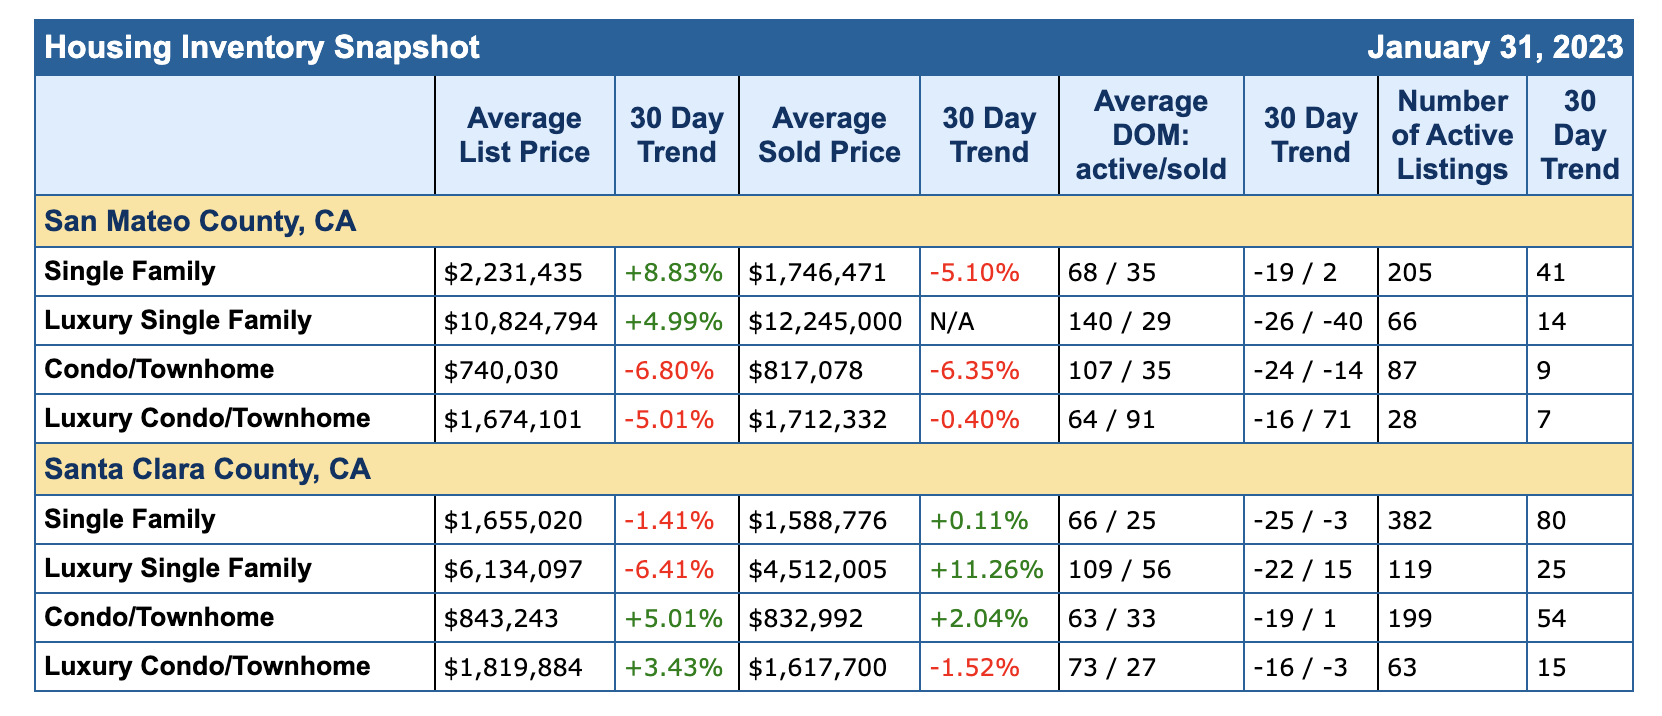
The Stats are In… Market Snapshot for Feb 2026 & March 2026

Hello Caton Team Friends,

The stats are in for Feb & Mar 2026.

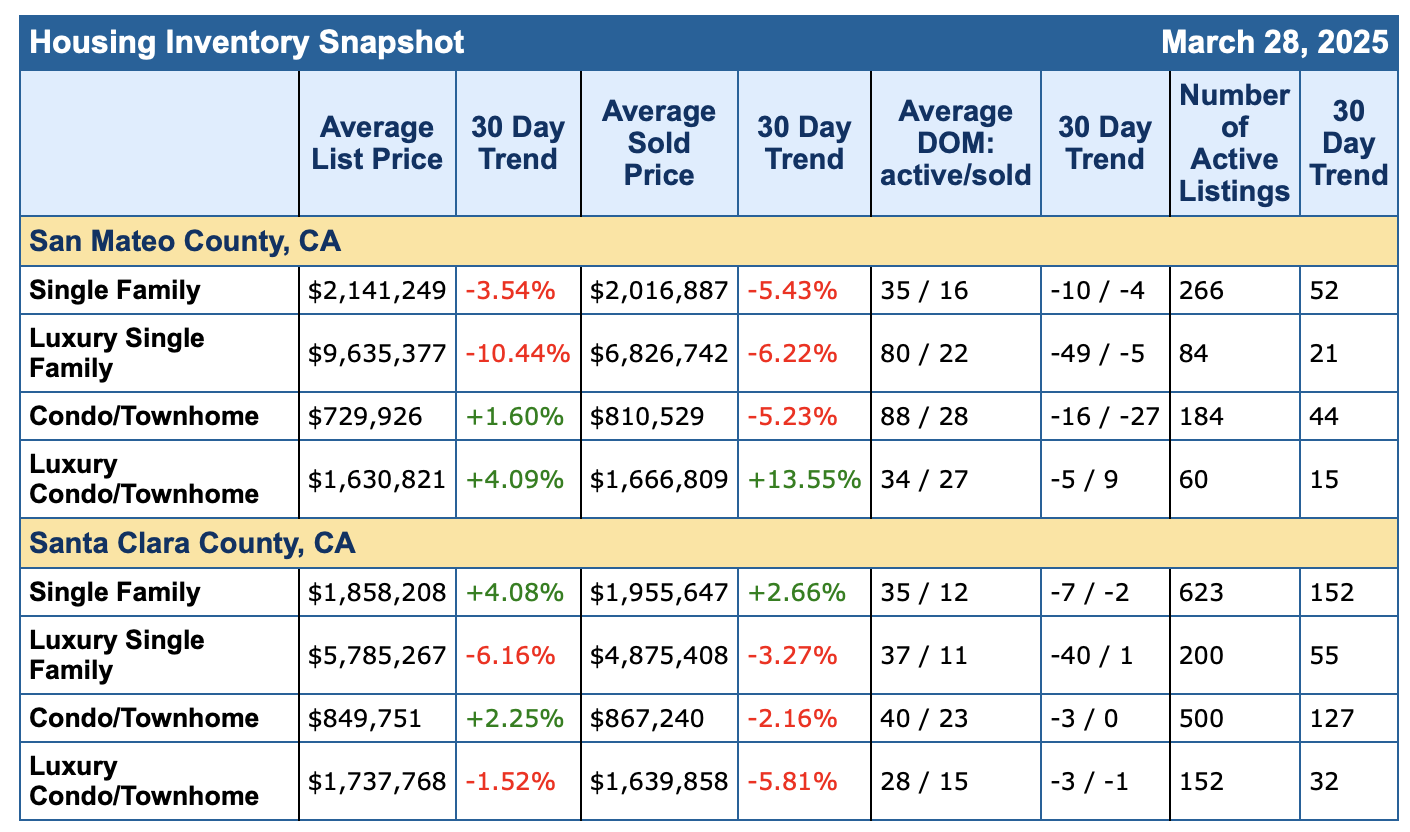
What gain we saw in Feb has tempered in March. We are midway through April and I can feel the cold thawing. Buyers are doing their homework, loan shopping and budget making. While sellers are getting their homes ready for the Spring Market that officially starts on May 1. Are you ready?

There was slight price adjustments in March, which still feels seasonal. Buyer right now are weighing so much, the interest rates haven’t fallen much, hovering around 6%+, the state of the economy and the world has folks on edge. But not off the table. With caution and a solid plan, I am seeing my clients make their Real Estate goals work! How can The Caton Team help you?

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at info@TheCatonTeam.com.

Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 40 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

How to Help Your Children Buy a Home – Shared Article

I read this article HERE.
By Emma Patch

Options range from family loans to outright gifts to help your children buy a home.

If you want to help your children buy a home there are a number of ways to go about it, ranging from family loans to outright gifts. This is especially pertinent to consider as lofty home prices, rising mortgage rates and a tight inventory of homes for sale have shut many young buyers out of the housing market.

The median age of home buyers in 2024 was 56, according to the National Association of Realtors, representing a jump from 2023’s already high median of 49. Overall, this indicates first-time home buyers are delaying their purchases. The typical first-time buyer was 38, an all-time high. 

With that in mind, parents (and grandparents) of would-be home buyers are often interested in helping out. Their options include gifting a down payment, co-signing a mortgage, jointly owning a home, making a loan, and buying a home outright for their children or grandchildren. Each of these avenues of financial support has its own perks and pitfalls. 

1. Provide an intra-family loan

One option that could benefit both parties is an intra-family loan. You may be able to offer your child a lower interest rate than a conventional mortgage lender would while still earning a higher interest rate than you could earn from a savings account.

For example, if you provide your child with a mortgage at a 4.5% interest rate, you’ll earn almost four percentage points more than the 0.55% average yield for a bank savings account. Your child, meanwhile, will pay significantly less than the national average for a 30-year fixed-rate mortgage. 

An intra-family loan works especially well for well-off individuals who can afford to give their children the money but prefer the financial discipline that comes with a loan, said Tim Burke, chief executive officer of National Family Mortgage, a family lending agency.

“For many parents, the motivation to lend money over gifting it is just about personal accountability,” he said. “Parents feel the responsibilities that come with homeownership, and the satisfaction that comes with meeting these responsibilities builds character.”

That was the case for Mary and Terry Shaffer of Pittsburgh, who lent money to both of their children to buy homes in that city. “Our son and our daughter do not like things handed to them, although they deserve to be helped,” said Mary, 68. “They have worked hard, and they both had accumulated savings for their closing costs.”

If parents need assurance that their child can afford the monthly payments, they should ask the child to get preapproved for a conventional mortgage, Burke said. However, that could be difficult for some children, especially if they’re self-employed borrowers. Even if a self-employed individual’s debt-to-income ratio — the amount of debt you owe as a percentage of your monthly income — may support a loan, a single year in which income declines may cause a bank to reject the application. 

If your child can’t get preapproval, it comes down to your judgment. “If you think your family member is not going to repay you, then don’t go through the exercise of setting up a loan that isn’t going to work,” Burke said.

Put the terms of the intra-family loan in writing so they’re clear and it’s an arm’s-length transaction, said Brian Lamborne, senior director of advanced planning at Northwestern Mutual. Putting the terms of the loan in writing can also help you deal with instances in which your children are unable to make payments. For example, you can agree ahead of time that should your child suffer financial hardship, payments will be deferred for a certain period of time — perhaps six months or up to a year — and moved to the end of the loan. 

The loan agreement should contemplate worst-case scenarios as well. For example, you may want to state the conditions under which the parents could foreclose on the property so they can sell it and pay off the loan. 

It’s also important to understand the tax implications for intra-family loans. Borrowers who itemize can only deduct interest on a loan secured by a mortgage if the mortgage has been properly recorded. In order to do that, families need to obtain a deed of trust and file it with the borrower’s local government authority, such as the registrar of deeds or country clerk’s office. A real estate attorney can help you draw up these documents. 

If the loan exceeds $10,000, the IRS requires you to charge an interest rate equal to or above the Applicable Federal Rate (AFR), which the IRS publishes monthly. The interest must be reported as income on your tax return.

If you don’t want to act as the loan servicer, you could use National Family Mortgage to set up, document and service the loan. It will email payment reminders and monthly statements, collect and credit payments, and issue year-end IRS 1098 and 1099-INT tax forms. The cost is a one-time fee of $725 to $2,100, depending on the size of the loan, and optional loan servicing starting at $15 per month.

2. Give a gift

For some families, the easiest solution is to give children enough money to make a down payment or buy a house outright. Gifting spares families the hassle of a loan and damage to their relationships if a loan can’t be repaid.

Mortgage lenders generally allow a relative to supply the entire down payment, but they will require a letter that provides the name of the giver, the amount of the gift and a statement that the giver doesn’t expect to be repaid. 

As is the case with a loan, it’s important to understand the tax implications of this transaction. In 2025, you can give up to $19,000 per person to as many people as you’d like without having to file a gift tax return. Married couples can give up to $38,000 per person. 

Any amount over the annual limit will reduce your exemption from the federal estate and gift tax. This isn’t a problem for most families because the federal estate tax exclusion is $13.99 million for 2025 or $27.98 million for married couples. However, if Congress fails to extend the 2017 Tax Cuts and Jobs Act, the exclusion will drop to about half that in 2026. 

In any event, parents or grandparents should only give a gift they can afford without jeopardizing their own financial security. “There are no loans when it comes to your own retirement,” said Jennifer Weber, a CFP in Lake Success, N.Y. “So only help in ways that you can afford now and in the future.”

3. Co-sign or co-borrow

If your child can’t qualify for a mortgage based on their own income and credit record but can afford monthly payments, co-signing a mortgage is one way to help them buy a home. However, it can be risky. 

A co-signer acts as a guarantor for the primary borrower, promising to assume responsibility for repayment if the primary borrower doesn’t pay as required. The lender will review your sources of income and your credit to ensure your income is high enough and your credit strong enough to qualify for a mortgage. 

If your child falls behind on monthly payments, your own credit could suffer. Plus, co-signing for a mortgage will increase your own debt-to-income ratio which could make it more difficult for you to borrow for your own purposes. Also, some lenders don’t allow co-signers. 

In another arrangement, a co-borrower or joint applicant shares ownership of the loan and assumes responsibility for payments from the start. In general, you and your child combined must put down at least 20%, and your child must cover the first 5% of the down payment from their own funds.

Otherwise, the property may qualify as an investment, in which case you’ll be charged a higher interest rate for the loan and be required to have more financial reserves. But if your child fails to pay the mortgage, property taxes or insurance on time, that could ding your credit history or result in a lien against the property. 

One extra consideration

You should make sure to consider how any assistance could affect family relationships. Your children or their spouses may be anxious or uncomfortable about accepting financial help from parents or in-laws. Siblings feelings matter, too.

“If you have multiple children, spend some time upfront to understand how giving or loaning to one child might affect family dynamics,” said Mitchell Kraus, a certified financial planner based in Santa Monica, Calif. “We’ve seen years of resentment coming from a small loan to one family member when it was not available to another.”

Got Questions? The Caton Team is here to help.

Cell| Sabrina 650.799.4333 | Susan 650.796.0654 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team from our TESTIMONIALS.

Effective. Efficient. Responsive. The Caton Team 🏡  

How Can The Caton Team Help You?

TESTIMONIALS | HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TRUST AGREEMENTS | HEALTH CARE DIRECTIVESTESTIMONIALS

Get exclusive inside access when you follow us on Facebook & Instagram

TESTIMONIALS | HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TRUST AGREEMENTS | HEALTH CARE DIRECTIVESTESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or some guidance – we are here for you. Contact us at your convenience – we are but a call, text, or click away!

The Caton Team believes, in order to be successful in the San Francisco | Peninsula | Bay Area | Silicon Valley Real Estate Market, we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Cell | Sabrina 650.799.4333 | Susan 650.796.0654 | EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

Website | The Caton Team Testimonials | Our Blog – The Real Estate Beat | Search for Homes | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina | Photography | Photography Blog 

Berkshire Hathaway HomeServices – Drysdale Properties, Redwood City Ca.

DRE # | Sabrina 01413526 | Susan 01238225 | Team 70000218 | Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

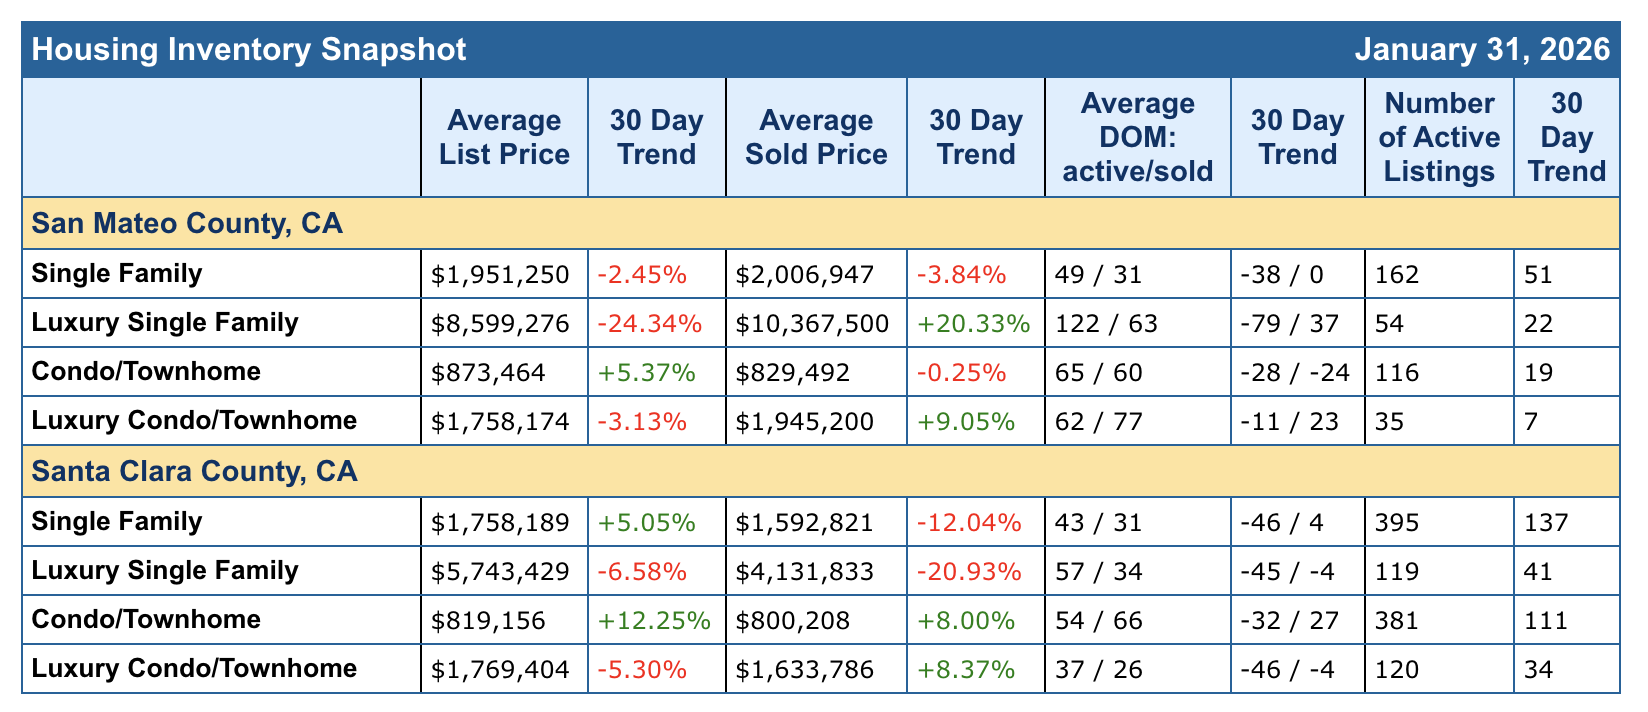
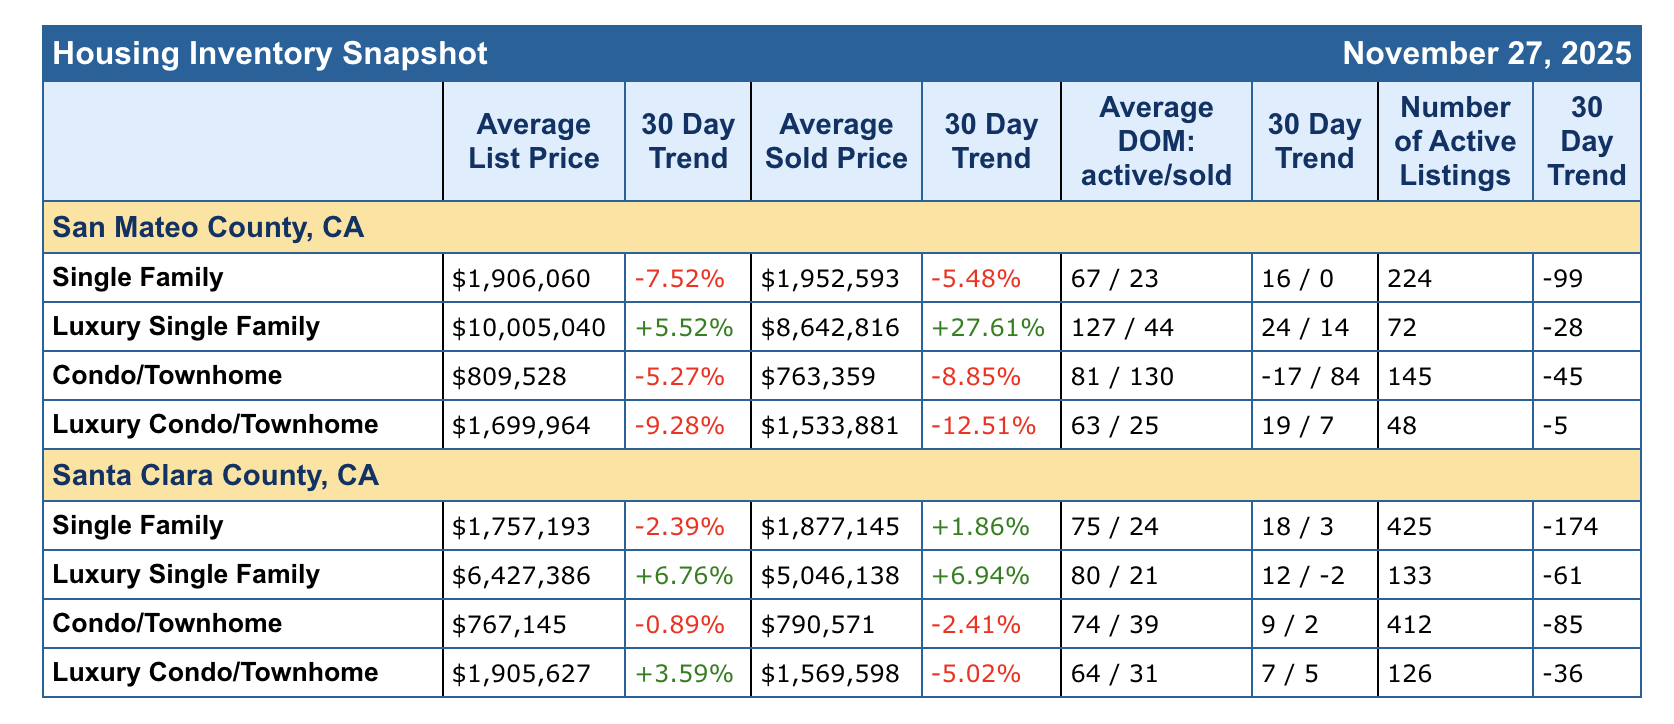
The Stats are In… Market Snapshot for Dec 2025 & Jan 2026

Hello Caton Team Friends,

The stats are in for Jan 2026 and December 2025. We saw a healthy December in San Mateo County with some adjustments in January. In my experience, in line with the habitual behavior of buyers in Winter. Condos are going strong, for those without balcony issues – which is a good indication of growth. We see the condo market as the first step to home ownership so we want to see healthy sales there, as buyers sell their condos and move into larger spaces, opening up that first rung to the next buyer.

What are your thoughts for the year ahead?

For my selling clients, life changes everyday and if you need to sell your home – let’s come up with a strategy to get you sold! Even in an odd market The Caton Team can help you strategically sell your home.

For my buyers, some homes are garnering multiple offers, but some are overlooked. With a little legwork, a buyer can truly find some great opportunities when they align with the market.

If you’re considering a Real Estate move, contact The Caton Team for a free consultation. With over 45+ years of combined Real Estate experience, we have the knowledge and know-how to guide you to your goal. Call us at 650.799.4333 or email us at info@TheCatonTeam.com.

Let’s see our month over month

How can The Caton Team Help You?

Contact The Caton Team 650.799.4333 | Email Info@TheCatonTeam.com

Whether you are selling or buying – today or tomorrow – contact The Caton Team – we’re happy to help you achieve your Real Estate goals. 

Effective. Efficient. Responsive. The Caton Team 🏡 

Each market is unique and with over 40 years of combined Real Estate experience, The Caton Team is more than happy to be of service if and when you are considering a move. Contact us anytime during your journey, together we’ll help you achieve your Real Estate goals.

Got Questions? The Caton Team is here to help.

Call | Text | Sabrina 650.799.4333 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team TESTIMONIALS.

| HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

RECENTLY SOLD by THE CATON TEAM

Homes Sold by The Caton Team | Helping Our Buyers Find Their Way Home
Get exclusive inside access when you follow us on Facebook & Instagram

| HOW TO SELLGET READY CAPITAL – Loans to Prep for Sale | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or need some guidance – we are here for you. Contact us at your convenience – we are but a call, text or click away!

The Caton Team believes, in order to be successful in the San Fransisco | Peninsula | Bay Area | Silicon Valley Real Estate Market we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined, local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Call | Text | Sabrina 650.799.4333 | Susan 650.796.0654 |EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

The Caton Team Testimonials | Blog – The Real Estate Beat | TheCatonTeam.com | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina

Berkshire Hathaway HomeServices – Drysdale Properties

DRE # |Sabrina 01413526 | Susan 01238225 | Team 70000218 |Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

5 key steps before you begin a home search – Shared Article

I read this article HERE. By Javan Yoder

Buying a home for the first time can be a rewarding experience. A home is an investment and place for you and your family to call your own. There are many steps involved in purchasing a home. Before you fall in love with a property or contact a real estate agent, it is important to make sure your finances are in order. To help your home purchase go smoothly, you should know where you stand financially. To help you assess your financial fitness for your home purchase, consider the following:

Check your credit score. An important first step is checking your credit score. Your score will help you determine the financing options available to you and your score will impact your mortgage terms. Lenders check credit scores to determine if a borrower has a record of on-time payments to gauge the likelihood of repaying the mortgage. The higher your credit score, the more financing options and lower interest rates will be available to you.

Set a realistic budget.  How much house can I afford is one of the first questions first-time home buyers ask themselves. Experts say that your total monthly home expenses should not exceed more than one-third of your gross monthly income. As you prepare a budget, make sure to include your estimated housing costs and down payment. Your estimated housing costs should not only include your mortgage payment but also other factors such as your estimated annual property taxes, home insurance and loan terms (how long you would like to pay off your mortgage).

Shop around for a mortgage rate. To secure the best financing deal for your new home, make sure to shop around for a home loan. Comparing costs may save you a significant amount of money in the long run. If you need assistance, a mortgage lender can help provide guidance on the various loan options available. There are several types of mortgages available, including FHA, conventional, adjustable rate, and fixed rate. You’ll need to learn more about each mortgage to figure out which option works best for you.

Know your down payment options. The longstanding first-time home buyer myth is that you need a 20-percent down payment to purchase a home. There are several loan programs and options available to allow buyers to move forward with purchasing a home with a smaller down payment. Determining how much you should put down is a personal decision based on your financial status.

Get pre-qualified or pre-approved for a mortgage. While the terms seem interchangeable, they vary in terms of purchasing a home. If you get pre-qualified for a home, you’ll learn how much money you will be able to borrow based on your financial profile, which includes a credit check. When you pre-qualify, you learn more about your financial readiness and will get an introduction to the mortgage options available to you. To get pre-approved for a mortgage, you provide more details about your financial status to a lender as well as a credit check. After the lender verifies your information, you will receive a letter of the amount and type of mortgage available to you. In a competitive real estate market, a pre-approval letter shows sellers and real estate agents that you are a serious buyer ready to make an offer on a home.

Got Questions? The Caton Team is here to help.

Cell| Sabrina 650.799.4333 | Susan 650.796.0654 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team from our TESTIMONIALS.

Effective. Efficient. Responsive. The Caton Team 🏡  

How Can The Caton Team Help You?

TESTIMONIALS | HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TRUST AGREEMENTS | HEALTH CARE DIRECTIVESTESTIMONIALS

Get exclusive inside access when you follow us on Facebook & Instagram

TESTIMONIALS | HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TRUST AGREEMENTS | HEALTH CARE DIRECTIVESTESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or some guidance – we are here for you. Contact us at your convenience – we are but a call, text, or click away!

The Caton Team believes, in order to be successful in the San Francisco | Peninsula | Bay Area | Silicon Valley Real Estate Market, we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Cell | Sabrina 650.799.4333 | Susan 650.796.0654 | EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

Website | The Caton Team Testimonials | Our Blog – The Real Estate Beat | Search for Homes | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina | Photography | Photography Blog 

Berkshire Hathaway HomeServices – Drysdale Properties, Redwood City Ca.

DRE # | Sabrina 01413526 | Susan 01238225 | Team 70000218 | Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.

Forget wedding registries — many newlyweds would rather you help pay their mortgage – Shared Article

Key Points

  • Gen Z and millennial homebuyers are struggling in the real estate market.
  • To make homeownership more affordable, some buyers are turning to their friends and family.
  • A Zillow expert told BI that 20% of wedding registries now include house funds.

I read this article HERE. By Alcynna Lloyd

It’s no secret that becoming a homeowner is financially out of reach for many millennials and Gen Z buyers.

Zillow data shows that in 2025, the typical median-income family would need to earn about $17,670 more this year than last to afford the mortgage on a typical US home.

It couldn’t happen at a worse time.

While home prices are dipping in some cities, they remain high nationwide. And even though mortgage rates have edged lower week by week, they’re still hovering around 6% — a far cry from the 3% range seen just a few years ago. All this is unfolding against the backdrop of a sluggish economy and a job market marked by slower wage growth and a wave of layoffs hitting employers both small and large.

However, Zillow’s home trends expert Amanda Pendleton notes that some young homebuyers are finding a workaround — by asking friends and family to help them fund a home purchase.

“Spoiler alert, they’re not doing it alone. Thirty-eight percent of all buyers today are getting some kind of gift or loan from a family member or friend. And another fun stat — 20% of wedding registries now include house funds,” Pendleton told Katie Notopoulos on Business Insider’s new video podcast, “Well Spent.”

‘We would rather have wedding money spent toward a home than getting gifts”

Turning to family and friends is exactly what Aislyn and Ali Benjamin did when they got married in 2022.

The California couple didn’t want traditional wedding gifts like kitchen appliances, or anything that would be forgotten and gather dust in a few years. Instead, they asked their guests for cold, hard cash to help fund the construction of their first home.

It’s easy to understand why. The Benjamins both run small businesses in Danville, California, a city about an hour east of San Francisco, where the median home price was $1.8 million in September, according to Zillow. Buying a home in the city was unrealistic, and renting wasn’t a long-term solution. For them, building an accessory dwelling unit (ADU) in Ali’s parents’ backyard in San Ramon just eight minutes from Danville was their best shot at homeownership.

And why not use a day when everyone was already celebrating them to help make it happen?

“I just made a GoFundMe, and we sent it out with our invites so people could contribute through the online link,” Aislyn, 30, told Business Insider.

In total, the couple raised $5,545 on GoFundMe and received about another $5,000 in cash, checks, and other gifts at their wedding, bringing their total to about $10,000.

That money, along with help from Ali’s parents, allowed them to build a 1,200-square-foot ADU by Bay-area-based company Villa for $500,000. They also financed the project with a mortgage.

The exterior of an ADU home.
The Benjamins’ ADU. Courtesy of Villa

“It gave us a little bit of a head start and a buffer, allowing us to not have to save up quite as much money,” Ali Benjamin, 35, told Business Insider.

“We would rather have wedding money spent toward a home than getting gifts.”

Got Questions? The Caton Team is here to help.

Cell| Sabrina 650.799.4333 | Susan 650.796.0654 |  EMAIL  |  WEB  |   BLOG

We love what we do and would love to help you navigate your sale or purchase of Residential Real Estate. Please reach out for a personal consultation. Please enjoy our free resources below and get to know our team from our TESTIMONIALS.

Effective. Efficient. Responsive. The Caton Team 🏡  

How Can The Caton Team Help You?

TESTIMONIALS | HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TRUST AGREEMENTS | HEALTH CARE DIRECTIVESTESTIMONIALS

Get exclusive inside access when you follow us on Facebook & Instagram

TESTIMONIALS | HOW TO SELL | VIRTUAL STAGING | A GUIDE TO BUYING | BUYING INFO |  MOVING | TRUST AGREEMENTS | HEALTH CARE DIRECTIVESTESTIMONIALS

Got Real Estate Questions?   The Caton Team is here to help.

We strive to be more than just Realtors – we are also your home resource. If you have any real estate questions, concerns, need a referral, or some guidance – we are here for you. Contact us at your convenience – we are but a call, text, or click away!

The Caton Team believes, in order to be successful in the San Francisco | Peninsula | Bay Area | Silicon Valley Real Estate Market, we have to think and act differently. We do this by positioning our clients in the strongest light, representing them with the utmost integrity, while strategically maneuvering through negotiations and contracts. Together we make dreams come true.

A mother and daughter-in-law team with over 35 years of combined local Real Estate experience and knowledge – wouldn’t you like The Caton Team to represent you? Let us know how we can be of service. Contact us any time.

Cell | Sabrina 650.799.4333 | Susan 650.796.0654 | EMAIL |  WEB|   BLOG

The Caton Team – Susan & Sabrina
A Family of Realtors
Effective. Efficient. Responsive.
What can we do for you?

Website | The Caton Team Testimonials | Our Blog – The Real Estate Beat | Search for Homes | Facebook | Instagram | HomeSnap | Pinterest | LinkedIn Sabrina | Photography | Photography Blog 

Berkshire Hathaway HomeServices – Drysdale Properties, Redwood City Ca.

DRE # | Sabrina 01413526 | Susan 01238225 | Team 70000218 | Office 01499008

The Caton Team does not receive compensation for any posts.  Information is deemed reliable but not guaranteed. Third-party information not verified.